Renwick Evans and Associates
  • Blog Home
  • Categories
    • Startup Launch Guidance
    • Cash Flow, Funding & Capital Strategies
    • Business Operations, challenges & Solutions
    • Merchant Processing & Payments
    • Business Marketing That Works
    • Business Growth & Scaling
    • Business Consulting Insights
    • Compliance & Risk Management
  • Home
May 05.2026
1 Minute Read

Understanding Processing Fees for New Small Businesses

Did you know that nearly 60% of small business owners underestimate how much merchant processing fees impact their bottom line? If you’re starting a new business or accepting card payments for the first time, understanding these fees can make the difference between profit and pain
Small business owner reviewing merchant processing fees at a cozy, sunlit office desk with a laptop and calculator

The Real Impact of Merchant Processing Fees: Why Every Dollar Counts for Small Businesses

For many new small businesses, merchant processing fees can easily be overlooked when budgeting or setting prices. Yet, these costs—typically charged by payment processors to handle credit card, debit card, and other card payments—directly affect your profitability. Each time a customer swipes, taps, or inserts their card, a fee is deducted from the transaction, paid to the card networks, your payment processor, and sometimes the bank that issued the card.

"Nearly 60% of small business owners underestimate how much merchant processing fees impact their bottom line."

The challenge is that merchant processing fees can range anywhere from 1.5% to over 4% per transaction, depending on your provider, the card type, and your industry. For a business operating with slim margins, these fees can quickly eat away at profits. For example, if your average sale is $50 and you process 500 transactions per month with an average 3% fee, you’ll pay $750 in processing fees alone each month. For new business owners, every dollar counts—so understanding, tracking, and minimizing these fees sets the groundwork for business growth and financial stability.
Small business owner reviewing merchant processing fees at a cozy, sunlit office desk with a laptop and calculator

What You'll Learn About Merchant Processing Fees

  • A breakdown of what merchant processing fees are and why they matter
  • In-depth explanation of credit card, card processing, and transaction fees
  • How to compare card processing fees and payment processor pricing models
  • Legal considerations and tips for minimizing processing fees

Defining Merchant Processing Fees for Small Businesses

What Are Merchant Processing Fees?

Merchant processing fees are the costs your business pays each time you accept a card payment, whether by credit card, debit card, or other electronic means. These fees are typically split among three main players: the payment processor (the company that handles the transaction), the card network (like Visa, MasterCard, or American Express), and the card issuer (the bank that issued the customer’s card). The cost is usually deducted automatically from the sales amount, meaning you receive the net revenue after the fees are taken out.

Many small businesses are surprised by how many types of fees are involved, from the basic card processing fees to interchange fees, assessment fees, and sometimes additional monthly or incidental charges. Knowing precisely what you’re paying—and why—allows you to make informed choices when selecting a payment processor or setting your store’s card payment policies.
Cashier swiping a credit card at a modern point-of-sale terminal to illustrate card processing fees

How Merchant Processing Fees Impact New Businesses' Profitability

Every percentage point in merchant processing fees comes directly out of your profit. For example, if you sell $10,000 in goods and accept payment cards, a 3% credit card processing fee would cost you $300. For small businesses just starting out, this can mean the difference between breaking even and being in the red. Processing fees don’t just chip away at your revenue—they affect your pricing power, ability to compete, and long-term sustainability.

"Merchant processing fees can reduce profit margins by up to 4% per transaction if unchecked."

Even within just a few months of business, unchecked or poorly understood fees may add up to hundreds—sometimes thousands—of dollars. That’s why it’s so important to monitor, analyze, and regularly renegotiate your credit card processing agreements, and to educate your team about the significance of every card swipe.

As you evaluate your options, it's also helpful to compare how different payment processors structure their fees and what features they offer. For a practical breakdown of leading providers and their pricing models, check out our guide to building a strong small business, which includes insights on choosing the right payment solutions for your needs.

Key Terms: Credit Card, Card Processing, and Processing Fees Explained

What are Credit Card Processing Fees and Why Do They Exist?

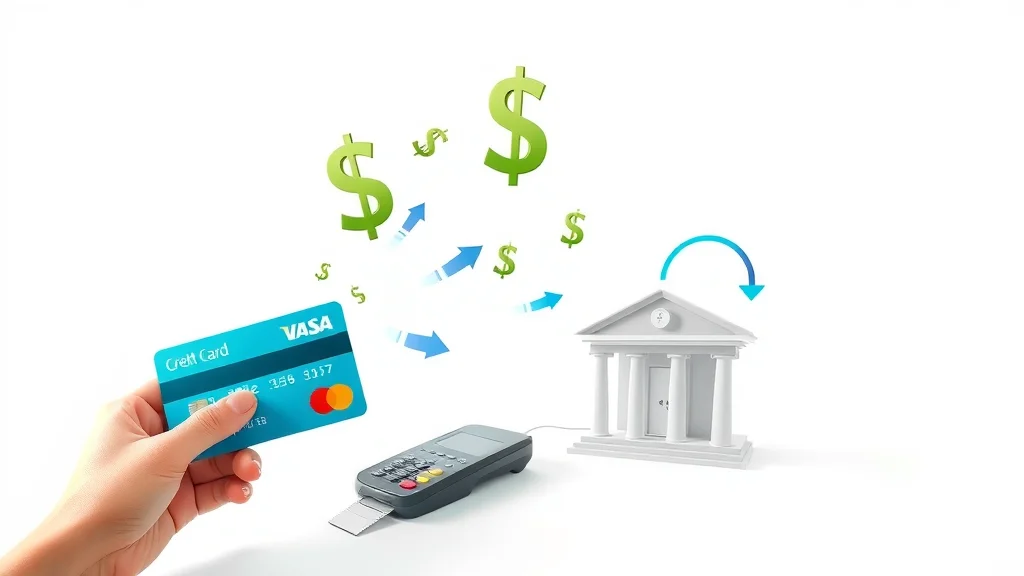
Credit card processing fees are the charges that payment processors and card networks impose for handling credit card transactions. These fees exist to cover the costs related to fraud prevention, transaction processing, and the infrastructure that makes card payments possible. When a customer uses a credit card, a complex system of networks, banks, and technology enables the payment to move from their account to yours—each taking a small share for the service.

The most common types of card processing fees include interchange fees (paid to the card issuer), assessment fees (paid to the card network), and processor fees (for the services of the payment processor). These costs can be fixed or variable depending on the card type, transaction amount, and your processing volume. Understanding these terms is essential for every new business aiming to minimize their costs.
Infographic illustrating the flow of credit card processing fees between card, terminal, and banks

Understanding the Role of Card Processing in Small Business Transactions

The process of accepting card payments is more complex than it seems at first glance. When you, as a merchant, accept a credit card or debit card payment, several entities are involved: the cardholder (your customer), the merchant (your business), the acquiring bank (your business’s bank), the issuing bank (the cardholder's bank), and the card network (like Visa or MasterCard). Each step in this process incurs a small fee, which adds up to your total card processing costs.

This multi-layered transaction process is why processing fees exist. It’s also why you may notice different rates for different types of transactions. For example, swiping a physical card (card present) is considered lower risk and often comes with a lower fee than entering card numbers online (card not present), which can be more susceptible to fraud.

A Detailed Look at Transaction Fee and Processing Fee Structures

Not all merchant processing fees are created equal. You’ll likely encounter a combination of flat-rate fees, per-transaction fees, and additional charges for things like chargebacks or monthly statements. Most providers disclose these in their contracts, but understanding what each fee represents is the first step in managing them.

For instance, some providers charge a fixed percentage plus a fixed amount per transaction, such as 2.9% + 30¢. Others may separate out assessment fees and interchange fees (we’ll define these next). Knowing the structure of your payment processor’s fees lets you estimate costs more accurately and spot opportunities to save as your business grows.

The Components of Merchant Processing Fees

Interchange Fees: How Card Networks and Issuers Get Paid

Interchange fees form the largest portion of most merchant processing costs. These fees are set by the card networks (like Visa, MasterCard, Discover, and American Express) but are paid to the card issuer—the bank that issued your customer’s card. Interchange fees vary widely based on the type of card used (credit card vs. debit card), how the transaction is made (in-person vs. online), and your business industry.

For example, debit card transactions tend to have lower interchange fees than credit cards, while rewards cards and premium cards may incur higher costs. Understanding interchange fees gives you leverage when comparing processing providers and setting payment policies. Many processors now provide detailed breakdowns of how much you’re paying in interchange for each transaction.
Financial analyst displaying pie chart of interchange, assessment, and processor fee breakdowns for merchant processing fees

What Are Assessment Fees and How Do They Affect Your Processing Fees?

Assessment fees are small charges collected by the card networks themselves, separate from the interchange fee. While interchange fees are paid to the card issuer, assessment fees are retained by Visa, MasterCard, or the other card network facilitating the transaction. These fees are usually much smaller—often a fraction of a percent—but they do add up over thousands of transactions.

While you can’t negotiate assessment fees directly (they’re set by the card networks), being aware of them helps you understand and audit the total cost structure in your monthly statements. Look for assessment fees alongside interchange fees and processor fees when analyzing where your money is going.

Payment Processor Fees: Comparing Leading Providers for Small Businesses

Unlike interchange or assessment fees, the processor fee is the cost added by the company you choose for payment processing. This is where you have the most flexibility and negotiating power. Some providers use flat-rate models, while others use interchange-plus (passing interchange fees directly to you with a set markup) or tiered structures. Leading providers for small businesses include Square, Stripe, PayPal, Clover, and traditional banks—all with different fee models and support levels.

Comparing processor fees is crucial for cutting costs. Some charge monthly fees, batch fees, or inactivity fees in addition to per-transaction costs. Always ask for a clear breakdown of all processor charges before signing an agreement.

Comparison Table: Interchange, Assessment, and Processor Fee Breakdown
Provider Interchange Fee Assessment Fee Processor Fee Other Monthly Fees
Square Passed through Included in rate 2.6% + 10¢ per swipe None
Stripe Passed through Included in rate 2.9% + 30¢ per transaction None
PayPal Passed through Included in rate 2.99% + 49¢ per transaction None
Clover (Bank) Varies by volume/type Varies Interchange-Plus or tiered $5–$20 monthly typical

Exploring Pricing Models for Merchant Processing Fees

Flat-Rate vs. Interchange-Plus: Which Pricing Model Suits New Businesses?

Two of the most common pricing models for merchant processing fees are flat-rate and interchange-plus. Flat-rate pricing providers, like Square and PayPal, charge a fixed percentage plus a small fee per transaction. This model is simple, predictable, and ideal for businesses starting out with lower or less predictable volumes.

Interchange-plus pricing passes the actual interchange and assessment fees onto the merchant, adding a consistent markup from the processor. While this model is more transparent and can result in lower overall costs for higher-volume businesses, it is less predictable and requires careful statement review. For many new small businesses, starting with flat-rate can make budgeting easier—while established businesses may benefit from negotiating an interchange-plus model as volume grows.
Business owner comparing flat-rate and interchange-plus card processing pricing models on colorful printed statements

Tiered Pricing Explained: Is It Right for Your Business?

Some payment processors offer tiered pricing, which groups your transactions into categories such as qualified, mid-qualified, and non-qualified, with each tier carrying a different rate. While it may seem straightforward, tiered pricing can lead to unexpected charges, especially on reward cards, corporate cards, or online transactions. Many small business owners find their most common transactions fall into higher, more expensive tiers.

It’s vital to understand exactly which transactions fall into which tiers and what the actual rate structure is. Tiered pricing can sometimes mask higher transaction fees, so ask your provider for a detailed fee schedule.

Monthly Fees, Transaction Fees, and Hidden Costs Revealed

Beyond the per-transaction fees, merchants must keep an eye out for monthly fees (like statement or PCI compliance fees), minimum processing fees, and batch or settlement fees. Some providers may also charge equipment rental fees, early termination charges, or inactivity penalties. These hidden costs can quickly add up, erasing the savings from lower advertised rates.

"Always read the fine print before signing up with a payment processor—tiered pricing can hide high transaction fees."

Review your statements every month and don’t hesitate to ask for clarification or renegotiate if you spot new or unexplained charges. The most successful small businesses brutally track and challenge every processing fee.

How Card Type Impacts Merchant Processing Fees

Credit Card, Debit Card, and American Express: Fee Structure Comparison

Not all cards cost the same to process. Generally, accepting a debit card (where customers use a PIN or signature) costs less than processing a credit card transaction. American Express transactions tend to have the highest processing fees, due to Amex’s unique card network structure and fee policies. Merchants can pay from under 1.5% for debit cards to over 3.5% for some corporate or reward cards, especially American Express.

Every merchant should evaluate what percentage of sales are from debit cards, credit cards, and specific brands, then factor this into negotiations with processors and in pricing policies. Where possible, encouraging customers to use lower-fee payment methods (like debit or ACH) can result in significant savings.
Hand holding credit card, debit card, and American Express card to compare card processing fees in a retail setting

Card Networks and Card Processing Fee Variances

The card network—such as Visa, MasterCard, Discover, or Amex—affects your processing fees as each sets its own fee schedules and assessment fees. In general, Visa and MasterCard are similar, Discover can be slightly higher, and American Express typically carries the highest rates for merchant processing fees.

Depending on your business type and customer profile, it may make sense to accept only the card networks that offer favorable rates, or to negotiate blended rates with your payment processor that averages out the differences.

Table: Typical Fees for Major Card Networks and American Express
Card Network Credit Card Transaction Fee Debit Card Transaction Fee Assessment Fee
Visa 1.5% - 2.5% + 10¢ 0.5% - 1.5% + 10¢ 0.13% - 0.14%
MasterCard 1.5% - 2.6% + 10¢ 0.6% - 1.6% + 10¢ 0.13% - 0.14%
Discover 1.6% - 2.7% + 10¢ 0.6% - 1.6% + 10¢ 0.13% - 0.14%
American Express 2.3% - 3.5% + 10¢ N/A Varies (generally included)

Factors Affecting Merchant Processing Fees for New Small Businesses

Business Type, Industry, and Average Transaction Size

Your industry type and business model significantly influence your merchant processing fees. High-risk businesses (those with more frequent chargebacks or refunds, or operating online without card-present transactions) often pay higher rates than low-risk, brick-and-mortar businesses. Similarly, businesses with small average ticket sizes often see higher relative costs due to fixed per-transaction fees.

For example, a coffee shop processing many small transactions may experience more impact from the 10–30¢ per-transaction component than a high-volume retailer selling big-ticket items. Always discuss your expected sales patterns with potential payment processors to find the best fit.
Group of entrepreneurs from different business types using POS devices, showing how processing fees vary by industry and average transaction size

Card Not Present vs. Card Present Transactions

Processing card payments where the card is not physically present (such as for online orders or phone sales) generally incurs higher fees. This is because such transactions are viewed as riskier and more susceptible to fraud by card networks. Conversely, in-person card-present transactions, especially those using chip and PIN technology, tend to offer lower processing fees.

As a new business, adopting technology that supports chip cards and contactless payments can help keep your processing fees in check and reduce fraud risk.

Processor Negotiation Power and Rate Customization

Don’t assume that processing rates are set in stone—negotiation is possible, especially as your volume grows or if you can demonstrate consistent transactions. Some processors can offer customized solutions or bundled services, provide discounts for certain payment methods, or even waive certain monthly or setup fees for new businesses.

Periodically comparing your statements and competing offers ensures you’re not overpaying. Leverage your transaction data and be prepared to switch providers if another can deliver genuine savings or better support.

Legal Considerations: Credit Card and Card Processing Fee Regulations

Is It Legal to Charge a Credit Card Processing Fee to Customers?

In the US, it is generally legal to add a surcharge to offset credit card processing fees—but only if you follow state laws and the specific rules of card networks. Surcharging remains complicated, as laws can vary considerably between states and card networks set requirements for how surcharges are disclosed and capped.

State Regulations and Card Network Rules Impacting Processing Fees

Some states, such as Colorado and Massachusetts, have laws limiting or prohibiting surcharges on card transactions, while others require clear customer disclosures. Card network rules (especially from Visa and MasterCard) also mandate maximum surcharge limits, notification requirements, and consumer transparency.

Before implementing surcharges or passing on costs to customers, consult legal counsel or your payment processor to ensure compliance.

What You Should Know About Surcharging, Cash Discounts, and Compliance

Beyond surcharges, businesses can explore cash discount programs (offering a discount for non-card payments) or set minimum purchase amounts for card use (within card network rules). However, compliance is critical—violations can result in fines or loss of processing privileges.

"Consult a legal expert or payment processor before adding surcharges—penalties for non-compliance can be significant."

Properly disclose all fees to customers and maintain records to prove your compliance with both state and card network requirements.

How to Minimize Merchant Processing Fees: Strategies for Small Businesses

  • Shop around: Comparing credit card processing providers often yields significant savings and better terms.
  • Choose the right pricing model: Match your transaction volume and patterns to the model that offers the most cost-effective results.
  • Negotiate better rates: Don’t accept the first offer; use your transaction history to seek better rates or bundled services.
  • Encourage lower-fee payment methods: Promote debit card and ACH payments, which may cost less than traditional credit card transactions.
Professional business owner sealing a deal with a payment processor to reduce merchant processing fees

Case Study: Handling Card Processing Fees as a New Business

Startup Example: Reducing Costs with Interchange-Plus Pricing

Consider a startup café processing $20,000 in monthly sales. Initially, they sign up with a flat-rate processor at 2.9% + 30¢ per transaction. After reviewing their statements, they discover a competitor offers interchange-plus pricing with an average effective rate of 2.2%. They switch providers, saving $140 per month—or $1,680 per year.

Their diligence in reviewing statements, negotiating rates, and choosing the right pricing model directly improved their profit margins and ability to reinvest in the business. This proactive approach is a template for all new small businesses juggling thin margins and competitive markets.
Entrepreneur analyzing bar graph showing merchant processing fee savings after switching to interchange-plus pricing

People Also Ask About Merchant Processing Fees

What is the merchant processing fee?

Merchant processing fees are charges that businesses pay to accept card payments, including credit card processing, card processing fees, and assessment fees imposed by card networks and processors.

Is it illegal to charge the customer 3% credit card fee?

In many states, surcharging is allowed with specific conditions, but businesses must follow card network rules and local laws to remain compliant.

How much is a 3% processing fee?

A 3% processing fee means $3 is charged on every $100 transacted; fees can vary by processor, card type, and pricing model.

Is a 3% transaction fee a lot?

A 3% transaction fee is at the higher end of industry averages, potentially impacting profit margins for small businesses.

Best Practices for Managing Merchant Processing Fees

  1. Audit statements monthly for hidden or new processing fees
  2. Bookkeeper auditing merchant processing fee statements with a calculator and paperwork
  3. Educate your staff on card processing procedures
  4. Consider negotiating or switching payment processors
  5. Use technology to automate and reconcile payment processing
Merchant Processing Fees in the Digital Era: Emerging Trends

Contactless Payments and New Card Processing Fee Structures

The rise of contactless payments (using smartphones, smartwatches, or contactless cards) offers convenience and speed, but fee structures are evolving. Many processors price contactless transactions similarly to chip card transactions, though some may apply higher “card not present” rates if the underlying technology isn’t secure. New fees for digital wallets, buy-now-pay-later, or cryptocurrency are also emerging, so compare new offerings carefully.
Customer using smartphone for contactless payment in a modern coffee shop, reflecting new processing fee structures

The Impact of PCI Compliance and Security on Processing Fees

Maintaining PCI compliance, the industry standard for card payment security, is essential for avoiding fines and keeping processing fees low. Non-compliance can result in higher monthly fees or even account termination. Many processors offer integrated solutions to help small businesses stay compliant as data security threats evolve.

A robust security approach not only saves you money on fees but also builds customer trust in your business’s commitment to protecting their sensitive payment information.

FAQs: Merchant Processing Fees for New Small Businesses

Do all businesses have to pay merchant processing fees?

Yes, any business that accepts credit or debit card payments must pay some form of merchant processing fee. These fees cover the cost of moving funds from the customer’s bank to your account and are a standard part of card payment processing.

Can I pass merchant processing fees to customers?

You may be able to, depending on your state law and card network rules. Many states allow surcharging if you follow disclosure requirements and caps. Always check compliance details or consult your payment processor before implementing this strategy.

Are there ways to process credit cards without any fee?

No, every transaction incurs some fee, even if bundled into product prices or paid through a third party. However, businesses can minimize costs by encouraging lower-fee methods, shopping for competitive pricing, and negotiating with processors.

Key Takeaways: What New Small Businesses Must Remember About Merchant Processing Fees

  • Merchant processing fees directly affect profits—understand every charge
  • Pricing model selection can provide substantial savings
  • Always review compliance and legal guidelines for surcharges
  • Proactive management can help minimize unexpected processing fees

Conclusion: Navigating Merchant Processing Fees for Small Business Success

"Understanding and optimizing your merchant processing fees is essential for maintaining a healthy bottom line as a new entrepreneur."

Mastering merchant processing fees is just one piece of the puzzle when it comes to building a resilient and profitable small business. If you’re ready to take your business foundation to the next level, explore our comprehensive guidance for building a strong small business. This resource covers essential legal, operational, and strategic steps that can help you avoid common pitfalls and set your venture up for long-term success. By deepening your understanding of both financial and legal best practices, you’ll be better equipped to navigate challenges and seize new opportunities as your business grows.
Ready to Reduce Your Merchant Processing Fees?

Call for a free consultation at 214-854-9931

Recommended Video Resources on Merchant Processing Fees

Merchant Processing Fees 101: Explaining All the Essentials

How to Compare Card Processing Fee Offers for Small Businesses

Merchant Processing & Payments

Write A Comment

*
*
Please complete the captcha to submit your comment.
Related Posts All Posts
09.16.2026

Payment Processing for Subscription-Based Startups

As you consider the essential components of subscription payment processing, it's also valuable to explore how recurring billing automation can further streamline your operations and reduce manual errors. For a practical breakdown of recurring billing best practices and actionable setup tips, check out this guide on optimizing recurring billing for startups. If you’re ready to take your startup’s payment infrastructure to the next level, it’s worth broadening your perspective beyond just payment processing. Building a resilient subscription business also means understanding the legal, operational, and strategic foundations that support long-term growth. For a comprehensive look at how to strengthen your small business from the ground up—including legal considerations and sustainable business practices—explore this in-depth resource on building a strong small business. By combining robust payment systems with holistic business strategies, you’ll be well-positioned to thrive in the competitive subscription economy.

09.09.2026

Best Merchant Services for Retail Startups

Did you know that 82% of retail startups fail without reliable payment processing? It’s true: having the right retail merchant services isn’t just nice to have—it’s mission critical for every budding retail business. This guide cuts through the noise to reveal how the right merchant service companies can unlock your startup’s growth, prevent payment pitfalls, and transform your retail store into a customer favorite. Revealing the Real Impact of Retail Merchant Services on Startup Growth As a retail startup, your path to profitability hinges on seamless payment processing solutions and the ability to quickly accept card payments, whether from credit cards, debit cards, or digital wallets. Without a trusted merchant service provider, cash flow can stall, customer trust can erode, and you risk falling behind competitors who streamline every transaction. Retail merchant services provide the lifeblood for your business, handling everything from card machine setup to chargeback protection, and direct connections to financial networks for instant day settlement. The right services company doesn’t just move money—they move your business forward. Success in the retail world means more than stocking shelves and managing staff. With over 60% of transactions now cashless in modern retail businesses, your ability to accept card payments is directly tied to sales growth, better customer experiences, and repeat purchases. Reliable payment processing opens doors for omnichannel sales, from in-store POS systems to online and mobile checkouts. In this article, we'll unpack why payment service providers are essential for startups, how to compare merchant services, and which solutions offer the competitive edge needed in a crowded retail marketplace. When evaluating merchant service providers, it's also helpful to understand how payment processing fits into the broader foundation of your business. For a deeper dive into building a resilient small business from the ground up, including legal and operational essentials, explore this comprehensive guide to small business fundamentals. A Startling Fact: 82% of Retail Startups Fail Without Reliable Payment Processing That’s right: data shows failure to secure dependable, secure merchant service relationships and easy card payment procedures puts startups at a major disadvantage. After all, friction at the checkout often leads to lost sales—and no small business can afford that. What You'll Learn About Retail Merchant Services for Small Businesses Key features of the best retail merchant services How merchant services impact retail startup success Industry-leading merchant service companies and processing solutions Retail merchant service costs and payment processing considerations Understanding Retail Merchant Services and Payment Processing Solutions What Are Retail Merchant Services? Retail merchant services refer to the comprehensive suite of payment processing tools and services that empower small businesses to accept and manage payments made with credit cards, debit cards, and other modern card payment methods. These services span everything from opening a merchant account (which functions as a temporary holding bank account) to supporting POS systems, online checkout integration, fraud management, and automated reporting. Unlike ordinary bank accounts, merchant services are tailored for fast-moving retail selling—giving you the agility to handle in-person, mobile, or online transactions with equal confidence. For startups in particular, choosing the right retail merchant service provider can make the crucial difference between seamless sales and disruptive headaches. Reliable merchant service companies streamline the way your retail business processes payments, minimize cash flow delays, and safeguard against card fraud or chargebacks. They act as trusted partners, not just vendors, giving you access to state-of-the-art card machines, virtual terminal options, and transparent processing costs tailored to your unique growth stage. How Merchant Service Companies Work for Small Business Retailers A merchant services company acts as the engine behind every successful card transaction. They enable your retail merchant setup to accept card payments by connecting your POS system or card reader to global financial networks. When a customer pays with a credit card or debit card, your merchant account receives the payment, verifies the transaction, and deposits the funds safely—typically with next-day or even same-day settlement for robust cash flow. The best services provide dashboard access for tracking sales, real-time alerts, and easy access to technical or customer support. Small business retailers benefit from merchant service companies that offer flexible contract terms (monthly or pay-as-you-go), transparent fee structures, and advanced fraud detection. Look for providers that integrate with a wide range of hardware—from advanced POS terminals to smartphone-compatible dongles—and who facilitate both physical and e-commerce transactions. This not only caters to changing customer behaviors but also ensures your retail business won’t be left behind by new payment technologies. Role of Credit Card and Card Machines in Merchant Services Card machines and POS terminals are the critical hardware components that bring merchant services to life in any retail store. These devices authenticate, process, and encrypt card payments—allowing fast, secure, and reliable checkouts whether via chip, swipe, tap, or digital wallets. Modern merchant services companies often provide or lease these machines as part of their overall service suite, ensuring compatibility with multiple card types and payment apps. Having the latest card machine or virtual terminal boosts your brand’s professionalism and customer trust. Speedy card processing means shorter lines and fewer abandoned baskets—a must for busy retail environments. On top of this, advanced POS systems can sync with inventory management, track customer preferences, and produce detailed sales reports—helping startups turn payment data into actionable business insights. Top Features of the Best Retail Merchant Services Integrated payment processing solutions Seamless credit card and debit card acceptance POS card machines and terminals Competitive pricing structures for small business Robust fraud and chargeback management The best retail merchant services go beyond simple payment acceptance. Integrated processing solutions ensure your operation can handle all forms of card payments—chip, magstripe, contactless, and even new methods like QR codes or mobile wallets. Seamless integration into your POS system reduces training time and the risk of manual entry errors. Competitive pricing—typically ranging from 1. 5% to 3. 5% on card transactions—is vital for protecting margins, while robust chargeback management provisions shield your business from common pitfalls that disrupt cash flow. When choosing a service provider, ensure they offer fraud detection tools, next-day settlements, online reporting, and on-demand customer service. Whether you’re processing a few card transactions per day or managing multi-location sales, these features will help your startup operate efficiently and confidently in a fast-moving retail landscape. Comparison Table: Leading Retail Merchant Service Companies Merchant Service Company Key Features Costs & Fees Contract Terms Processing Speed Best For Square Free POS, card reader, online invoicing, real-time reporting 2.6% + 10¢ per transaction No long-term contract Next day Retail popups & startups Clover Customizable POS, inventory tools, contactless payments 2.3% + 10¢ per transaction Monthly contracts Same or next day Growing small businesses Helcim Transparent pricing, virtual terminal, advanced security Interchange + 0.3% + 8¢ No contract 1-2 days Cost-conscious startups Stripe API integration, online/offline payments, fraud detection 2.9% + 30¢ per online transaction Month-to-month 2 days Omnichannel retailers PayPal Zettle Simple POS, card reader, eCommerce sync 2.29% per transaction No contract Next day Side businesses & mobile sellers Best Retail Merchant Services for Startups: Detailed Reviews Review: [Top Merchant Service Company #1] Square is a pioneer in retail payment processing solutions, renowned for intuitive design, transparent pricing, and no-hassle contracts. Their free POS system, coupled with an affordable card reader, allows startups to accept credit and debit card payments anywhere—whether in-store, curbside, or at pop-up events. Square stands out for its crystal-clear 2. 6% + 10¢ per transaction fee—no hidden costs or monthly minimums. With seamless integration into modern retail environments, Square helps small businesses thrive by ensuring reliable cash flow, same-day settlements, and 24/7 support. Comprehensive sales and customer insights are only a tap away in the Square Dashboard, giving startup retailers a powerful advantage in a competitive market. Alongside brick-and-mortar capability, Square supports online checkouts and digital wallet payments, allowing retailers to meet customers where they shop. With built-in chargeback protection and fraud detection, it keeps your business secure as you scale. For startups needing adaptability, speed, and transparent service, Square is among the best in the industry. Review: [Top Merchant Service Company #2] Clover is a favorite among retail merchants looking for a customizable and scalable POS ecosystem. Its modular system—featuring everything from sleek card machines and contactless card readers to inventory management tools—caters to both new startups and growing businesses. Clover’s transaction fees are competitive (2. 3% + 10¢), and the platform offers monthly contract flexibility, important for startups wary of long-term commitments. What sets Clover apart is its vast app marketplace, empowering retailers to expand as their needs evolve—from customer loyalty programs to online store integration. With robust support for debit and credit card acceptance, quick day settlement, and superior chargeback resolution, Clover is ideal for startups seeking growth potential. Their hardware options cover everything from stationary POS terminals to mobile card readers for smartphone or tablet use—all backed by industry-standard security and PCI compliance. Review: [Top Merchant Service Company #3] Helcim is best known for its radically transparent, low-cost pricing—making it a top pick for cost-conscious retail startups. Helcim uses an interchange-plus structure, with rates as low as interchange + 0. 3% + 8¢ per transaction, passing savings directly to retailers as they grow. Their POS system is user-friendly and versatile, supporting both brick-and-mortar and online sales, plus a powerful virtual terminal for phone or mail orders. Helcim includes free PCI compliance and advanced security tools to protect against fraud and chargebacks, reducing risk for small businesses. Fast processing (1-2 day settlement), real-time reporting, and no long-term contracts help startups stay agile while maintaining healthy cash flow. Helcim’s strong focus on customer support and resource guides is an additional plus for first-time business owners navigating retail payment systems for the very first time. How to Choose the Right Retail Merchant Services for Your Startup Assessing processing solutions and hardware needs Comparing credit card transaction fees Evaluating customer support and merchant account services Considering setup costs and contract flexibility Choosing the optimal merchant services company starts with a frank assessment of your retail operation’s scale, expected transaction volume, and technical requirements. New startups may want low-cost, plug-and-play solutions like Square or PayPal Zettle, while ambitious businesses gearing up for rapid growth might benefit from an all-in-one system like Clover or customizable solutions like Helcim. Carefully compare credit card and debit card fees—not just per-transaction charges, but also hidden costs like PCI compliance, service provider support, chargeback fees, and hardware rentals. Pay special attention to setup timelines, ease of onboarding, contract flexibility, and whether the provider offers responsive customer support via multiple channels. Look for transparent terms, quick day settlement for consistent cash flow, and integration with online platforms for omnichannel sales. Startups should choose a merchant account that scales with the business and won’t lock them into restrictive or costly arrangements. Video Guide: Setting Up Retail Merchant Services for Small Businesses Expert Quote: On the Value of Merchant Services for Retail Small Business "Choosing the right retail merchant service can mean the difference between thriving and surviving for startups. Reliable payment processing is your lifeline to steady revenue." — Industry Payment Professional People Also Ask: Frequently Searched Questions About Retail Merchant Services Who owns retail merchant services? Answer: Retail merchant services can be owned by independent companies, financial institutions, or specialized payment processors offering merchant accounts and processing solutions to retailers. What does a retail merchant do? Answer: A retail merchant manages the sale of goods and services to customers, handling payments, inventory, and customer service—crucially relying on merchant services for secure credit card and digital payment processing. How much does retail merchant services charge? Answer: Costs vary by merchant service company but typically include transaction fees, monthly service charges, and equipment costs. Fees for retail merchant services generally range from 1. 5% to 3. 5% per credit card transaction. What's the cheapest way to accept credit cards? Answer: The least expensive option is often a flat-rate processing solution with no long-term contract or monthly minimums. Many retail merchant service providers now offer transparent pricing for small business startups. Video Tutorial: Comparing Card Machines and Payment Processing Solutions Pros and Cons List: Retail Merchant Services for Startups Pros: Fast payments, increased sales, improved customer trust, flexible payment processing. Cons: Monthly and transaction fees, contract terms, potential chargebacks. FAQs: Quick Answers to Retail Merchant Services Queries What is the difference between retail merchant services and traditional bank accounts? Retail merchant services provide specialized payment processing, chargeback protection, and point-of-sale integrations—unlike standard bank accounts, which do not process customer card transactions or offer POS solutions. Are retail merchant services necessary for online retail businesses? Yes—any business selling online needs a merchant account or payment services company to securely process credit card and digital wallet payments. Can startups negotiate payment processing fees with merchant service companies? In many cases, yes—startups with higher volume or growth potential can often negotiate lower rates or transaction fees with providers. What is PCI compliance and why does it matter for small business retailers? PCI compliance ensures your payment system securely handles cardholder data, protecting against fraud and data breaches—a prerequisite for any retail merchant service provider. Key Takeaways: Finding the Best Retail Merchant Services for Your Business Choosing optimal retail merchant services requires comparing features, pricing, and support. Reliable payment processing is essential for retail startup growth and customer trust. Startups benefit from transparent, scalable, and secure merchant service solutions. Ready to Grow Your Startup? Call for a Free Consultation at 214-854-9931 With the right retail merchant services partner, your startup can thrive—unlocking faster sales, happier customers, and steady growth in a dynamic retail landscape. As you continue to refine your retail startup’s payment infrastructure, remember that merchant services are just one pillar of a resilient business. For a holistic approach to building a strong foundation—covering legal, operational, and strategic considerations—take the next step by reviewing expert guidance for small business success. This resource offers actionable insights that go beyond payments, helping you future-proof your venture and navigate the challenges of growth with confidence. Investing in both robust merchant services and sound business practices will position your startup for long-term achievement in today’s competitive retail landscape.

09.02.2026

How Chargebacks Hurt Startup Merchant Accounts

Did you know over 80% of startups are hit with chargebacks in their first year—risking not only their revenue but their very survival? While many founders focus on growth and customer acquisition, few realize just how devastating chargebacks can be to young businesses. In this article, you’ll learn how startup chargeback prevention can save your company from costly pitfalls, secure your merchant account, and ultimately protect your business as you scale. A Startling Look at Startup Chargeback Prevention and Its Impact on Startup Merchant Accounts Unveiling a surprising statistic: Over 80% of startups experience chargebacks within their first year. Why startup chargeback prevention is more than just a finance issue—it's a survival strategy. “Chargebacks aren’t just the cost of doing business—they can be the difference between scaling or shuttering your startup.” What You'll Learn About Startup Chargeback Prevention How chargebacks can undermine your startup's financial stability. Comprehensive startup chargeback prevention techniques. Key steps to protect your merchant account from chargeback fraud. Role of payment processors and customer service in friendly fraud. Understanding Chargeback Prevention for Startup Merchant Accounts What Are Chargebacks and Why Do Startups Need Prevention? Chargebacks occur when a cardholder disputes a credit card charge directly with their issuing bank, prompting a reversal of funds from your merchant account. For startup merchants, frequent chargebacks aren’t just minor hiccups—they can lead to costly penalties, loss of payment processing privileges, or even a frozen bank account. This is why startup chargeback prevention is critical from day one. Startups often operate on slim margins, and a few unexpected reversals are enough to throw off cash flow, frustrate business owners, and threaten your bottom line. By prioritizing chargeback prevention, startups can proactively shield themselves against these setbacks, ensure smooth payment processing, and protect your revenue as you grow. For startups looking to further strengthen their defenses, understanding the legal and operational foundations of small business management is equally important. Exploring guidance for building a strong small business can provide additional strategies that complement your chargeback prevention efforts and support long-term stability. How Credit Card Chargeback Works in Startup Contexts A chargeback typically starts when a customer disputes a card charge with their card issuer, often citing fraud, dissatisfaction, or a failure in customer service. The card issuer then temporarily removes the funds from your account and starts the dispute process, collecting evidence from both the cardholder and merchant. For startups, responding quickly and providing compelling documentation is essential to prevent losing both the funds and customer trust. The process exposes founders to complex interactions with card companies and strict timelines set by the issuing bank. Failing to follow through can result in penalties, an increased chargeback ratio, and potential termination of your payment processing capabilities—underscoring the need for proactive chargeback management and robust prevention strategies. The Growing Importance of Chargeback Prevention Strategies for Startups Startups today face a landscape where fraudsters are more sophisticated and card charge disputes are on the rise. As card not present (CNP) transactions increase, so does exposure to friendly fraud and chargeback fraud. Prevention strategies go beyond simple transaction monitoring. They involve advanced fraud detection, swift customer service, and leveraging partnerships with the right payment processor. The earlier you establish chargeback prevention protocols, the better protected your startup will be from the start. Building these strategies helps prevent chargebacks, protect your business reputation, and positions your company to scale confidently—even in a challenging fintech environment. Chargeback Type Description Impacts Prevention Methods Card Charge Legitimate transaction later disputed by customer Loss of funds, higher chargeback ratio, potential account termination Clear billing, timely delivery, signature confirmation Fraudulent Chargeback Unauthorized or counterfeit credit card use Revenue loss, fines, increased costs of fraud prevention Fraud detection tools, AVS, CVV checks, EMV Friendly Fraud Customer falsely claims fraud/dispute to recover funds Loss of goods/services and funds, customer trust erosion Strong communication, order tracking, providing clear receipts How Chargebacks Disrupt Startup Businesses—and Why Startup Chargeback Prevention Matters Startup Chargeback Prevention and Its Direct Effects on Revenue and Growth Chargebacks directly chip away at your startup’s revenue and can stall growth in unexpected ways. Every disputed transaction not only results in lost income but also compounds into fees levied by card companies and payment processors. If your chargeback ratio rises above what the processor allows, you risk having your merchant account frozen or terminated. For startups, these penalties can rapidly escalate, making it essential to prevent chargebacks from the outset. Additionally, the financial stability of your business is threatened, as cash flow crunches limit your ability to invest in operations or marketing. Proactive chargeback prevention strategies are essential to safeguard your bottom line and allow uninterrupted growth, especially in the competitive early stages of business. Protecting Your Business from Card Chargeback Risks The risk of card chargebacks increases as your business grows. Effective startup chargeback prevention means identifying potential vulnerabilities in your payment systems and customer service, addressing them before they become liabilities. Integrating fraud detection software, authenticating credit card transactions, and educating your team on common causes of disputes can substantially reduce chargebacks. Remember, the goal is not just to recover lost funds, but to create an environment where disputes are minimized and your reputation remains intact. When founders make prevention a core business objective, they reduce the chances of merchant account loss, preserve cash flow, and protect your business for the long run. Case Study: How a Startup Lost Access to Its Payment Processor After Chargeback Fraud Consider the story of a SaaS founder whose business was thriving—until a wave of friendly fraud chargebacks hit their merchant account. Despite strong sales, the startup failed to respond promptly to disputes and lacked a systematic chargeback prevention plan. Their payment processor flagged the high chargeback ratio and, with little warning, shut off their merchant account. The founder struggled to secure a new processor, customers experienced service interruptions, and revenue came screeching to a halt. This highlights the real-world stakes of startup chargeback prevention: inaction leads to lost payment processing capabilities and, for many startups, a swift downward spiral. “Losing your merchant account is often just the first domino in a cascade of failures for startups.” Identifying the Main Causes of Chargebacks for Startups Common credit card chargeback scenarios in early-stage businesses. Role of customer service failures in creating avoidable disputes. Friendly fraud: What it is and why startups are vulnerable. Detecting and Preventing Friendly Fraud in Startups Friendly fraud, where a genuine customer falsely claims they didn’t receive the product or were charged erroneously, is especially dangerous for startups. Startups are more vulnerable because they may lack robust verification systems or proactive communication. Preventing friendly fraud requires clear receipts, detailed tracking, swift responses to customer complaints, and educating customers on your billing practices. Implementing automated fraud detection tools and working closely with your payment processor can help flag suspicious behavior. Ultimately, integrating prevention strategies into your daily operations will minimize losses from friendly fraud and maintain healthy customer relations. Payment Processor Rules and Card Charge Dispute Process Your payment processor has strict policies for responding to card chargebacks. The dispute process is time-sensitive: after a chargeback is initiated, you have a short window to provide evidence such as order confirmations, delivery proofs, and communication history. Failing to comply may result in financial penalties and jeopardize your merchant account. Understanding the rules—including chargeback thresholds and what the card issuer requires—puts startups at an advantage when navigating these disputes. Robust documentation and prompt communication with your processor are key components of effective chargeback management, ensuring you don’t lose disputes by default and that you protect your revenue as you grow. Startup Chargeback Prevention Strategies: Avoid Card Chargeback Pitfalls Top 10 startup chargeback prevention tips. Implementation of fraud prevention tools for early-stage businesses. Developing a proactive customer service approach for dispute resolution. “Investing in robust startup chargeback prevention techniques pays for itself.” Leveraging Payment Processor Solutions for Effective Startup Chargeback Prevention Payment processors are invaluable allies in preventing chargebacks. Advanced processors offer real-time alerts, fraud filters, and chargeback representment services tailored for startups. By selecting a processor equipped with the latest fraud detection tools, businesses immediately reduce their risk. Ensure your payment partner has experience with chargeback prevention, provides transparent reporting, and supports you in building airtight documentation. Such partnerships help founders stay one step ahead, enabling startups to focus on growth while safeguarding transaction stability and customer trust. Best Practices for Credit Card Charge Monitoring Monitoring every credit card charge—both for patterns of fraud and for customer satisfaction—is central to chargeback prevention. Implement daily transaction reviews, automated alerts for large or suspicious charges, and regular reconciliation of payments. Utilize your processor’s dashboards to spot anomalies early. This vigilance allows business owners to catch issues before they escalate, address disputes promptly, and maintain a healthy chargeback ratio. Incorporating these monitoring routines into your financial workflow means you’re always prepared to combat card chargeback issues. Integrating Fraud Detection for Ongoing Card Charge Protection Fraud detection solutions powered by AI and machine learning are now accessible even for startups. These tools automatically flag irregular purchase patterns, mismatched billing details, and high-risk locations before the transaction is completed. Startups benefit from integrating these technologies, as they help prevent chargebacks before they materialize, save hours of manual review, and add a crucial layer of security. By investing in ongoing fraud prevention technology, you protect your business, reduce chargebacks, and establish a reputation for secure and reliable payment processing. Startup Chargeback Fraud: Identifying and Responding to Threats Understanding Chargeback Fraud and Its Consequences for Startups Chargeback fraud occurs when a transaction is intentionally disputed under false pretenses, often by individuals exploiting loopholes in the payment system. For startups, the stakes are high: too many fraudulent chargebacks will not only cost you goods or services and transaction value, but also risk your merchant account status and brand reputation. Small businesses and startups are especially susceptible because their verification and disruption response may not match those of established enterprises. Proactive monitoring, advanced fraud detection tools, and documented evidence are essential defenses against this growing threat in the digital economy. How Startups Can Prevent Chargeback Fraud with Modern Technology Modern technology offers startups a variety of ways to prevent chargeback fraud effectively. Implementing AVS (Address Verification Service), CVV checks, two-factor authentication, and device fingerprinting minimizes unauthorized transactions. Machine learning-based fraud analytics can detect patterns and flag high-risk behavior before the sale completes. Combining these technological tools with timely customer communication significantly lowers the risk of chargeback fraud and demonstrates to both card providers and customers that you’re a vigilant merchant. Proactive defense is not just best practice; it’s essential to safeguard your business’s future. Step-by-Step Guide to Navigating the Dispute Process When a chargeback occurs, swift action is essential. First, promptly review the dispute notification from your payment processor, then gather all transaction records, delivery confirmations, and communication history with the customer. Next, prepare a clear, organized response and submit it through your payment processor’s chargeback dispute portal. Remain in communication with both the processor and your customer throughout the process. Consistent documentation and rapid response are the foundation of successful dispute resolution—giving your startup the best chance to recover funds and maintain a healthy merchant account standing. “Every successful dispute recovery is a lesson in startup resilience.” Customer Service as a Pillar of Startup Chargeback Prevention Creating Seamless Experiences to Preventing Chargebacks Exceptional customer service is one of the most effective ways to prevent chargebacks. By creating seamless and transparent customer journeys—from easy checkout processes to proactive support—founders drastically reduce the chances of a dispute ever arising. Resolve issues before they escalate and ensure customers have multiple channels to reach your team. Every positive experience is an insurance policy against chargebacks, friendly fraud, and reputational damage. Make customer satisfaction an integral part of your chargeback prevention strategies. How Fast, Transparent Communication Protects Your Revenue Clear, timely, and honest communication is central to protect your revenue. When an issue is detected, quick outreach can turn a potential dispute into an amicable resolution. Explain company policies, refund procedures, and dispute timelines transparently. By keeping customers in the loop, you demonstrate reliability, reduce frustration, and limit the tendency to file a chargeback. Staff should be empowered to solve problems efficiently—building loyalty and minimizing costly card chargeback events. Training Staff for Chargeback Prevention Excellence Your team is your first line of defense against chargebacks. Invest in regular training that covers identifying early signs of disputes, communicating chargeback policies with clarity, and using your payment processor’s chargeback management tools. Employees should understand how to interpret fraud alerts and manage the dispute process professionally. Ongoing training keeps your company’s prevention skills sharp as card company regulations and fraud tactics evolve. This culture of vigilance helps your startup avoid common pitfalls and lowers exposure to unnecessary financial risk. Startup Chargeback Prevention and the Role of Payment Processors How to Choose a Payment Processor With Strong Startup Chargeback Prevention Tools Selecting a payment processor capable of supporting your startup chargeback prevention goals is vital. Compare processors based on features like built-in fraud detection, chargeback reporting, threshold alerts, and transparent chargeback dispute support. Ask about experience working with startups and ensure they offer dedicated support for early-stage businesses. A processor invested in your success shares best practices and provides a partnership—not just a service—helping ensure your merchant account remains in good standing as you grow. Consider costs, integrations, and the quality of their chargeback prevention tools when making your selection. What to Know About Payment Processor Chargeback Dispute Procedures Familiarity with your processor’s chargeback dispute process can save you time and money. Know the documentation you need, the timeframes for response, escalation procedures, and what your processor requires for a successful dispute. Work with their support team to ensure your policies and evidence meet standards set by card issuers. This proactive approach allows founders to protect your business and learn from each dispute—constantly refining prevention measures for the future. Ask questions upfront and establish clear communication channels with your processor from the very beginning. Essential Fraud Detection and Prevention Tools for Startups Automated fraud detection for preventing card chargebacks. Benefits of AI-driven chargeback prevention solutions. Third-party tools for real-time monitoring and reporting. Documenting and Reporting for Startup Chargeback Prevention Keeping Accurate Records for Evidence in the Dispute Process Winning chargeback disputes depends on your ability to produce timely, accurate evidence. Maintain digital records of every transaction, communication, shipping confirmation, and refund. Use secure cloud storage or CRM systems that timestamp actions. This detailed documentation acts as your insurance policy in the event of a chargeback—providing compelling proof to card companies and payment processors. Dedicated record keeping is an investment in both financial safety and operational resilience, helping you reduce chargebacks and protect your merchant account for the long term. Best Practices for Documenting Customer Communication Every interaction with customers can serve as evidence in the dispute process. Ensure all communication (emails, chat transcripts, call logs) is stored systematically and linked with corresponding transactions. Set up standard templates for confirming orders, shipping updates, and issue resolution summaries. This not only streamlines chargeback management, but also strengthens customer trust. Well-documented communication satisfies card issuers’ evidence requirements and places your startup in the strongest possible position to recover revenue when challenged. Training and Education for Ongoing Startup Chargeback Prevention Internal policy creation for preventing chargebacks. Ongoing team training: Why it matters for long-term fraud prevention. Startup Chargeback Prevention Case Studies: Success Stories and Lessons Learned “Our chargebacks dropped by 70% after implementing comprehensive prevention strategies.” – A fintech founder Many emerging fintech businesses and SaaS startups have turned their fortunes around by adopting comprehensive startup chargeback prevention programs. These companies focused on deploying automated fraud detection, strengthening customer service, and closely monitoring card chargebacks. Within months, they saw massive reductions in disputed transactions, better payment processor relationships, and significant improvements to their bottom line. The lesson: preventative action, not reaction, makes all the difference in scaling a resilient company. Comparing Chargeback Prevention Solutions for Startups Tool Key Features Cost (Monthly) Effectiveness FraudShield Pro AI analytics, instant alerts, integrates with all major processors $49–$99 High for early-stage SaaS and ecommerce startups Chargeback Defender Automated representment, real-time resolution, chargeback reports $79–$129 Excellent for dispute-heavy businesses SecurePay Plus Manual review assist, chargeback dispute support, notification system $59–$99 Best for high-ticket-item startups Key Takeaways: Why Startup Chargeback Prevention Should Be Every Founder’s Priority Startup chargeback prevention is central to protecting your business and revenue. Effective strategies reduce the risk of merchant account loss. Ongoing education, customer service, and technology adoption are essential. Startup Chargeback Prevention FAQs What are the first steps to implement startup chargeback prevention? Start by selecting a payment processor with robust prevention features, train your staff, establish clear customer communication protocols, and implement real-time fraud detection tools. How can fintech startups prevent friendly fraud and chargeback fraud? Use transparent billing, keep comprehensive transaction records, respond quickly to customer inquiries, and consider AI-powered fraud detection to spot suspicious activity before it escalates. When do payment processors terminate merchant accounts for excessive card chargebacks? Most payment processors set a strict threshold; if your chargeback ratio exceeds 1% of your monthly transactions, you risk termination. Immediate action is critical if you approach this limit. Are automated fraud detection tools essential for startup chargeback prevention? Yes, especially as your transaction volume increases. Automation helps flag high-risk charges instantly, preventing fraudulent transactions from going through and reducing costly disputes. People Also Ask: Startup Chargeback Prevention How can startups reduce the risk of credit card chargebacks? Startups can reduce the risk of credit card chargebacks by using proactive communication, implementing clear billing descriptors, monitoring for suspicious transactions, providing accurate delivery timelines, and training teams to resolve issues quickly, all as part of a comprehensive startup chargeback prevention plan. What is the best chargeback prevention strategy for a new merchant account? The best strategy combines fraud detection tools, transparent customer service processes, clear refund policies, and ongoing documentation of every transaction. Leveraging your payment processor’s resources further reduces exposure to card chargebacks and ensures early-stage protection. How does startup chargeback prevention differ from traditional chargeback prevention? Startup chargeback prevention places more emphasis on rapid response and flexibility, using technology and internal training to overcome limited resources. Startups also require solutions tailored to high risk, low volume, and the unique challenges of scaling rapidly. Can a startup recover from excessive chargebacks? Yes, but recovery requires immediate action: lowering the chargeback rate, switching processors if necessary, improving fraud prevention systems, and retraining staff. Quick recovery strategies—backed by smarter documentation—restore merchant privileges and rebuild trust with partners. What role does customer service play in preventing chargebacks for startups? Exceptional customer service minimizes dispute escalation, resolves complaints promptly, and fosters transparency—all of which are proven to prevent chargebacks before they happen. It’s a fundamental pillar of effective startup chargeback prevention. Are all payment processors equal when it comes to startup chargeback prevention? No. Some processors offer specialized tools, dedicated support, and startup-focused solutions, while others have minimal prevention options. Research and choose a processor aligned with your business’s chargeback prevention needs to ensure the best protection. Ready to Secure Your Startup? Call for a Free Consultation at 214-854-9931 Conclusion: Startup chargeback prevention is not optional—it’s your safeguard to protecting revenue, ensuring scalable growth, and building a business that stands the test of time. Take action now to strengthen your defenses and allow your vision to thrive. As you continue to refine your chargeback prevention strategies, remember that building a resilient business goes beyond just managing disputes. By investing in the right legal, operational, and financial frameworks, you set the stage for sustainable growth and long-term success. For a deeper dive into foundational business practices that can further protect and empower your startup, consider reviewing comprehensive guidance for building a strong small business. This resource offers actionable insights that complement your chargeback prevention efforts and help you navigate the broader challenges of entrepreneurship with confidence.

About Us:

At Renwick Evans and Associates, we deliver tailored consulting strategies that support your business's unique journey toward growth and success.

We provide strategic guidance for small business owners seeking clarity, stability, and growth. Our services support businesses at every stage—from startup to expansion—through smart strategy and practical solutions.

Connect with Us:

Phone: 214-854-9931

Click to Call Now

{"name":"Call Footer","action_type":"3","optin_action_type":"5","form_redirect_type":"3","form_redirect_funnel_url":"uaahut61mb","form_redirect_custom_url":"","order_form_settings":{"containers":[{"id":"personal-info-wrapper","visible":true,"label":{"id":"of-personal-title","visible":true},"fields":[{"id":"of-full-name","setting":false,"placeholder":"Full Name"},{"id":"of-field-email","setting":false,"placeholder":"Email Address"},{"id":"of-phone-number","setting":true,"visible":false,"require":true,"placeholder":"Enter Your Mobile Phone","additional":{"sms_permission":0}},{"id":"of-gdpr-optin-approval","label":"I Accept To Receive Additional Info","placeholder":"","icon":"fa-mobile","required":0,"visible":0,"system":1,"additional":{"gdpr_optin_approval":"1"}}]},{"id":"shipping-information-wrapper","visible":false,"label":{"id":"of-shipping-title","visible":true},"fields":[{"id":"of-shipping-address","setting":false,"placeholder":"Address"},{"id":"of-shipping-city","setting":false,"placeholder":"City"},{"id":"of-shipping-state","setting":false,"placeholder":"State"},{"id":"of-shipping-zipcode","setting":false,"placeholder":"Postal Code"}]},{"id":"profit-bump-wrapper","visible":true,"otoBgColor":"rgba(219,229,239,1)","otoBorderColor":"rgba(38,71,102,1)","otoTitleBgColor":"rgba(45,78,108,1)","otoArrowsColor":"rgba(255,177,58,1)","fields":[]},{"id":"order-summary-wrapper","visible":true,"orderDynamicBgColor":"rgba(242,242,242,1)","orderDynamicTexColor":"rgba(51,51,51,1)","fields":[]}]},"optin_type":{"showLabels":0,"fields":[{"name":"first_name","label":"Full Name","placeholder":"Enter Your Full Name","icon":"fa-user","required":1,"visible":1,"system":1,"additional":{}},{"name":"last_name","label":"Full Name","placeholder":"Enter Your Full Name","icon":"fa-user","required":1,"visible":1,"system":1,"additional":{}},{"name":"email","label":"Email","placeholder":"Enter Your Email","icon":"fa-envelope","required":1,"visible":1,"system":1,"additional":{}},{"name":"mobile_phone","label":"Mobile Phone","placeholder":"Enter Your Mobile Phone","icon":"fa-mobile","required":0,"visible":0,"system":1,"additional":{"sms_permission":0}},{"name":"fields_labels","label":"","placeholder":"","icon":"","required":0,"visible":1,"system":1,"additional":{}},{"name":"captcha","label":"Captcha","placeholder":"","icon":"","required":1,"visible":1,"system":1,"additional":{}},{"name":"gdpr_optin_approval","label":"SSBBY2NlcHQgVG8gUmVjZWl2ZSBBZGRpdGlvbmFsIEluZm8=","placeholder":"","icon":"fa-mobile","required":0,"visible":1,"system":1,"additional":{"gdpr_optin_approval":"1","sms_permission":0}}],"customFields":[],"sortedFields":[{"name":"first_name","label":"Full Name","placeholder":"Enter Your Full Name","icon":"fa-user","required":1,"visible":1,"system":1,"additional":{}},{"name":"first_name","label":"Full Name","placeholder":"Enter Your Full Name","icon":"fa-user","required":1,"visible":1,"system":1,"additional":{}},{"name":"last_name","label":"Full Name","placeholder":"Enter Your Full Name","icon":"fa-user","required":1,"visible":1,"system":1,"additional":{}},{"name":"email","label":"Email","placeholder":"Enter Your Email","icon":"fa-envelope","required":1,"visible":1,"system":1,"additional":{}},{"name":"mobile_phone","label":"Mobile Phone","placeholder":"Enter Your Mobile Phone","icon":"fa-mobile","required":0,"visible":0,"system":1,"additional":{"sms_permission":0}},{"name":"captcha","label":"Captcha","placeholder":"","icon":"","required":1,"visible":1,"system":1,"additional":{}}],"design":{"form_background_color":"rgb(245, 245, 245)","field_stroke":{"size":"1","color":"rgb(220, 220, 220)"},"field_icons":1,"button_color":"rgb(255, 158, 0)","button_stroke":{"size":"0","color":"rgba(255, 255, 255, 0.2)"},"button_box_shadow_color":"none","field_size":"small","label_size":"16","label_color":"rgb(0, 0, 0)","input_color":"rgb(52, 152, 219)","control_text_color":"rgb(0, 0, 0)","control_text_size":"15"},"mappedFields":[]},"redirect_type":{"url":"","target":0},"next_step":{"value":"uaahut61mb"},"click_to_email":{"value":""},"click_to_call":{"value":"2148549931"},"jump_to_block":{},"content":{"header_text":"PHNwYW4gc3R5bGU9ImZvbnQtc2l6ZToyNHB4OyBmb250LWZhbWlseTonb3BlbiBzYW5zJzsiPjxzcGFuIHN0eWxlPSJsaW5lLWhlaWdodDoxLjRlbTsiPldlIEFyZSBFeGNpdGVkITwvc3Bhbj48L3NwYW4+","content_text":"PHNwYW4gc3R5bGU9ImZvbnQtc2l6ZTo0OHB4OyBmb250LWZhbWlseTonb3BlbiBzYW5zJzsiPjxzcGFuIHN0eWxlPSJsaW5lLWhlaWdodDowLjllbTsiPjxzdHJvbmc+UExFQVNFIEZJTEwgT1VUIFlPVVIgSU5GTyAgQkVMT1cgVE8gU1VCU0NSSUJFPC9zdHJvbmc+PC9zcGFuPjwvc3Bhbj4=","button_text":"PHNwYW4gc3R5bGU9ImZvbnQtc2l6ZToyN3B4OyBmb250LWZhbWlseTonb3BlbiBzYW5zJzsiPjxzcGFuIHN0eWxlPSJsaW5lLWhlaWdodDoxZW07Ij48c3Ryb25nPlNFQ1VSRSBNWSBTUE9UPC9zdHJvbmc+PC9zcGFuPjwvc3Bhbj4=","spam_text":"PHNwYW4gc3R5bGU9ImxpbmUtaGVpZ2h0OjEuMmVtOyI+V2UgaGF0ZSBTUEFNIGFuZCBwcm9taXNlIHRvIGtlZXAgeW91ciBlbWFpbCBhZGRyZXNzIHNhZmU8L3NwYW4+","sms_text":"UmVjZWl2ZSBTTVMgVGV4dCBVcGRhdGVzIC0gPHNwYW4+b3B0aW9uYWw8L3NwYW4+","sms_text2":"SSBBY2NlcHQgVG8gUmVjZWl2ZSBBZGRpdGlvbmFsIEluZm8="},"email_confirmation":{"enable":1,"subject":"V2UgQXJlIEV4Y2l0ZWQhIFlvdXIgSW4h","message":""},"integrations":[],"automation_enable":0,"thank_you":{"type":"popup","redirect_url":"","popup_options":{"background_color":"#ffffff","headline_visible":1,"icon_visible":1,"icon_url":"//my.funnelpages.com/assets-pb/images/thankyou-popup-icon.png","subheadline_visible":1,"button_visible":1,"button_color":"#ffa800","headline_text":"PHNwYW4gc3R5bGU9ImxpbmUtaGVpZ2h0OjEuNGVtOyI+VGhhbmsgWW91IEZvciBDb250YWN0aW5nIFVzPC9zcGFuPg==","subeadline_text":"PHNwYW4gc3R5bGU9ImxpbmUtaGVpZ2h0OjEuNGVtOyI+UGxlYXNlIENoZWNrIFlvdXIgRW1haWw8YnIgLz5XZSBXaWxsIEJlIEZvbGxvd2luZyBVcCBTaG9ydGx5PC9zcGFuPg==","button_text":"Q2xvc2U="}}}

Our Approach:

We believe strategy comes before solutions. By focusing on clarity, transparency, and measurable outcomes, we help business owners make informed decisions that move their businesses forward.

Our mission is to help small businesses rise to new heights through clear strategy, smarter systems, and confident decision-making.

© 2026 Renwick Evans & Associates All Rights Reserved. 5318 S. Hampton Rd. , Dallas, TX 75232. Contact Us. Terms of Service . Privacy Policy

This website contains content that has been created using AI. Results created with AI can be inaccurate, unreliable, and subject to hallucinations. Renwick Evans & Associates disclaims any and all liability arising from use of its AI tool or services. Results created with AI are generally not protectable under intellectual property law, so Users assume all risk associated with potential liability and non-protectability arising from its use. For further details, see the Terms, available above.
eyJjb21wYW55IjoiUmVud2ljayBFdmFucyAmIEFzc29jaWF0ZXMiLCJhZGRyZXNzIjoiNTMxOCBTLiBIYW1wdG9uIFJkLiAgIiwiY2l0eSI6IkRhbGxhcyIsInN0YXRlIjoiVFgiLCJ6aXAiOiI3NTIzMiIsImVtYWlsIjoicmVud2lja0ByZW53aWNrZXZhbnMuY29tIiwidG9zIjoiUEhBK1BITjBjbTl1Wno0OFpXMCtWMmhsYmlCNWIzVWdjMmxuYmkxcGJpQjNhWFJvSUhWekxDQjViM1VnWVhKbElHZHBkbWx1WnladVluTndPeUI1YjNWeUlIQmxjbTFwYzNOcGIyNGdZVzVrSUdOdmJuTmxiblFnZEc4Z2MyVnVaQ0I1YjNVZ1pXMWhhV3dnWVc1a0wyOXlJRk5OVXlCMFpYaDBJRzFsYzNOaFoyVnpMaUJDZVNCamFHVmphMmx1WnlCMGFHVWdWR1Z5YlhNZ1lXNWtJRU52Ym1ScGRHbHZibk1nWW05NElHRnVaQ0JpZVNCemFXZHVhVzVuSUdsdUlIbHZkU0JoZFhSdmJXRjBhV05oYkd4NUlHTnZibVpwY20wZ2RHaGhkQ0I1YjNVZ1lXTmpaWEIwSUdGc2JDQjBaWEp0Y3lCcGJpQjBhR2x6SUdGbmNtVmxiV1Z1ZEM0OEwyVnRQand2YzNSeWIyNW5Qand2Y0Q0S0NqeHdQaVp1WW5Od096d3ZjRDRLQ2p4d1BqeHpkSEp2Ym1jK1UwVlNWa2xEUlR3dmMzUnliMjVuUGp3dmNENEtDanh3UGxkbElIQnliM1pwWkdVZ1lTQnpaWEoyYVdObElIUm9ZWFFnWTNWeWNtVnVkR3g1SUdGc2JHOTNjeUI1YjNVZ2RHOGdjbVZqWldsMlpTQnlaWEYxWlhOMGN5Qm1iM0lnWm1WbFpHSmhZMnNzSUdOdmJYQmhibmtnYVc1bWIzSnRZWFJwYjI0c0lIQnliMjF2ZEdsdmJtRnNJR2x1Wm05eWJXRjBhVzl1TENCamIyMXdZVzU1SUdGc1pYSjBjeXdnWTI5MWNHOXVjeXdnWkdselkyOTFiblJ6SUdGdVpDQnZkR2hsY2lCdWIzUnBabWxqWVhScGIyNXpJSFJ2SUhsdmRYSWdaVzFoYVd3Z1lXUmtjbVZ6Y3lCaGJtUXZiM0lnWTJWc2JIVnNZWElnY0dodmJtVWdiM0lnWkdWMmFXTmxMaUJaYjNVZ2RXNWtaWEp6ZEdGdVpDQmhibVFnWVdkeVpXVWdkR2hoZENCMGFHVWdVMlZ5ZG1salpTQnBjeUJ3Y205MmFXUmxaQ0FtY1hWdmREdEJVeTFKVXlaeGRXOTBPeUJoYm1RZ2RHaGhkQ0IzWlNCaGMzTjFiV1VnYm04Z2NtVnpjRzl1YzJsaWFXeHBkSGtnWm05eUlIUm9aU0IwYVcxbGJHbHVaWE56TENCa1pXeGxkR2x2Yml3Z2JXbHpMV1JsYkdsMlpYSjVJRzl5SUdaaGFXeDFjbVVnZEc4Z2MzUnZjbVVnWVc1NUlIVnpaWElnWTI5dGJYVnVhV05oZEdsdmJuTWdiM0lnY0dWeWMyOXVZV3hwZW1GMGFXOXVJSE5sZEhScGJtZHpMand2Y0Q0S0NqeHdQbGx2ZFNCaGNtVWdjbVZ6Y0c5dWMybGliR1VnWm05eUlHOWlkR0ZwYm1sdVp5QmhZMk5sYzNNZ2RHOGdkR2hsSUZObGNuWnBZMlVnWVc1a0lIUm9ZWFFnWVdOalpYTnpJRzFoZVNCcGJuWnZiSFpsSUhSb2FYSmtJSEJoY25SNUlHWmxaWE1nS0hOMVkyZ2dZWE1nVTAxVElIUmxlSFFnYldWemMyRm5aWE1zSUVsdWRHVnlibVYwSUhObGNuWnBZMlVnY0hKdmRtbGtaWElnYjNJZ1kyVnNiSFZzWVhJZ1lXbHlkR2x0WlNCamFHRnlaMlZ6S1M0Z1dXOTFJR0Z5WlNCeVpYTndiMjV6YVdKc1pTQm1iM0lnZEdodmMyVWdabVZsY3l3Z2FXNWpiSFZrYVc1bklIUm9iM05sSUdabFpYTWdZWE56YjJOcFlYUmxaQ0IzYVhSb0lIUm9aU0JrYVhOd2JHRjVJRzl5SUdSbGJHbDJaWEo1SUc5bUlHVmhZMmdnVTAxVElIUmxlSFFnYldWemMyRm5aU0J6Wlc1MElIUnZJSGx2ZFNCaWVTQjFjeTRnU1c0Z1lXUmthWFJwYjI0c0lIbHZkU0J0ZFhOMElIQnliM1pwWkdVZ1lXNWtJR0Z5WlNCeVpYTndiMjV6YVdKc1pTQm1iM0lnWVd4c0lHVnhkV2x3YldWdWRDQnVaV05sYzNOaGNua2dkRzhnWVdOalpYTnpJSFJvWlNCVFpYSjJhV05sSUdGdVpDQnlaV05sYVhabElIUm9aU0JUVFZNZ2RHVjRkQ0J0WlhOellXZGxjeTRnVjJVZ1pHOGdibTkwSUdOb1lYSm5aU0JoYm5rZ1ptVmxjeUJtYjNJZ1pHVnNhWFpsY25rZ2IyWWdaVzFoYVd3Z2IzSWdVMDFUTGlCVWFHbHpJR2x6SUdFZ1puSmxaU0J6WlhKMmFXTmxJSEJ5YjNacFpHVmtJR0o1SUhWekxpQkliM2RsZG1WeUxDQndiR1ZoYzJVZ1kyaGxZMnNnZDJsMGFDQjViM1Z5SUdsdWRHVnlibVYwSUhObGNuWnBZMlVnY0hKdmRtbGtaWElnWVc1a0lHTmxiR3gxYkdGeUlHTmhjbkpwWlhJZ1ptOXlJR0Z1ZVNCamFHRnlaMlZ6SUhSb1lYUWdiV0Y1SUdsdVkzVnlJR0Z6SUdFZ2NtVnpkV3gwSUdaeWIyMGdjbVZqWldsMmFXNW5JR1Z0WVdsc0lHRnVaQ0JUVFZNZ2RHVjRkQ0J0WlhOellXZGxjeUIwYUdGMElIZGxJR1JsYkdsMlpYSWdkWEJ2YmlCNWIzVnlJRzl3ZEMxcGJpQmhibVFnY21WbmFYTjBjbUYwYVc5dUlIZHBkR2dnYjNWeUlHVnRZV2xzSUdGdVpDQlRUVk1nYzJWeWRtbGpaWE11SUZsdmRTQmpZVzRnWTJGdVkyVnNJR0YwSUdGdWVTQjBhVzFsTGlCS2RYTjBJSFJsZUhRZ0puRjFiM1E3VTFSUFVDWnhkVzkwT3lCMGJ5WnVZbk53T3p4b2FXZG9iR2xuYUhRZ1kyeGhjM005SW1OdmJYQmhibmxUVFZOUWFHOXVaVlZ3WkdGMFpTSStiblZzYkR3dmFHbG5hR3hwWjJoMFBpNGdRV1owWlhJZ2VXOTFJSE5sYm1RZ2RHaGxJRk5OVXlCdFpYTnpZV2RsSUNaeGRXOTBPMU5VVDFBbWNYVnZkRHNnZEc4Z2RYTXNJSGRsSUhkcGJHd2djMlZ1WkNCNWIzVWdZVzRnVTAxVElHMWxjM05oWjJVZ2RHOGdZMjl1Wm1seWJTQjBhR0YwSUhsdmRTQm9ZWFpsSUdKbFpXNGdkVzV6ZFdKelkzSnBZbVZrTGlCQlpuUmxjaUIwYUdsekxDQjViM1VnZDJsc2JDQnVieUJzYjI1blpYSWdjbVZqWldsMlpTQlRUVk1nYldWemMyRm5aWE1nWm5KdmJTQjFjeTQ4TDNBK0NnbzhjRDQ4YzNSeWIyNW5QbGxQVlZJZ1VrVkhTVk5VVWtGVVNVOU9JRTlDVEVsSFFWUkpUMDVUUEM5emRISnZibWMrUEM5d1Bnb0tQSEErU1c0Z1kyOXVjMmxrWlhKaGRHbHZiaUJ2WmlCNWIzVnlJSFZ6WlNCdlppQjBhR1VnVTJWeWRtbGpaU3dnZVc5MUlHRm5jbVZsSUhSdk9qd3ZjRDRLQ2p4dmJENEtDVHhzYVQ1d2NtOTJhV1JsSUhSeWRXVXNJR0ZqWTNWeVlYUmxMQ0JqZFhKeVpXNTBJR0Z1WkNCamIyMXdiR1YwWlNCcGJtWnZjbTFoZEdsdmJpQmhZbTkxZENCNWIzVnljMlZzWmlCaGN5QndjbTl0Y0hSbFpDQmllU0IwYUdVZ1UyVnlkbWxqWlNZak16azdjeUJ5WldkcGMzUnlZWFJwYjI0Z1ptOXliU0FvYzNWamFDQnBibVp2Y20xaGRHbHZiaUJpWldsdVp5QjBhR1VnSm5GMWIzUTdVbVZuYVhOMGNtRjBhVzl1SUVSaGRHRW1jWFZ2ZERzcElHRnVaRHd2YkdrK0NnazhiR2srYldGcGJuUmhhVzRnWVc1a0lIQnliMjF3ZEd4NUlIVndaR0YwWlNCMGFHVWdVbVZuYVhOMGNtRjBhVzl1SUVSaGRHRWdkRzhnYTJWbGNDQnBkQ0IwY25WbExDQmhZMk4xY21GMFpTd2dZM1Z5Y21WdWRDQmhibVFnWTI5dGNHeGxkR1V1SUVsbUlIbHZkU0J3Y205MmFXUmxJR0Z1ZVNCcGJtWnZjbTFoZEdsdmJpQjBhR0YwSUdseklIVnVkSEoxWlN3Z2FXNWhZMk4xY21GMFpTd2dibTkwSUdOMWNuSmxiblFnYjNJZ2FXNWpiMjF3YkdWMFpTd2diM0lnZDJVZ2FHRjJaU0J5WldGemIyNWhZbXhsSUdkeWIzVnVaSE1nZEc4Z2MzVnpjR1ZqZENCMGFHRjBJSE4xWTJnZ2FXNW1iM0p0WVhScGIyNGdhWE1nZFc1MGNuVmxMQ0JwYm1GalkzVnlZWFJsTENCdWIzUWdZM1Z5Y21WdWRDQnZjaUJwYm1OdmJYQnNaWFJsTENCM1pTQm9ZWFpsSUhSb1pTQnlhV2RvZENCMGJ5QnpkWE53Wlc1a0lHOXlJRHh6ZEhKdmJtYytQSE53WVc0Z2MzUjViR1U5SW1OdmJHOXlPaU5HUmpBd01EQTdJajUwWlhKdGFXNWhkR1VnZVc5MWNpQmhZMk52ZFc1MEwzQnliMlpwYkdVZ1lXNWtJSEpsWm5WelpTQmhibmtnWVc1a0lHRnNiQ0JqZFhKeVpXNTBJRzl5SUdaMWRIVnlaU0IxYzJVZ2IyWWdkR2hsSUZObGNuWnBZMlVnS0c5eUlHRnVlU0J3YjNKMGFXOXVJSFJvWlhKbGIyWXBMand2YzNCaGJqNDhMM04wY205dVp6NDhMMnhwUGdvOEwyOXNQZ29LUEhBK0ptNWljM0E3UEM5d1BnbzhhR2xuYUd4cFoyaDBJR05zWVhOelBTSmpiMjF3WVc1NVRtRnRaVlZ3WkdGMFpTSStVbVZ1ZDJsamF5QkZkbUZ1Y3lBbVlXMXdPeUJCYzNOdlkybGhkR1Z6UEM5b2FXZG9iR2xuYUhRK1BHSnlJQzgrQ2p4b2FXZG9iR2xuYUhRZ1kyeGhjM005SW1OdmJYQmhibmxCWkdSeVpYTnpWWEJrWVhSbElqNDFNekU0SUZNdUlFaGhiWEIwYjI0Z1VtUXVJQ3dnUkdGc2JHRnpMQ0JVV0NBM05USXpNand2YUdsbmFHeHBaMmgwUGp4aWNpQXZQZ284YUdsbmFHeHBaMmgwSUdOc1lYTnpQU0pqYjIxd1lXNTVVR2h2Ym1WVmNHUmhkR1VpUGp3dmFHbG5hR3hwWjJoMFBqeGljaUF2UGdvOGFHbG5hR3hwWjJoMElHTnNZWE56UFNKamIyMXdZVzU1UlcxaGFXeFZjR1JoZEdVaVBuSmxibmRwWTJzb1FDbHlaVzUzYVdOclpYWmhibk11WTI5dFBDOW9hV2RvYkdsbmFIUSsiLCJwcml2YWN5IjoiUEhBK1BITjBjbTl1Wno1UVVrbFdRVU5aUEM5emRISnZibWMrUEM5d1Bnb0tQSEErUEhOMGNtOXVaejVVYUdVZ2FXNW1iM0p0WVhScGIyNGdjSEp2ZG1sa1pXUWdaSFZ5YVc1bklIUm9hWE1nY21WbmFYTjBjbUYwYVc5dUlHbHpJR3RsY0hRZ2NISnBkbUYwWlNCaGJtUWdZMjl1Wm1sa1pXNTBhV0ZzTENCaGJtUWdkMmxzYkNCdVpYWmxjaUJpWlNCa2FYTjBjbWxpZFhSbFpDd2dZMjl3YVdWa0xDQnpiMnhrTENCMGNtRmtaV1FnYjNJZ2NHOXpkR1ZrSUdsdUlHRnVlU0IzWVhrc0lITm9ZWEJsSUc5eUlHWnZjbTB1SUZSb2FYTWdhWE1nYjNWeUlHZDFZWEpoYm5SbFpTNDhMM04wY205dVp6NDhMM0ErQ2dvOGNENDhjM1J5YjI1blBrbE9SRVZOVGtsVVdUd3ZjM1J5YjI1blBqd3ZjRDRLQ2p4d1BqeGxiVDVaYjNVZ1lXZHlaV1VnZEc4Z2FXNWtaVzF1YVdaNUlHRnVaQ0JvYjJ4a0lIVnpMQzRnWVc1a0lHbDBjeUJ6ZFdKemFXUnBZWEpwWlhNc0lHRm1abWxzYVdGMFpYTXNJRzltWm1salpYSnpMQ0JoWjJWdWRITXNJR052TFdKeVlXNWtaWEp6SUc5eUlHOTBhR1Z5SUhCaGNuUnVaWEp6TENCaGJtUWdaVzF3Ykc5NVpXVnpMQ0JvWVhKdGJHVnpjeUJtY205dElHRnVlU0JqYkdGcGJTQnZjaUJrWlcxaGJtUXNJR2x1WTJ4MVpHbHVaeUJ5WldGemIyNWhZbXhsSUdGMGRHOXlibVY1Y3lZak16azdJR1psWlhNc0lHMWhaR1VnWW5rZ1lXNTVJSFJvYVhKa0lIQmhjblI1SUdSMVpTQjBieUJ2Y2lCaGNtbHphVzVuSUc5MWRDQnZaaUJEYjI1MFpXNTBJSGx2ZFNCeVpXTmxhWFpsTENCemRXSnRhWFFzSUhKbGNHeDVMQ0J3YjNOMExDQjBjbUZ1YzIxcGRDQnZjaUJ0WVd0bElHRjJZV2xzWVdKc1pTQjBhSEp2ZFdkb0lIUm9aU0JUWlhKMmFXTmxMQ0I1YjNWeUlIVnpaU0J2WmlCMGFHVWdVMlZ5ZG1salpTd2dlVzkxY2lCamIyNXVaV04wYVc5dUlIUnZJSFJvWlNCVFpYSjJhV05sTENCNWIzVnlJSFpwYjJ4aGRHbHZiaUJ2WmlCMGFHVWdWRTlUTENCdmNpQjViM1Z5SUhacGIyeGhkR2x2YmlCdlppQmhibmtnY21sbmFIUnpJRzltSUdGdWIzUm9aWEl1UEM5bGJUNDhMM0ErQ2dvOGNENDhjM1J5YjI1blBrUkpVME5NUVVsTlJWSWdUMFlnVjBGU1VrRk9WRWxGVXp3dmMzUnliMjVuUGp3dmNENEtDanh3UGp4emRISnZibWMrV1U5VklFVllVRkpGVTFOTVdTQlZUa1JGVWxOVVFVNUVJRUZPUkNCQlIxSkZSU0JVU0VGVU9qd3ZjM1J5YjI1blBqd3ZjRDRLQ2p4dmJENEtDVHhzYVQ1WlQxVlNJRlZUUlNCUFJpQlVTRVVnVTBWU1ZrbERSU0JKVXlCQlZDQlpUMVZTSUZOUFRFVWdVa2xUU3k0Z1ZFaEZJRk5GVWxaSlEwVWdTVk1nVUZKUFZrbEVSVVFnVDA0Z1FVNGdKbkYxYjNRN1FWTWdTVk1tY1hWdmREc2dRVTVFSUNaeGRXOTBPMEZUSUVGV1FVbE1RVUpNUlNaeGRXOTBPeUJDUVZOSlV5NGdMQzRnUVU1RUlGVlRMQ0JKVkNZak16azdVeUJEVlZOVVQwMUZVbE1zSUVWWVVGSkZVMU5NV1NCRVNWTkRURUZKVFZNZ1FVeE1JRmRCVWxKQlRsUkpSVk1nVDBZZ1FVNVpJRXRKVGtRc0lGZElSVlJJUlZJZ1JWaFFVa1ZUVXlCUFVpQkpUVkJNU1VWRUxDQkpUa05NVlVSSlRrY3NJRUpWVkNCT1QxUWdURWxOU1ZSRlJDQlVUeUJVU0VVZ1NVMVFURWxGUkNCWFFWSlNRVTVVU1VWVElFOUdJRTFGVWtOSVFVNVVRVUpKVEVsVVdTd2dSa2xVVGtWVFV5QkdUMUlnUVNCUVFWSlVTVU5WVEVGU0lGQlZVbEJQVTBVZ1FVNUVJRTVQVGkxSlRrWlNTVTVIUlUxRlRsUXVQQzlzYVQ0S0NUeHNhVDVOUVV0RlV5Qk9UeUJYUVZKU1FVNVVXU0JVU0VGVUlDaHBLU0JVU0VVZ1UwVlNWa2xEUlNCWFNVeE1JRTFGUlZRZ1dVOVZVaUJTUlZGVlNWSkZUVVZPVkZNc0lDaHBhU2tnVkVoRklGTkZVbFpKUTBVZ1YwbE1UQ0JDUlNCVlRrbE9WRVZTVWxWUVZFVkVMQ0JVU1UxRlRGa3NJRk5GUTFWU1JTd2dUMUlnUlZKU1QxSXRSbEpGUlN3Z0tHbHBhU2tnVkVoRklGSkZVMVZNVkZNZ1ZFaEJWQ0JOUVZrZ1FrVWdUMEpVUVVsT1JVUWdSbEpQVFNCVVNFVWdWVk5GSUU5R0lGUklSU0JUUlZKV1NVTkZJRmRKVEV3Z1FrVWdRVU5EVlZKQlZFVWdUMUlnVWtWTVNVRkNURVVzSUVGT1JDQW9hWFlwSUVGT1dTQkZVbEpQVWxNZ1NVNGdWRWhGSUZOUFJsUlhRVkpGSUZkSlRFd2dRa1VnUTA5U1VrVkRWRVZFTGp3dmJHaytDZ2s4YkdrK1FVNVpJRTFCVkVWU1NVRk1JRVJQVjA1TVQwRkVSVVFnVDFJZ1QxUklSVkpYU1ZORklFOUNWRUZKVGtWRUlGUklVazlWUjBnZ1ZFaEZJRlZUUlNCUFJpQlVTRVVnVTBWU1ZrbERSU0JKVXlCRVQwNUZJRUZVSUZsUFZWSWdUMWRPSUVSSlUwTlNSVlJKVDA0Z1FVNUVJRkpKVTBzZ1FVNUVJRlJJUVZRZ1dVOVZJRmRKVEV3Z1FrVWdVMDlNUlV4WklGSkZVMUJQVGxOSlFreEZJRVpQVWlCQlRsa2dSRUZOUVVkRklGUlBJRmxQVlZJZ1EwOU5VRlZVUlZJZ1UxbFRWRVZOSUU5U0lFeFBVMU1nVDBZZ1JFRlVRU0JVU0VGVUlGSkZVMVZNVkZNZ1JsSlBUU0JVU0VVZ1JFOVhUa3hQUVVRZ1QwWWdRVTVaSUZOVlEwZ2dUVUZVUlZKSlFVd3VQQzlzYVQ0S0NUeHNhVDVPVHlCQlJGWkpRMFVnVDFJZ1NVNUdUMUpOUVZSSlQwNHNJRmRJUlZSSVJWSWdUMUpCVENCUFVpQlhVa2xVVkVWT0xDQlBRbFJCU1U1RlJDQkNXU0JaVDFVZ1JsSlBUU0JQVWlCVVNGSlBWVWRJSUU5U0lFWlNUMDBnVkVoRklGTkZVbFpKUTBVZ1UwaEJURXdnUTFKRlFWUkZJRUZPV1NCWFFWSlNRVTVVV1NCT1QxUWdSVmhRVWtWVFUweFpJRk5VUVZSRlJDQkpUaUJVU0VVZ1ZFOVRMand2YkdrK0Nqd3ZiMncrQ2dvOGNENDhjM1J5YjI1blBreEpUVWxVUVZSSlQwNGdUMFlnVEVsQlFrbE1TVlJaUEM5emRISnZibWMrUEM5d1Bnb0tQSEErV1U5VklFVllVRkpGVTFOTVdTQlZUa1JGVWxOVVFVNUVJRUZPUkNCQlIxSkZSU0JVU0VGVUlFRk9SQ0JUU0VGTVRDQk9UMVFnUWtVZ1RFbEJRa3hGSUVaUFVpQkJUbGtnUkVsU1JVTlVMQ0JKVGtSSlVrVkRWQ3dnU1U1RFNVUkZUbFJCVEN3Z1UxQkZRMGxCVEN3Z1EwOU9VMFZSVlVWT1ZFbEJUQ0JQVWlCRldFVk5VRXhCVWxrZ1JFRk5RVWRGVXl3Z1NVNURURlZFU1U1SElFSlZWQ0JPVDFRZ1RFbE5TVlJGUkNCVVR5d2dSRUZOUVVkRlV5QkdUMUlnVEU5VFV5QlBSaUJRVWs5R1NWUlRMQ0JIVDA5RVYwbE1UQ3dnVlZORkxDQkVRVlJCSUU5U0lFOVVTRVZTSUVsT1ZFRk9SMGxDVEVVZ1RFOVRVMFZUSUNoRlZrVk9JRWxHSUVoQlV5QkNSVVZPSUVGRVZrbFRSVVFnVDBZZ1ZFaEZJRkJQVTFOSlFrbE1TVlJaSUU5R0lGTlZRMGdnUkVGTlFVZEZVeWtzSUZKRlUxVk1WRWxPUnlCR1VrOU5Pand2Y0Q0S0NqeHZiRDRLQ1R4c2FUNVVTRVVnVlZORklFOVNJRlJJUlNCSlRrRkNTVXhKVkZrZ1ZFOGdWVk5GSUZSSVJTQlRSVkpXU1VORk96d3ZiR2srQ2drOGJHaytWRWhGSUVOUFUxUWdUMFlnVUZKUFExVlNSVTFGVGxRZ1QwWWdVMVZDVTFSSlZGVlVSU0JIVDA5RVV5QkJUa1FnVTBWU1ZrbERSVk1nVWtWVFZVeFVTVTVISUVaU1QwMGdRVTVaSUVkUFQwUlRMQ0JFUVZSQkxDQkpUa1pQVWsxQlZFbFBUaUJQVWlCVFJWSldTVU5GVXlCUVZWSkRTRUZUUlVRZ1QxSWdUMEpVUVVsT1JVUWdUMUlnVFVWVFUwRkhSVk1nVWtWRFJVbFdSVVFnVDFJZ1ZGSkJUbE5CUTFSSlQwNVRJRVZPVkVWU1JVUWdTVTVVVHlCVVNGSlBWVWRJSUU5U0lFWlNUMDBnVkVoRklGTkZVbFpKUTBVN1BDOXNhVDRLQ1R4c2FUNVZUa0ZWVkVoUFVrbGFSVVFnUVVORFJWTlRJRlJQSUU5U0lFRk1WRVZTUVZSSlQwNGdUMFlnV1U5VlVpQlVVa0ZPVTAxSlUxTkpUMDVUSUU5U0lFUkJWRUU3UEM5c2FUNEtDVHhzYVQ1VFZFRlVSVTFGVGxSVElFOVNJRU5QVGtSVlExUWdUMFlnUVU1WklGUklTVkpFSUZCQlVsUlpJRTlPSUZSSVJTQlRSVkpXU1VORk95QlBVand2YkdrK0NnazhiR2srUVU1WklFOVVTRVZTSUUxQlZGUkZVaUJTUlV4QlZFbE9SeUJVVHlCVVNFVWdVMFZTVmtsRFJTNDhMMnhwUGdvOEwyOXNQZ29LUEhBK1BIVStRbmtnY21WbmFYTjBaWEpwYm1jZ1lXNWtJSE4xWW5OamNtbGlhVzVuSUhSdklHOTFjaUJsYldGcGJDQmhibVFnVTAxVElITmxjblpwWTJVc0lHSjVJRzl3ZEMxcGJpd2diMjVzYVc1bElISmxaMmx6ZEhKaGRHbHZiaUJ2Y2lCaWVTQm1hV3hzYVc1bklHOTFkQ0JoSUdOaGNtUXNJQ1p4ZFc5ME8zbHZkU0JoWjNKbFpTQjBieUIwYUdWelpTQlVSVkpOVXlCUFJpQlRSVkpXU1VORkpuRjFiM1E3SUdGdVpDQjViM1VnWVdOcmJtOTNiR1ZrWjJVZ1lXNWtJSFZ1WkdWeWMzUmhibVFnZEdobElHRmliM1psSUhSbGNtMXpJRzltSUhObGNuWnBZMlVnYjNWMGJHbHVaV1FnWVc1a0lHUmxkR0ZwYkdWa0lHWnZjaUI1YjNVZ2RHOWtZWGt1UEM5MVBqd3ZjRDRLQ2p4d1BpWnVZbk53T3p3dmNENEtVbVZ1ZDJsamF5QkZkbUZ1Y3lBbVlXMXdPeUJCYzNOdlkybGhkR1Z6UEdKeUlDOCtDalV6TVRnZ1V5NGdTR0Z0Y0hSdmJpQlNaQzRnTENCRVlXeHNZWE1zSUZSWUlEYzFNak15UEdKeUlDOCtDanhpY2lBdlBncHlaVzUzYVdOcktFQXBjbVZ1ZDJsamEyVjJZVzV6TG1OdmJRPT0ifQ==

Terms of Service

Privacy Policy

Core Modal Title

Sorry, no results found

You Might Find These Articles Interesting

T
Please Check Your Email
We Will Be Following Up Shortly
*
*
*