Renwick Evans and Associates
  • Blog Home
  • Categories
    • Startup Launch Guidance
    • Cash Flow, Funding & Capital Strategies
    • Business Operations, challenges & Solutions
    • Merchant Processing & Payments
    • Business Marketing That Works
    • Business Growth & Scaling
    • Business Consulting Insights
    • Compliance & Risk Management
  • Home
April 10.2026
1 Minute Read

How Bad Processing Setup Hurts Cash Flow

Did you know that over 60% of businesses struggle with cash flow issues directly linked to poorly optimized payment processing setups? What seems like a minor inefficiency can actually snowball, causing cascading disruption in your business’s financial stability, limiting growth, and trapping working capital

A Startling Look at Payment Processing Cash Flow Disruption
Business owner concerned about payment processing cash flow disruption, surrounded by paperwork and payment terminals, photorealistic office scene

"Recent studies show that over 60% of businesses face cash flow issues due to inefficient payment processing setups."

Payment processing cash flow is more than just moving money from a sale through your accounts—it's the lifeblood that keeps your business operational and enables growth. When the payment process is slow, opaque, or riddled with errors, your working capital suffers. These disruptions increase the risk of missed opportunities and late fees and, in severe cases, can threaten the very existence of your company. Whether you're accepting credit card payments in-store, handling virtual card payouts online, or processing bank transfers, a poorly designed payment system or outmoded payment processing system leads to expensive bottlenecks.

Imagine delayed card payment settlements resulting in unpaid invoices, or outdated payment methods causing customers to abandon transactions. Each hiccup in the payment workflow expands into wider cash flow gaps and compounding losses in both revenue and customer satisfaction. By solving these issues proactively, businesses can ensure their working capital remains healthy, paving the way for confident decision-making and seamless growth.

What You'll Learn: Key Insights About Payment Processing Cash Flow

  • Understand how payment process inefficiencies stunt working capital and cash flow.

  • Recognize the warning signs of poor payment processing systems and solutions.

  • Identify actionable steps to optimize payment solutions and methods.

Understanding Payment Processing Cash Flow: Fundamentals Every Business Needs

Defining Payment Processing and Its Link to Cash Flow
Accountant reviewing transaction data to understand payment processing cash flow fundamentals

At its core, payment processing is the series of steps a business takes to accept, verify, and transfer funds from a customer's payment to the company’s bank account. Every payment method—from card payments to digital wallets—relies on a secure, streamlined set of steps for the transaction to occur. Yet, if any part of this payment process is inefficient or outdated, it slows access to vital funds, impeding cash flow and reducing available working capital. In today's fast-paced environment, customers expect instant gratification, and any delay in resolving payment system issues can seriously damage not only the company's liquidity but its reputation as well.

For most businesses, payment processing cash flow involves managing multiple moving parts: customer purchase, authorization, transfer, and finally, settlement into company accounts. A friction-filled or error-prone payment processing system disrupts this journey, increasing processing costs and decreasing customer satisfaction. As a result, companies that don’t review and optimize their payment solutions risk falling behind—both financially and competitively.

Addressing these challenges often starts with a thorough review of your current payment workflows and identifying where inefficiencies are costing you most. For a step-by-step approach to evaluating and upgrading your payment systems, explore our guidance for building a strong small business, which covers practical strategies for strengthening your financial foundation.

How the Payment Process Directly Impacts Cash Flow

The payment process directly affects when—and how much—money your business can actually use. Delays in authorization, settlement, or even reconciliation within your accounting software create gaps in available working capital. These delays often stem from disjointed payment systems, outdated technology, or inefficient approval flows. Each hour or day lost in processing time means capital is inaccessible for payroll, new inventory, or unforeseen expenses.

Furthermore, processing solutions that lack real-time updates can mislead business owners into believing they have more liquidity than they truly do. Inaccurate cash flow forecasting leads to overcommitment and exposes businesses to the risk of bounced checks, missed payments, or rushed borrowing under unfavorable payment terms. The only way to mitigate this is by implementing modern and connected payment processing solutions that provide end-to-end visibility and speed.

Working Capital, Payment Systems, and Payment Processing Cash Flow

Working capital is the difference between a company’s current assets and current liabilities. For businesses of all sizes, the fluidity of moving funds—from payment initiation all the way to bank settlement—determines how agile that company can be in seizing new opportunities. Inefficient payment processing systems act like a bottleneck, holding onto funds that could be put to productive use.

By improving the payment system workflow, organizations see shorter cycles for card payment settlements and better forecasting accuracy. This leads to optimized staffing, timely vendor payments, and more strategic growth decisions. Conversely, fragmented or manual processing systems steadily eat away at the resources needed to sustain a healthy cash flow and resilient working capital management.

The Role of Card Payment and Payment Methods in Payment Processing Cash Flow
Modern POS terminal illustrating card payment methods and their impact on cash flow

The choice of payment methods has a significant impact on payment processing cash flow. Card payments—whether credit card, debit, or virtual card—often settle faster than checks or traditional invoices. However, they may come with higher processing costs. Meanwhile, instant mobile payment options and digital wallets can provide both speed and convenience but must be integrated securely in your payment system.

Businesses that fail to offer a variety of payment options limit how quickly they can receive funds. On the other hand, adopting too many disconnected payment methods creates reconciliation headaches, bloating administrative time and creating opportunities for costly errors. The optimal solution is a well-integrated, modern payment processing solution that matches your customer expectations while ensuring efficient cash flow.

Common Payment Processing System Pitfalls That Hurt Cash Flow

Inefficient Payment Solutions: Delays, Errors, and Hidden Costs

  • Outdated payment system limitations

  • Lack of digital payment methods

  • Disconnected accounting software

  • Poor customer experience during payments

Many businesses are stuck with outdated payment systems that simply can't keep up with modern commerce. These systems introduce avoidable delays, frequent processing errors, and sometimes, hidden fees that drain profit margins. Relying on old terminals or manual invoice processes means customers might encounter friction when they try to make payments. Each failed or delayed transaction not only results in lost sales but also creates an administrative burden, as staff scramble to fix errors and re-enter payment information into siloed databases.

The absence of digital or mobile payment methods makes the experience worse for both customers and team members, stalling settlements and stretching out the cash flow timeline. Without automation through accounting software or integration between different processing systems, reconciliation becomes a manual, error-prone task that further exposes the business to missed or duplicate payments and compliance risks.

Processing System Issues: The Ripple Effect on Cash Flow
Small business team frustrated by complex payment processing system causing cash flow issues

A poorly configured payment processing system doesn't just delay receipts—it can send shockwaves through your organization. When processing system dashboards are overly complex or lack real-time clarity, confusion grows among both staff and management. Decisions are then based on inaccurate assessments of working capital and liquidity, risking overextension or unexpected shortfalls. Each processing solution that fails to communicate seamlessly with accounting or inventory modules causes costly ripple effects.

These issues aren’t isolated to accounting—they impact every department, from sales to procurement. A locked or delayed payment process can create cash flow gaps, stall critical projects, or lead to missed discounts due to late vendor payments. Forward-thinking businesses understand that stable working capital depends on eliminating these ripple effects by investing in intuitive, modern payment processing solutions that grow with them.

Slow Payment Terms and How They Drain Working Capital

Payment terms define how long after a sale a business receives its money. Operating on extended payment terms or with clients who repeatedly delay can strangle cash flow, especially if those funds are crucial for covering operating expenses. This often occurs for service-based businesses or B2B companies with recurring invoices, where slow settlements directly restrict available working capital.

If your processing system cannot support flexible payment options like immediate ACH transfers or digital wallet settlements, you’re locking your cash behind walls. Automation and frequent reminders can help speed up payments, while offering incentives for quick card payment or mobile transfers fosters a cycle of healthy liquidity.

Fragmented Payment Methods and Clunky Systems

Fragmentation happens when a business uses many different payment methods or disconnected platforms, making reconciliation and cash flow forecasting nearly impossible. This leads to duplicated data entry, missing payments, or even fraud exposure. Clunky payment processing systems only complicate matters: for each unique channel—be it in-store, mobile, or online—you may be managing a separate portal or workflow.

Effectively, instead of streamlining the payment process, these systems create more work, slow down collections, and create new, costly bottlenecks. The solution lies in consolidation: integrating your payment solutions to gain a holistic view of incoming and outgoing funds, streamline operations, and maximize your operational cash flow.

The Workflow of Payment Processing and Its Effect on Payment Processing Cash Flow

What is the Workflow of Payment Processing?

  • Step-by-step journey: from payment initiation to settlement

  • Key players in the payment processing system

The typical payment processing workflow starts with payment initiation (when a customer provides payment details), followed by authorization (approval by banks or card networks), clearing and settlement (moving funds between accounts), and ends with reconciliation in your accounting software. Key participants include the customer, merchant, payment gateway, merchant bank, acquiring bank, and card networks. Any inefficiency—be it a slow internet connection, data entry error, or bank hold—can extend this timeline and hurt cash flow.

Companies with automated, integrated payment systems make this journey seamless, meaning money is accessible almost instantly and records are automatically updated. Those with fragmented processing systems or lots of manual intervention, however, deal with missing funds, data discrepancies, and a prolonged wait for necessary capital.

How Workflow Inefficiencies Lead to Cash Flow Gaps

When the payment workflow is inefficient, each stage—from authorization to reconciliation—has the potential to stall, creating cash flow gaps. Manual steps increase errors and time delays, leading to missed revenue and misallocated working capital. For example, delays in batched settlements could mean waiting days or even weeks to access funds, making it hard to meet payroll, restock quickly, or pay off vendors on time.

This fragmented model also decreases customer satisfaction. A confusing or sluggish payment process can prompt abandoned carts or negative feedback, further tightening your revenue and cash flow. Businesses must re-engineer their process with automation, real-time monitoring, and seamless integration to close these gaps and drive maximum liquidity.

Comparison of Efficient vs. Inefficient Payment Processing Workflows

Efficient Workflow

Inefficient Workflow

Cash Flow Impact

Funds accessible within hours or next business day, faster reinvestment, fewer shortfalls

Funds delayed for several days/weeks, bottlenecks, higher risk of negative balances

Working Capital

Optimized, predictable, supports business growth and agility

Constrained, unpredictable, increases need for emergency borrowing

Customer Experience

Frictionless, boosts loyalty, encourages repeat sales

Frustrating, causes cart abandonment, damages reputation

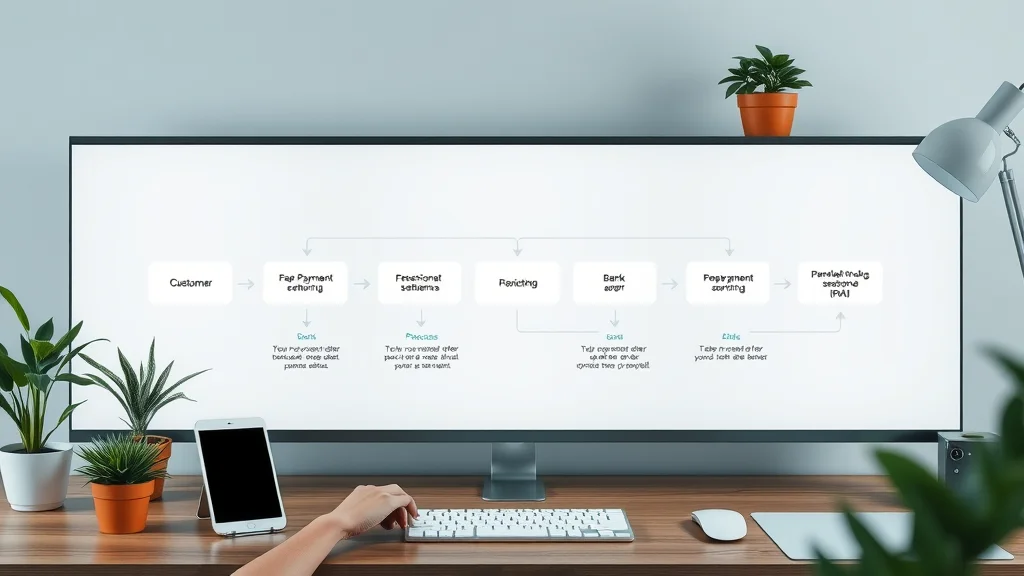
Workflow diagram showing payment processing journey and cash flow impact

Analyzing the Five Steps of Transaction Processing in Payment Processing Cash Flow

What are the 5 Steps of Transaction Processing?

  • Authorization

  • Batched Settlement

  • Clearing

  • Funding

  • Reconciliation (within accounting software)
Technological collage showing five steps of payment transaction processing across devices

The five key steps in the payment process underpin every successful transaction and healthy cash flow:

  1. Authorization: Approval from issuing bank or service, confirming available funds and legitimacy.

  2. Batched Settlement: Grouping transactions for processing, impacting when money moves.

  3. Clearing: Financial institutions verify and transmit payment data for both sides.

  4. Funding: Funds actually move into the merchant’s bank account.

  5. Reconciliation: Transactions are matched in accounting software, closing potential gaps and ensuring accuracy.

A break or delay at any step expands the time it takes to clear card payments and receive funds, multiplying the risks of errors and shortfalls in working capital.

How Each Step Influences Payment Processing Cash Flow and Working Capital

Each stage plays a fundamental part in controlling your payment processing cash flow. Issues during authorization can result in declined payments and lost sales opportunities. Slow or inefficient batched settlements can trap much-needed revenue, with delayed clearing and funding translating into real cash shortages. Finally, insufficient reconciliation processes—especially those not connected with digital accounting software—mean discrepancies may go unnoticed until it’s too late.

The takeaway: Businesses should review each of these steps, automate where possible, and ensure each processing solution is tightly integrated. This safeguards the accuracy and timeliness of available working capital for payroll, inventory, and growth.

The Relationship Between Payment Methods and Payment Processing Cash Flow

Diverse Payment Options: Pros and Cons for Your Cash Flow

  • Credit card payments

  • Bank transfers

  • Digital wallets

  • Instant payments

Offering a range of payment options enhances customer satisfaction and can improve cash flow by shortening settlement times. For example, credit card and instant payment methods (like Zelle or Venmo) generally provide quicker access to funds compared to checks or wire transfers. Digital wallets satisfy tech-savvy customers and may reduce fraud, but require up-to-date terminals and tighter security.

Each payment method comes with trade-offs. Card payments, while fast, incur higher processing costs than bank transfers. Meanwhile, fragmented solutions can increase administrative complexity if not managed effectively. The best approach is to find an optimal mix that meets customer needs while minimizing settlement delays and fees, keeping your payment processing cash flow streamlined.

How to Improve Payment Processing Cash Flow With the Right Payment Solution
Business owner optimistically using digital wallet, symbolizing improved payment processing cash flow

Improving payment processing cash flow starts with selecting modern, customer-focused payment solutions. Look for systems that seamlessly handle multiple payment methods, integrate directly with accounting software, and offer real-time reporting. Automation of reminders, instant card payment processing, and simplified reconciliation all decrease friction, speed up settlements, and maximize available working capital.

Consider investing in platforms that balance speed with security—offering both rapid settlements and robust fraud protection. Tailoring payment options to your customer base also promotes higher customer satisfaction and retention. By taking a strategic approach to payment processing solutions, you’ll ensure liquidity isn’t an afterthought but a competitive advantage.

Payment Solutions and Systems: Choosing What’s Right for Healthy Payment Processing Cash Flow

Evaluating Modern Payment Processing Systems for Better Cash Flow
Business analyst using a tablet to compare modern payment processing solutions for healthy cash flow

Start by looking at speed: do funds settle in hours or days? Then assess flexibility—can your customers use preferred payment methods like credit card, digital wallets, and mobile pay? It’s also crucial to consider support for recurring payments and how robust the customer experience is throughout the payment process

The most effective payment solutions offer full integration with accounting software, boosting accuracy and visibility. Evaluate whether the system can scale as you grow and if it provides actionable insights into cash flow and working capital. Avoid platforms that require manual reconciliation or lack transparency—these will only extend cash flow gaps over time.

Integrating Payment Solutions with Accounting Software for Seamless Payment Process

  • Simplifying reconciliation of payment transactions

  • Boosting overall visibility and control

Integration between payment solutions and your business’s accounting software eliminates tedious manual updates and reduces the risk of human error. By syncing real-time transaction data directly into your general ledger, you not only simplify reconciliation but also enhance your oversight into available working capital. This connection enables faster, more accurate reporting and reveals critical payment trends and potential bottlenecks before they escalate.

Fully integrated payment processing systems also trigger automatic alerts for failed or pending settlements—empowering your team to take rapid action. This level of workflow automation frees up staff, speeds the payment process, and ensures maximum liquidity with minimum effort.

Impact of Customer Experience on Payment Processing Cash Flow

"A seamless payment system not only retains customers but also accelerates your working capital cycle."

The link between customer experience and payment processing cash flow can’t be overstated. A frictionless, reliable payment method encourages timely payments and repeat purchases. In contrast, convoluted or error-prone systems drive up cart abandonment and result in lost revenue. Positive experiences mean customers return and promote your brand, accelerating sales as well as your access to funds.

Optimizing every touch point—from payment initiation to confirmation and refund processing—boosts not only cash flow but also your competitive edge in a crowded marketplace.

Case Studies: How Bad Payment Processing Setup Damaged Cash Flow

Small Business Example: Payment System Bottlenecks

Consider a local restaurant that insisted on manual POS terminals and paper receipts. During peak hours, order delays and double charges became common—leading to customer complaints and lost business. The owner soon realized cash deposits were delayed by several days as reconciliation required manual entry and verification. The result was a persistent cash flow gap that affected everything from inventory restocking to payroll accuracy. After switching to an integrated, cloud-based payment processing solution, deposits arrived next business day and working capital improved instantly.

Enterprise Example: Delayed Card Payment Settlement and Cash Flow Squeeze

A large e-commerce company used multiple, non-integrated payment processing systems for domestic and international sales. Processing times varied dramatically, especially for card payments from certain regions, leaving significant revenue in limbo for days at a time. The lack of unified reporting and real-time notifications left finance teams in the dark when reconciling accounts. Migrating to a modern, multi-currency payment processing solution shaved days off settlement times and freed up millions in working capital.

Lessons Learned: Best Practices for Payment Processing Cash Flow

The lessons from these cases are clear: outdated payment processing setups lead to unnecessary cash flow gaps. The most impactful moves include adopting unified payment systems, automating manual tasks, enabling instant and digital payment methods, and consistently reviewing and optimizing payment solutions for speed, flexibility, and security. These practices not only reduce errors and costs but also empower businesses to respond swiftly to opportunities.

Step-by-Step Guide: Optimizing Payment Processing Cash Flow for Your Business

Assess Your Current Payment Systems and Solutions

  • Checklist of warning signs and inefficiencies

  • Red flags in payment terms and payment methods

Pay special attention to payment terms—are overdue accounts frequent? Are customers abandoning carts due to lack of payment options?

Monitoring these metrics provides a baseline for targeted improvements. The goal: identify where cash gets “stuck” and where adopting new payment solutions will have the biggest impact on working capital.

Implement Strategic Payment Options for Better Cash Flow

  • Choosing faster payment methods

  • Automate payment process using accounting software

Choose payment options that guarantee fast settlement, such as instant ACH, card payment, or integrated digital wallets. Consider automating invoicing and regular payment reminders to ensure prompt payment. Where possible, link your payment system to real-time accounting software—this enhances visibility and reduces the opportunity for error or fraud.

Implementing these strategic payment solutions shouldn’t disrupt current business; instead, aim for phased rollouts and staff training to ensure a smooth transition. This approach maximizes the impact on cash flow without overwhelming your team.

Watch the animated explainer video below to see how different payment processing workflows affect real businesses. Learn about common pitfalls and practical solutions for supercharging your cash flow.

People Also Ask: Answering Top Payment Processing Cash Flow Questions

What is the workflow of payment processing?

The workflow includes payment initiation, authorization, settlement, reconciliation, and reporting, each affecting speed and accuracy of cash inflow to your business.

What are the 5 steps of transaction processing?

The five steps are authorization, batching, clearing, funding, and reconciliation. Each plays a vital role in maintaining steady payment processing cash flow.

What is cash flow payment?

Cash flow payment refers to incoming and outgoing money directly linked to payments processed, determining liquidity and operational health.

What are the four types of cash flows?

Operating, investing, financing, and free cash flow are four main types, each influenced by payment processing system efficiency.

FAQs: Payment Processing Cash Flow Optimization

  • How can businesses quickly identify payment processing cash flow issues?
    Watch for frequent reconciliation mismatches, delays between payment collection and funds availability, and high rates of abandoned transactions or rejected payments. These are classic signs your payment processing cash flow is suffering.

  • Which payment solutions offer the fastest impact on working capital?
    Integrated systems supporting instant ACH, digital wallets, and credit card payments typically provide the fastest boost in cash flow and working capital by shortening settlement times.

  • Are integrated payment systems worth the investment for small businesses?
    Absolutely. Integrated solutions improve accuracy, speed up collections, reduce errors, and provide better insights for decision-making, expanding working capital and supporting growth.

  • How does customer experience factor into payment processing cash flow improvement?
    A seamless, easy-to-use payment process increases customer satisfaction, shortens payment cycles, and reduces abandoned purchases—all of which accelerate cash flow into your business.

Key Takeaways for Improving Payment Processing Cash Flow

  • Bad payment processing setups create cash flow gaps and stall working capital.

  • Optimize payment solutions, payment methods, and use modern accounting software.

  • Monitor processing system workflows to ensure maximum liquidity.

  • Prioritize customer experience with streamlined payment solutions.

Hear from payment industry leaders and CFOs about transforming cash flow with next-gen payment systems in this in-depth interview.

Conclusion: Take Charge of Your Payment Processing Cash Flow

"Streamlining your payment process is more than an operational upgrade—it's a growth lever for your business."

Act now to modernize your payment systems and secure your company’s financial future.

If you’re ready to take your business’s financial health to the next level, don’t stop at optimizing payment processing alone. Building a resilient company means understanding the broader legal and operational strategies that support sustainable growth. Discover actionable advice and foundational steps for long-term success in our comprehensive resource on building a strong small business. By combining robust payment systems with sound business practices, you’ll be well-positioned to navigate challenges and seize new opportunities with confidence.
Ready to Improve Your Payment Processing Cash Flow?

Call for a free consultation at 214-854-9931

Merchant Processing & Payments

Write A Comment

*
*
Please complete the captcha to submit your comment.
Related Posts All Posts
09.16.2026

Payment Processing for Subscription-Based Startups

As you consider the essential components of subscription payment processing, it's also valuable to explore how recurring billing automation can further streamline your operations and reduce manual errors. For a practical breakdown of recurring billing best practices and actionable setup tips, check out this guide on optimizing recurring billing for startups. If you’re ready to take your startup’s payment infrastructure to the next level, it’s worth broadening your perspective beyond just payment processing. Building a resilient subscription business also means understanding the legal, operational, and strategic foundations that support long-term growth. For a comprehensive look at how to strengthen your small business from the ground up—including legal considerations and sustainable business practices—explore this in-depth resource on building a strong small business. By combining robust payment systems with holistic business strategies, you’ll be well-positioned to thrive in the competitive subscription economy.

09.09.2026

Best Merchant Services for Retail Startups

Did you know that 82% of retail startups fail without reliable payment processing? It’s true: having the right retail merchant services isn’t just nice to have—it’s mission critical for every budding retail business. This guide cuts through the noise to reveal how the right merchant service companies can unlock your startup’s growth, prevent payment pitfalls, and transform your retail store into a customer favorite. Revealing the Real Impact of Retail Merchant Services on Startup Growth As a retail startup, your path to profitability hinges on seamless payment processing solutions and the ability to quickly accept card payments, whether from credit cards, debit cards, or digital wallets. Without a trusted merchant service provider, cash flow can stall, customer trust can erode, and you risk falling behind competitors who streamline every transaction. Retail merchant services provide the lifeblood for your business, handling everything from card machine setup to chargeback protection, and direct connections to financial networks for instant day settlement. The right services company doesn’t just move money—they move your business forward. Success in the retail world means more than stocking shelves and managing staff. With over 60% of transactions now cashless in modern retail businesses, your ability to accept card payments is directly tied to sales growth, better customer experiences, and repeat purchases. Reliable payment processing opens doors for omnichannel sales, from in-store POS systems to online and mobile checkouts. In this article, we'll unpack why payment service providers are essential for startups, how to compare merchant services, and which solutions offer the competitive edge needed in a crowded retail marketplace. When evaluating merchant service providers, it's also helpful to understand how payment processing fits into the broader foundation of your business. For a deeper dive into building a resilient small business from the ground up, including legal and operational essentials, explore this comprehensive guide to small business fundamentals. A Startling Fact: 82% of Retail Startups Fail Without Reliable Payment Processing That’s right: data shows failure to secure dependable, secure merchant service relationships and easy card payment procedures puts startups at a major disadvantage. After all, friction at the checkout often leads to lost sales—and no small business can afford that. What You'll Learn About Retail Merchant Services for Small Businesses Key features of the best retail merchant services How merchant services impact retail startup success Industry-leading merchant service companies and processing solutions Retail merchant service costs and payment processing considerations Understanding Retail Merchant Services and Payment Processing Solutions What Are Retail Merchant Services? Retail merchant services refer to the comprehensive suite of payment processing tools and services that empower small businesses to accept and manage payments made with credit cards, debit cards, and other modern card payment methods. These services span everything from opening a merchant account (which functions as a temporary holding bank account) to supporting POS systems, online checkout integration, fraud management, and automated reporting. Unlike ordinary bank accounts, merchant services are tailored for fast-moving retail selling—giving you the agility to handle in-person, mobile, or online transactions with equal confidence. For startups in particular, choosing the right retail merchant service provider can make the crucial difference between seamless sales and disruptive headaches. Reliable merchant service companies streamline the way your retail business processes payments, minimize cash flow delays, and safeguard against card fraud or chargebacks. They act as trusted partners, not just vendors, giving you access to state-of-the-art card machines, virtual terminal options, and transparent processing costs tailored to your unique growth stage. How Merchant Service Companies Work for Small Business Retailers A merchant services company acts as the engine behind every successful card transaction. They enable your retail merchant setup to accept card payments by connecting your POS system or card reader to global financial networks. When a customer pays with a credit card or debit card, your merchant account receives the payment, verifies the transaction, and deposits the funds safely—typically with next-day or even same-day settlement for robust cash flow. The best services provide dashboard access for tracking sales, real-time alerts, and easy access to technical or customer support. Small business retailers benefit from merchant service companies that offer flexible contract terms (monthly or pay-as-you-go), transparent fee structures, and advanced fraud detection. Look for providers that integrate with a wide range of hardware—from advanced POS terminals to smartphone-compatible dongles—and who facilitate both physical and e-commerce transactions. This not only caters to changing customer behaviors but also ensures your retail business won’t be left behind by new payment technologies. Role of Credit Card and Card Machines in Merchant Services Card machines and POS terminals are the critical hardware components that bring merchant services to life in any retail store. These devices authenticate, process, and encrypt card payments—allowing fast, secure, and reliable checkouts whether via chip, swipe, tap, or digital wallets. Modern merchant services companies often provide or lease these machines as part of their overall service suite, ensuring compatibility with multiple card types and payment apps. Having the latest card machine or virtual terminal boosts your brand’s professionalism and customer trust. Speedy card processing means shorter lines and fewer abandoned baskets—a must for busy retail environments. On top of this, advanced POS systems can sync with inventory management, track customer preferences, and produce detailed sales reports—helping startups turn payment data into actionable business insights. Top Features of the Best Retail Merchant Services Integrated payment processing solutions Seamless credit card and debit card acceptance POS card machines and terminals Competitive pricing structures for small business Robust fraud and chargeback management The best retail merchant services go beyond simple payment acceptance. Integrated processing solutions ensure your operation can handle all forms of card payments—chip, magstripe, contactless, and even new methods like QR codes or mobile wallets. Seamless integration into your POS system reduces training time and the risk of manual entry errors. Competitive pricing—typically ranging from 1. 5% to 3. 5% on card transactions—is vital for protecting margins, while robust chargeback management provisions shield your business from common pitfalls that disrupt cash flow. When choosing a service provider, ensure they offer fraud detection tools, next-day settlements, online reporting, and on-demand customer service. Whether you’re processing a few card transactions per day or managing multi-location sales, these features will help your startup operate efficiently and confidently in a fast-moving retail landscape. Comparison Table: Leading Retail Merchant Service Companies Merchant Service Company Key Features Costs & Fees Contract Terms Processing Speed Best For Square Free POS, card reader, online invoicing, real-time reporting 2.6% + 10¢ per transaction No long-term contract Next day Retail popups & startups Clover Customizable POS, inventory tools, contactless payments 2.3% + 10¢ per transaction Monthly contracts Same or next day Growing small businesses Helcim Transparent pricing, virtual terminal, advanced security Interchange + 0.3% + 8¢ No contract 1-2 days Cost-conscious startups Stripe API integration, online/offline payments, fraud detection 2.9% + 30¢ per online transaction Month-to-month 2 days Omnichannel retailers PayPal Zettle Simple POS, card reader, eCommerce sync 2.29% per transaction No contract Next day Side businesses & mobile sellers Best Retail Merchant Services for Startups: Detailed Reviews Review: [Top Merchant Service Company #1] Square is a pioneer in retail payment processing solutions, renowned for intuitive design, transparent pricing, and no-hassle contracts. Their free POS system, coupled with an affordable card reader, allows startups to accept credit and debit card payments anywhere—whether in-store, curbside, or at pop-up events. Square stands out for its crystal-clear 2. 6% + 10¢ per transaction fee—no hidden costs or monthly minimums. With seamless integration into modern retail environments, Square helps small businesses thrive by ensuring reliable cash flow, same-day settlements, and 24/7 support. Comprehensive sales and customer insights are only a tap away in the Square Dashboard, giving startup retailers a powerful advantage in a competitive market. Alongside brick-and-mortar capability, Square supports online checkouts and digital wallet payments, allowing retailers to meet customers where they shop. With built-in chargeback protection and fraud detection, it keeps your business secure as you scale. For startups needing adaptability, speed, and transparent service, Square is among the best in the industry. Review: [Top Merchant Service Company #2] Clover is a favorite among retail merchants looking for a customizable and scalable POS ecosystem. Its modular system—featuring everything from sleek card machines and contactless card readers to inventory management tools—caters to both new startups and growing businesses. Clover’s transaction fees are competitive (2. 3% + 10¢), and the platform offers monthly contract flexibility, important for startups wary of long-term commitments. What sets Clover apart is its vast app marketplace, empowering retailers to expand as their needs evolve—from customer loyalty programs to online store integration. With robust support for debit and credit card acceptance, quick day settlement, and superior chargeback resolution, Clover is ideal for startups seeking growth potential. Their hardware options cover everything from stationary POS terminals to mobile card readers for smartphone or tablet use—all backed by industry-standard security and PCI compliance. Review: [Top Merchant Service Company #3] Helcim is best known for its radically transparent, low-cost pricing—making it a top pick for cost-conscious retail startups. Helcim uses an interchange-plus structure, with rates as low as interchange + 0. 3% + 8¢ per transaction, passing savings directly to retailers as they grow. Their POS system is user-friendly and versatile, supporting both brick-and-mortar and online sales, plus a powerful virtual terminal for phone or mail orders. Helcim includes free PCI compliance and advanced security tools to protect against fraud and chargebacks, reducing risk for small businesses. Fast processing (1-2 day settlement), real-time reporting, and no long-term contracts help startups stay agile while maintaining healthy cash flow. Helcim’s strong focus on customer support and resource guides is an additional plus for first-time business owners navigating retail payment systems for the very first time. How to Choose the Right Retail Merchant Services for Your Startup Assessing processing solutions and hardware needs Comparing credit card transaction fees Evaluating customer support and merchant account services Considering setup costs and contract flexibility Choosing the optimal merchant services company starts with a frank assessment of your retail operation’s scale, expected transaction volume, and technical requirements. New startups may want low-cost, plug-and-play solutions like Square or PayPal Zettle, while ambitious businesses gearing up for rapid growth might benefit from an all-in-one system like Clover or customizable solutions like Helcim. Carefully compare credit card and debit card fees—not just per-transaction charges, but also hidden costs like PCI compliance, service provider support, chargeback fees, and hardware rentals. Pay special attention to setup timelines, ease of onboarding, contract flexibility, and whether the provider offers responsive customer support via multiple channels. Look for transparent terms, quick day settlement for consistent cash flow, and integration with online platforms for omnichannel sales. Startups should choose a merchant account that scales with the business and won’t lock them into restrictive or costly arrangements. Video Guide: Setting Up Retail Merchant Services for Small Businesses Expert Quote: On the Value of Merchant Services for Retail Small Business "Choosing the right retail merchant service can mean the difference between thriving and surviving for startups. Reliable payment processing is your lifeline to steady revenue." — Industry Payment Professional People Also Ask: Frequently Searched Questions About Retail Merchant Services Who owns retail merchant services? Answer: Retail merchant services can be owned by independent companies, financial institutions, or specialized payment processors offering merchant accounts and processing solutions to retailers. What does a retail merchant do? Answer: A retail merchant manages the sale of goods and services to customers, handling payments, inventory, and customer service—crucially relying on merchant services for secure credit card and digital payment processing. How much does retail merchant services charge? Answer: Costs vary by merchant service company but typically include transaction fees, monthly service charges, and equipment costs. Fees for retail merchant services generally range from 1. 5% to 3. 5% per credit card transaction. What's the cheapest way to accept credit cards? Answer: The least expensive option is often a flat-rate processing solution with no long-term contract or monthly minimums. Many retail merchant service providers now offer transparent pricing for small business startups. Video Tutorial: Comparing Card Machines and Payment Processing Solutions Pros and Cons List: Retail Merchant Services for Startups Pros: Fast payments, increased sales, improved customer trust, flexible payment processing. Cons: Monthly and transaction fees, contract terms, potential chargebacks. FAQs: Quick Answers to Retail Merchant Services Queries What is the difference between retail merchant services and traditional bank accounts? Retail merchant services provide specialized payment processing, chargeback protection, and point-of-sale integrations—unlike standard bank accounts, which do not process customer card transactions or offer POS solutions. Are retail merchant services necessary for online retail businesses? Yes—any business selling online needs a merchant account or payment services company to securely process credit card and digital wallet payments. Can startups negotiate payment processing fees with merchant service companies? In many cases, yes—startups with higher volume or growth potential can often negotiate lower rates or transaction fees with providers. What is PCI compliance and why does it matter for small business retailers? PCI compliance ensures your payment system securely handles cardholder data, protecting against fraud and data breaches—a prerequisite for any retail merchant service provider. Key Takeaways: Finding the Best Retail Merchant Services for Your Business Choosing optimal retail merchant services requires comparing features, pricing, and support. Reliable payment processing is essential for retail startup growth and customer trust. Startups benefit from transparent, scalable, and secure merchant service solutions. Ready to Grow Your Startup? Call for a Free Consultation at 214-854-9931 With the right retail merchant services partner, your startup can thrive—unlocking faster sales, happier customers, and steady growth in a dynamic retail landscape. As you continue to refine your retail startup’s payment infrastructure, remember that merchant services are just one pillar of a resilient business. For a holistic approach to building a strong foundation—covering legal, operational, and strategic considerations—take the next step by reviewing expert guidance for small business success. This resource offers actionable insights that go beyond payments, helping you future-proof your venture and navigate the challenges of growth with confidence. Investing in both robust merchant services and sound business practices will position your startup for long-term achievement in today’s competitive retail landscape.

09.02.2026

How Chargebacks Hurt Startup Merchant Accounts

Did you know over 80% of startups are hit with chargebacks in their first year—risking not only their revenue but their very survival? While many founders focus on growth and customer acquisition, few realize just how devastating chargebacks can be to young businesses. In this article, you’ll learn how startup chargeback prevention can save your company from costly pitfalls, secure your merchant account, and ultimately protect your business as you scale. A Startling Look at Startup Chargeback Prevention and Its Impact on Startup Merchant Accounts Unveiling a surprising statistic: Over 80% of startups experience chargebacks within their first year. Why startup chargeback prevention is more than just a finance issue—it's a survival strategy. “Chargebacks aren’t just the cost of doing business—they can be the difference between scaling or shuttering your startup.” What You'll Learn About Startup Chargeback Prevention How chargebacks can undermine your startup's financial stability. Comprehensive startup chargeback prevention techniques. Key steps to protect your merchant account from chargeback fraud. Role of payment processors and customer service in friendly fraud. Understanding Chargeback Prevention for Startup Merchant Accounts What Are Chargebacks and Why Do Startups Need Prevention? Chargebacks occur when a cardholder disputes a credit card charge directly with their issuing bank, prompting a reversal of funds from your merchant account. For startup merchants, frequent chargebacks aren’t just minor hiccups—they can lead to costly penalties, loss of payment processing privileges, or even a frozen bank account. This is why startup chargeback prevention is critical from day one. Startups often operate on slim margins, and a few unexpected reversals are enough to throw off cash flow, frustrate business owners, and threaten your bottom line. By prioritizing chargeback prevention, startups can proactively shield themselves against these setbacks, ensure smooth payment processing, and protect your revenue as you grow. For startups looking to further strengthen their defenses, understanding the legal and operational foundations of small business management is equally important. Exploring guidance for building a strong small business can provide additional strategies that complement your chargeback prevention efforts and support long-term stability. How Credit Card Chargeback Works in Startup Contexts A chargeback typically starts when a customer disputes a card charge with their card issuer, often citing fraud, dissatisfaction, or a failure in customer service. The card issuer then temporarily removes the funds from your account and starts the dispute process, collecting evidence from both the cardholder and merchant. For startups, responding quickly and providing compelling documentation is essential to prevent losing both the funds and customer trust. The process exposes founders to complex interactions with card companies and strict timelines set by the issuing bank. Failing to follow through can result in penalties, an increased chargeback ratio, and potential termination of your payment processing capabilities—underscoring the need for proactive chargeback management and robust prevention strategies. The Growing Importance of Chargeback Prevention Strategies for Startups Startups today face a landscape where fraudsters are more sophisticated and card charge disputes are on the rise. As card not present (CNP) transactions increase, so does exposure to friendly fraud and chargeback fraud. Prevention strategies go beyond simple transaction monitoring. They involve advanced fraud detection, swift customer service, and leveraging partnerships with the right payment processor. The earlier you establish chargeback prevention protocols, the better protected your startup will be from the start. Building these strategies helps prevent chargebacks, protect your business reputation, and positions your company to scale confidently—even in a challenging fintech environment. Chargeback Type Description Impacts Prevention Methods Card Charge Legitimate transaction later disputed by customer Loss of funds, higher chargeback ratio, potential account termination Clear billing, timely delivery, signature confirmation Fraudulent Chargeback Unauthorized or counterfeit credit card use Revenue loss, fines, increased costs of fraud prevention Fraud detection tools, AVS, CVV checks, EMV Friendly Fraud Customer falsely claims fraud/dispute to recover funds Loss of goods/services and funds, customer trust erosion Strong communication, order tracking, providing clear receipts How Chargebacks Disrupt Startup Businesses—and Why Startup Chargeback Prevention Matters Startup Chargeback Prevention and Its Direct Effects on Revenue and Growth Chargebacks directly chip away at your startup’s revenue and can stall growth in unexpected ways. Every disputed transaction not only results in lost income but also compounds into fees levied by card companies and payment processors. If your chargeback ratio rises above what the processor allows, you risk having your merchant account frozen or terminated. For startups, these penalties can rapidly escalate, making it essential to prevent chargebacks from the outset. Additionally, the financial stability of your business is threatened, as cash flow crunches limit your ability to invest in operations or marketing. Proactive chargeback prevention strategies are essential to safeguard your bottom line and allow uninterrupted growth, especially in the competitive early stages of business. Protecting Your Business from Card Chargeback Risks The risk of card chargebacks increases as your business grows. Effective startup chargeback prevention means identifying potential vulnerabilities in your payment systems and customer service, addressing them before they become liabilities. Integrating fraud detection software, authenticating credit card transactions, and educating your team on common causes of disputes can substantially reduce chargebacks. Remember, the goal is not just to recover lost funds, but to create an environment where disputes are minimized and your reputation remains intact. When founders make prevention a core business objective, they reduce the chances of merchant account loss, preserve cash flow, and protect your business for the long run. Case Study: How a Startup Lost Access to Its Payment Processor After Chargeback Fraud Consider the story of a SaaS founder whose business was thriving—until a wave of friendly fraud chargebacks hit their merchant account. Despite strong sales, the startup failed to respond promptly to disputes and lacked a systematic chargeback prevention plan. Their payment processor flagged the high chargeback ratio and, with little warning, shut off their merchant account. The founder struggled to secure a new processor, customers experienced service interruptions, and revenue came screeching to a halt. This highlights the real-world stakes of startup chargeback prevention: inaction leads to lost payment processing capabilities and, for many startups, a swift downward spiral. “Losing your merchant account is often just the first domino in a cascade of failures for startups.” Identifying the Main Causes of Chargebacks for Startups Common credit card chargeback scenarios in early-stage businesses. Role of customer service failures in creating avoidable disputes. Friendly fraud: What it is and why startups are vulnerable. Detecting and Preventing Friendly Fraud in Startups Friendly fraud, where a genuine customer falsely claims they didn’t receive the product or were charged erroneously, is especially dangerous for startups. Startups are more vulnerable because they may lack robust verification systems or proactive communication. Preventing friendly fraud requires clear receipts, detailed tracking, swift responses to customer complaints, and educating customers on your billing practices. Implementing automated fraud detection tools and working closely with your payment processor can help flag suspicious behavior. Ultimately, integrating prevention strategies into your daily operations will minimize losses from friendly fraud and maintain healthy customer relations. Payment Processor Rules and Card Charge Dispute Process Your payment processor has strict policies for responding to card chargebacks. The dispute process is time-sensitive: after a chargeback is initiated, you have a short window to provide evidence such as order confirmations, delivery proofs, and communication history. Failing to comply may result in financial penalties and jeopardize your merchant account. Understanding the rules—including chargeback thresholds and what the card issuer requires—puts startups at an advantage when navigating these disputes. Robust documentation and prompt communication with your processor are key components of effective chargeback management, ensuring you don’t lose disputes by default and that you protect your revenue as you grow. Startup Chargeback Prevention Strategies: Avoid Card Chargeback Pitfalls Top 10 startup chargeback prevention tips. Implementation of fraud prevention tools for early-stage businesses. Developing a proactive customer service approach for dispute resolution. “Investing in robust startup chargeback prevention techniques pays for itself.” Leveraging Payment Processor Solutions for Effective Startup Chargeback Prevention Payment processors are invaluable allies in preventing chargebacks. Advanced processors offer real-time alerts, fraud filters, and chargeback representment services tailored for startups. By selecting a processor equipped with the latest fraud detection tools, businesses immediately reduce their risk. Ensure your payment partner has experience with chargeback prevention, provides transparent reporting, and supports you in building airtight documentation. Such partnerships help founders stay one step ahead, enabling startups to focus on growth while safeguarding transaction stability and customer trust. Best Practices for Credit Card Charge Monitoring Monitoring every credit card charge—both for patterns of fraud and for customer satisfaction—is central to chargeback prevention. Implement daily transaction reviews, automated alerts for large or suspicious charges, and regular reconciliation of payments. Utilize your processor’s dashboards to spot anomalies early. This vigilance allows business owners to catch issues before they escalate, address disputes promptly, and maintain a healthy chargeback ratio. Incorporating these monitoring routines into your financial workflow means you’re always prepared to combat card chargeback issues. Integrating Fraud Detection for Ongoing Card Charge Protection Fraud detection solutions powered by AI and machine learning are now accessible even for startups. These tools automatically flag irregular purchase patterns, mismatched billing details, and high-risk locations before the transaction is completed. Startups benefit from integrating these technologies, as they help prevent chargebacks before they materialize, save hours of manual review, and add a crucial layer of security. By investing in ongoing fraud prevention technology, you protect your business, reduce chargebacks, and establish a reputation for secure and reliable payment processing. Startup Chargeback Fraud: Identifying and Responding to Threats Understanding Chargeback Fraud and Its Consequences for Startups Chargeback fraud occurs when a transaction is intentionally disputed under false pretenses, often by individuals exploiting loopholes in the payment system. For startups, the stakes are high: too many fraudulent chargebacks will not only cost you goods or services and transaction value, but also risk your merchant account status and brand reputation. Small businesses and startups are especially susceptible because their verification and disruption response may not match those of established enterprises. Proactive monitoring, advanced fraud detection tools, and documented evidence are essential defenses against this growing threat in the digital economy. How Startups Can Prevent Chargeback Fraud with Modern Technology Modern technology offers startups a variety of ways to prevent chargeback fraud effectively. Implementing AVS (Address Verification Service), CVV checks, two-factor authentication, and device fingerprinting minimizes unauthorized transactions. Machine learning-based fraud analytics can detect patterns and flag high-risk behavior before the sale completes. Combining these technological tools with timely customer communication significantly lowers the risk of chargeback fraud and demonstrates to both card providers and customers that you’re a vigilant merchant. Proactive defense is not just best practice; it’s essential to safeguard your business’s future. Step-by-Step Guide to Navigating the Dispute Process When a chargeback occurs, swift action is essential. First, promptly review the dispute notification from your payment processor, then gather all transaction records, delivery confirmations, and communication history with the customer. Next, prepare a clear, organized response and submit it through your payment processor’s chargeback dispute portal. Remain in communication with both the processor and your customer throughout the process. Consistent documentation and rapid response are the foundation of successful dispute resolution—giving your startup the best chance to recover funds and maintain a healthy merchant account standing. “Every successful dispute recovery is a lesson in startup resilience.” Customer Service as a Pillar of Startup Chargeback Prevention Creating Seamless Experiences to Preventing Chargebacks Exceptional customer service is one of the most effective ways to prevent chargebacks. By creating seamless and transparent customer journeys—from easy checkout processes to proactive support—founders drastically reduce the chances of a dispute ever arising. Resolve issues before they escalate and ensure customers have multiple channels to reach your team. Every positive experience is an insurance policy against chargebacks, friendly fraud, and reputational damage. Make customer satisfaction an integral part of your chargeback prevention strategies. How Fast, Transparent Communication Protects Your Revenue Clear, timely, and honest communication is central to protect your revenue. When an issue is detected, quick outreach can turn a potential dispute into an amicable resolution. Explain company policies, refund procedures, and dispute timelines transparently. By keeping customers in the loop, you demonstrate reliability, reduce frustration, and limit the tendency to file a chargeback. Staff should be empowered to solve problems efficiently—building loyalty and minimizing costly card chargeback events. Training Staff for Chargeback Prevention Excellence Your team is your first line of defense against chargebacks. Invest in regular training that covers identifying early signs of disputes, communicating chargeback policies with clarity, and using your payment processor’s chargeback management tools. Employees should understand how to interpret fraud alerts and manage the dispute process professionally. Ongoing training keeps your company’s prevention skills sharp as card company regulations and fraud tactics evolve. This culture of vigilance helps your startup avoid common pitfalls and lowers exposure to unnecessary financial risk. Startup Chargeback Prevention and the Role of Payment Processors How to Choose a Payment Processor With Strong Startup Chargeback Prevention Tools Selecting a payment processor capable of supporting your startup chargeback prevention goals is vital. Compare processors based on features like built-in fraud detection, chargeback reporting, threshold alerts, and transparent chargeback dispute support. Ask about experience working with startups and ensure they offer dedicated support for early-stage businesses. A processor invested in your success shares best practices and provides a partnership—not just a service—helping ensure your merchant account remains in good standing as you grow. Consider costs, integrations, and the quality of their chargeback prevention tools when making your selection. What to Know About Payment Processor Chargeback Dispute Procedures Familiarity with your processor’s chargeback dispute process can save you time and money. Know the documentation you need, the timeframes for response, escalation procedures, and what your processor requires for a successful dispute. Work with their support team to ensure your policies and evidence meet standards set by card issuers. This proactive approach allows founders to protect your business and learn from each dispute—constantly refining prevention measures for the future. Ask questions upfront and establish clear communication channels with your processor from the very beginning. Essential Fraud Detection and Prevention Tools for Startups Automated fraud detection for preventing card chargebacks. Benefits of AI-driven chargeback prevention solutions. Third-party tools for real-time monitoring and reporting. Documenting and Reporting for Startup Chargeback Prevention Keeping Accurate Records for Evidence in the Dispute Process Winning chargeback disputes depends on your ability to produce timely, accurate evidence. Maintain digital records of every transaction, communication, shipping confirmation, and refund. Use secure cloud storage or CRM systems that timestamp actions. This detailed documentation acts as your insurance policy in the event of a chargeback—providing compelling proof to card companies and payment processors. Dedicated record keeping is an investment in both financial safety and operational resilience, helping you reduce chargebacks and protect your merchant account for the long term. Best Practices for Documenting Customer Communication Every interaction with customers can serve as evidence in the dispute process. Ensure all communication (emails, chat transcripts, call logs) is stored systematically and linked with corresponding transactions. Set up standard templates for confirming orders, shipping updates, and issue resolution summaries. This not only streamlines chargeback management, but also strengthens customer trust. Well-documented communication satisfies card issuers’ evidence requirements and places your startup in the strongest possible position to recover revenue when challenged. Training and Education for Ongoing Startup Chargeback Prevention Internal policy creation for preventing chargebacks. Ongoing team training: Why it matters for long-term fraud prevention. Startup Chargeback Prevention Case Studies: Success Stories and Lessons Learned “Our chargebacks dropped by 70% after implementing comprehensive prevention strategies.” – A fintech founder Many emerging fintech businesses and SaaS startups have turned their fortunes around by adopting comprehensive startup chargeback prevention programs. These companies focused on deploying automated fraud detection, strengthening customer service, and closely monitoring card chargebacks. Within months, they saw massive reductions in disputed transactions, better payment processor relationships, and significant improvements to their bottom line. The lesson: preventative action, not reaction, makes all the difference in scaling a resilient company. Comparing Chargeback Prevention Solutions for Startups Tool Key Features Cost (Monthly) Effectiveness FraudShield Pro AI analytics, instant alerts, integrates with all major processors $49–$99 High for early-stage SaaS and ecommerce startups Chargeback Defender Automated representment, real-time resolution, chargeback reports $79–$129 Excellent for dispute-heavy businesses SecurePay Plus Manual review assist, chargeback dispute support, notification system $59–$99 Best for high-ticket-item startups Key Takeaways: Why Startup Chargeback Prevention Should Be Every Founder’s Priority Startup chargeback prevention is central to protecting your business and revenue. Effective strategies reduce the risk of merchant account loss. Ongoing education, customer service, and technology adoption are essential. Startup Chargeback Prevention FAQs What are the first steps to implement startup chargeback prevention? Start by selecting a payment processor with robust prevention features, train your staff, establish clear customer communication protocols, and implement real-time fraud detection tools. How can fintech startups prevent friendly fraud and chargeback fraud? Use transparent billing, keep comprehensive transaction records, respond quickly to customer inquiries, and consider AI-powered fraud detection to spot suspicious activity before it escalates. When do payment processors terminate merchant accounts for excessive card chargebacks? Most payment processors set a strict threshold; if your chargeback ratio exceeds 1% of your monthly transactions, you risk termination. Immediate action is critical if you approach this limit. Are automated fraud detection tools essential for startup chargeback prevention? Yes, especially as your transaction volume increases. Automation helps flag high-risk charges instantly, preventing fraudulent transactions from going through and reducing costly disputes. People Also Ask: Startup Chargeback Prevention How can startups reduce the risk of credit card chargebacks? Startups can reduce the risk of credit card chargebacks by using proactive communication, implementing clear billing descriptors, monitoring for suspicious transactions, providing accurate delivery timelines, and training teams to resolve issues quickly, all as part of a comprehensive startup chargeback prevention plan. What is the best chargeback prevention strategy for a new merchant account? The best strategy combines fraud detection tools, transparent customer service processes, clear refund policies, and ongoing documentation of every transaction. Leveraging your payment processor’s resources further reduces exposure to card chargebacks and ensures early-stage protection. How does startup chargeback prevention differ from traditional chargeback prevention? Startup chargeback prevention places more emphasis on rapid response and flexibility, using technology and internal training to overcome limited resources. Startups also require solutions tailored to high risk, low volume, and the unique challenges of scaling rapidly. Can a startup recover from excessive chargebacks? Yes, but recovery requires immediate action: lowering the chargeback rate, switching processors if necessary, improving fraud prevention systems, and retraining staff. Quick recovery strategies—backed by smarter documentation—restore merchant privileges and rebuild trust with partners. What role does customer service play in preventing chargebacks for startups? Exceptional customer service minimizes dispute escalation, resolves complaints promptly, and fosters transparency—all of which are proven to prevent chargebacks before they happen. It’s a fundamental pillar of effective startup chargeback prevention. Are all payment processors equal when it comes to startup chargeback prevention? No. Some processors offer specialized tools, dedicated support, and startup-focused solutions, while others have minimal prevention options. Research and choose a processor aligned with your business’s chargeback prevention needs to ensure the best protection. Ready to Secure Your Startup? Call for a Free Consultation at 214-854-9931 Conclusion: Startup chargeback prevention is not optional—it’s your safeguard to protecting revenue, ensuring scalable growth, and building a business that stands the test of time. Take action now to strengthen your defenses and allow your vision to thrive. As you continue to refine your chargeback prevention strategies, remember that building a resilient business goes beyond just managing disputes. By investing in the right legal, operational, and financial frameworks, you set the stage for sustainable growth and long-term success. For a deeper dive into foundational business practices that can further protect and empower your startup, consider reviewing comprehensive guidance for building a strong small business. This resource offers actionable insights that complement your chargeback prevention efforts and help you navigate the broader challenges of entrepreneurship with confidence.

About Us:

At Renwick Evans and Associates, we deliver tailored consulting strategies that support your business's unique journey toward growth and success.

We provide strategic guidance for small business owners seeking clarity, stability, and growth. Our services support businesses at every stage—from startup to expansion—through smart strategy and practical solutions.

Connect with Us:

Phone: 214-854-9931

Click to Call Now

{"name":"Call Footer","action_type":"3","optin_action_type":"5","form_redirect_type":"3","form_redirect_funnel_url":"uaahut61mb","form_redirect_custom_url":"","order_form_settings":{"containers":[{"id":"personal-info-wrapper","visible":true,"label":{"id":"of-personal-title","visible":true},"fields":[{"id":"of-full-name","setting":false,"placeholder":"Full Name"},{"id":"of-field-email","setting":false,"placeholder":"Email Address"},{"id":"of-phone-number","setting":true,"visible":false,"require":true,"placeholder":"Enter Your Mobile Phone","additional":{"sms_permission":0}},{"id":"of-gdpr-optin-approval","label":"I Accept To Receive Additional Info","placeholder":"","icon":"fa-mobile","required":0,"visible":0,"system":1,"additional":{"gdpr_optin_approval":"1"}}]},{"id":"shipping-information-wrapper","visible":false,"label":{"id":"of-shipping-title","visible":true},"fields":[{"id":"of-shipping-address","setting":false,"placeholder":"Address"},{"id":"of-shipping-city","setting":false,"placeholder":"City"},{"id":"of-shipping-state","setting":false,"placeholder":"State"},{"id":"of-shipping-zipcode","setting":false,"placeholder":"Postal Code"}]},{"id":"profit-bump-wrapper","visible":true,"otoBgColor":"rgba(219,229,239,1)","otoBorderColor":"rgba(38,71,102,1)","otoTitleBgColor":"rgba(45,78,108,1)","otoArrowsColor":"rgba(255,177,58,1)","fields":[]},{"id":"order-summary-wrapper","visible":true,"orderDynamicBgColor":"rgba(242,242,242,1)","orderDynamicTexColor":"rgba(51,51,51,1)","fields":[]}]},"optin_type":{"showLabels":0,"fields":[{"name":"first_name","label":"Full Name","placeholder":"Enter Your Full Name","icon":"fa-user","required":1,"visible":1,"system":1,"additional":{}},{"name":"last_name","label":"Full Name","placeholder":"Enter Your Full Name","icon":"fa-user","required":1,"visible":1,"system":1,"additional":{}},{"name":"email","label":"Email","placeholder":"Enter Your Email","icon":"fa-envelope","required":1,"visible":1,"system":1,"additional":{}},{"name":"mobile_phone","label":"Mobile Phone","placeholder":"Enter Your Mobile Phone","icon":"fa-mobile","required":0,"visible":0,"system":1,"additional":{"sms_permission":0}},{"name":"fields_labels","label":"","placeholder":"","icon":"","required":0,"visible":1,"system":1,"additional":{}},{"name":"captcha","label":"Captcha","placeholder":"","icon":"","required":1,"visible":1,"system":1,"additional":{}},{"name":"gdpr_optin_approval","label":"SSBBY2NlcHQgVG8gUmVjZWl2ZSBBZGRpdGlvbmFsIEluZm8=","placeholder":"","icon":"fa-mobile","required":0,"visible":1,"system":1,"additional":{"gdpr_optin_approval":"1","sms_permission":0}}],"customFields":[],"sortedFields":[{"name":"first_name","label":"Full Name","placeholder":"Enter Your Full Name","icon":"fa-user","required":1,"visible":1,"system":1,"additional":{}},{"name":"first_name","label":"Full Name","placeholder":"Enter Your Full Name","icon":"fa-user","required":1,"visible":1,"system":1,"additional":{}},{"name":"last_name","label":"Full Name","placeholder":"Enter Your Full Name","icon":"fa-user","required":1,"visible":1,"system":1,"additional":{}},{"name":"email","label":"Email","placeholder":"Enter Your Email","icon":"fa-envelope","required":1,"visible":1,"system":1,"additional":{}},{"name":"mobile_phone","label":"Mobile Phone","placeholder":"Enter Your Mobile Phone","icon":"fa-mobile","required":0,"visible":0,"system":1,"additional":{"sms_permission":0}},{"name":"captcha","label":"Captcha","placeholder":"","icon":"","required":1,"visible":1,"system":1,"additional":{}}],"design":{"form_background_color":"rgb(245, 245, 245)","field_stroke":{"size":"1","color":"rgb(220, 220, 220)"},"field_icons":1,"button_color":"rgb(255, 158, 0)","button_stroke":{"size":"0","color":"rgba(255, 255, 255, 0.2)"},"button_box_shadow_color":"none","field_size":"small","label_size":"16","label_color":"rgb(0, 0, 0)","input_color":"rgb(52, 152, 219)","control_text_color":"rgb(0, 0, 0)","control_text_size":"15"},"mappedFields":[]},"redirect_type":{"url":"","target":0},"next_step":{"value":"uaahut61mb"},"click_to_email":{"value":""},"click_to_call":{"value":"2148549931"},"jump_to_block":{},"content":{"header_text":"PHNwYW4gc3R5bGU9ImZvbnQtc2l6ZToyNHB4OyBmb250LWZhbWlseTonb3BlbiBzYW5zJzsiPjxzcGFuIHN0eWxlPSJsaW5lLWhlaWdodDoxLjRlbTsiPldlIEFyZSBFeGNpdGVkITwvc3Bhbj48L3NwYW4+","content_text":"PHNwYW4gc3R5bGU9ImZvbnQtc2l6ZTo0OHB4OyBmb250LWZhbWlseTonb3BlbiBzYW5zJzsiPjxzcGFuIHN0eWxlPSJsaW5lLWhlaWdodDowLjllbTsiPjxzdHJvbmc+UExFQVNFIEZJTEwgT1VUIFlPVVIgSU5GTyAgQkVMT1cgVE8gU1VCU0NSSUJFPC9zdHJvbmc+PC9zcGFuPjwvc3Bhbj4=","button_text":"PHNwYW4gc3R5bGU9ImZvbnQtc2l6ZToyN3B4OyBmb250LWZhbWlseTonb3BlbiBzYW5zJzsiPjxzcGFuIHN0eWxlPSJsaW5lLWhlaWdodDoxZW07Ij48c3Ryb25nPlNFQ1VSRSBNWSBTUE9UPC9zdHJvbmc+PC9zcGFuPjwvc3Bhbj4=","spam_text":"PHNwYW4gc3R5bGU9ImxpbmUtaGVpZ2h0OjEuMmVtOyI+V2UgaGF0ZSBTUEFNIGFuZCBwcm9taXNlIHRvIGtlZXAgeW91ciBlbWFpbCBhZGRyZXNzIHNhZmU8L3NwYW4+","sms_text":"UmVjZWl2ZSBTTVMgVGV4dCBVcGRhdGVzIC0gPHNwYW4+b3B0aW9uYWw8L3NwYW4+","sms_text2":"SSBBY2NlcHQgVG8gUmVjZWl2ZSBBZGRpdGlvbmFsIEluZm8="},"email_confirmation":{"enable":1,"subject":"V2UgQXJlIEV4Y2l0ZWQhIFlvdXIgSW4h","message":""},"integrations":[],"automation_enable":0,"thank_you":{"type":"popup","redirect_url":"","popup_options":{"background_color":"#ffffff","headline_visible":1,"icon_visible":1,"icon_url":"//my.funnelpages.com/assets-pb/images/thankyou-popup-icon.png","subheadline_visible":1,"button_visible":1,"button_color":"#ffa800","headline_text":"PHNwYW4gc3R5bGU9ImxpbmUtaGVpZ2h0OjEuNGVtOyI+VGhhbmsgWW91IEZvciBDb250YWN0aW5nIFVzPC9zcGFuPg==","subeadline_text":"PHNwYW4gc3R5bGU9ImxpbmUtaGVpZ2h0OjEuNGVtOyI+UGxlYXNlIENoZWNrIFlvdXIgRW1haWw8YnIgLz5XZSBXaWxsIEJlIEZvbGxvd2luZyBVcCBTaG9ydGx5PC9zcGFuPg==","button_text":"Q2xvc2U="}}}

Our Approach:

We believe strategy comes before solutions. By focusing on clarity, transparency, and measurable outcomes, we help business owners make informed decisions that move their businesses forward.

Our mission is to help small businesses rise to new heights through clear strategy, smarter systems, and confident decision-making.

© 2026 Renwick Evans & Associates All Rights Reserved. 5318 S. Hampton Rd. , Dallas, TX 75232. Contact Us. Terms of Service . Privacy Policy

This website contains content that has been created using AI. Results created with AI can be inaccurate, unreliable, and subject to hallucinations. Renwick Evans & Associates disclaims any and all liability arising from use of its AI tool or services. Results created with AI are generally not protectable under intellectual property law, so Users assume all risk associated with potential liability and non-protectability arising from its use. For further details, see the Terms, available above.
eyJjb21wYW55IjoiUmVud2ljayBFdmFucyAmIEFzc29jaWF0ZXMiLCJhZGRyZXNzIjoiNTMxOCBTLiBIYW1wdG9uIFJkLiAgIiwiY2l0eSI6IkRhbGxhcyIsInN0YXRlIjoiVFgiLCJ6aXAiOiI3NTIzMiIsImVtYWlsIjoicmVud2lja0ByZW53aWNrZXZhbnMuY29tIiwidG9zIjoiUEhBK1BITjBjbTl1Wno0OFpXMCtWMmhsYmlCNWIzVWdjMmxuYmkxcGJpQjNhWFJvSUhWekxDQjViM1VnWVhKbElHZHBkbWx1WnladVluTndPeUI1YjNWeUlIQmxjbTFwYzNOcGIyNGdZVzVrSUdOdmJuTmxiblFnZEc4Z2MyVnVaQ0I1YjNVZ1pXMWhhV3dnWVc1a0wyOXlJRk5OVXlCMFpYaDBJRzFsYzNOaFoyVnpMaUJDZVNCamFHVmphMmx1WnlCMGFHVWdWR1Z5YlhNZ1lXNWtJRU52Ym1ScGRHbHZibk1nWW05NElHRnVaQ0JpZVNCemFXZHVhVzVuSUdsdUlIbHZkU0JoZFhSdmJXRjBhV05oYkd4NUlHTnZibVpwY20wZ2RHaGhkQ0I1YjNVZ1lXTmpaWEIwSUdGc2JDQjBaWEp0Y3lCcGJpQjBhR2x6SUdGbmNtVmxiV1Z1ZEM0OEwyVnRQand2YzNSeWIyNW5Qand2Y0Q0S0NqeHdQaVp1WW5Od096d3ZjRDRLQ2p4d1BqeHpkSEp2Ym1jK1UwVlNWa2xEUlR3dmMzUnliMjVuUGp3dmNENEtDanh3UGxkbElIQnliM1pwWkdVZ1lTQnpaWEoyYVdObElIUm9ZWFFnWTNWeWNtVnVkR3g1SUdGc2JHOTNjeUI1YjNVZ2RHOGdjbVZqWldsMlpTQnlaWEYxWlhOMGN5Qm1iM0lnWm1WbFpHSmhZMnNzSUdOdmJYQmhibmtnYVc1bWIzSnRZWFJwYjI0c0lIQnliMjF2ZEdsdmJtRnNJR2x1Wm05eWJXRjBhVzl1TENCamIyMXdZVzU1SUdGc1pYSjBjeXdnWTI5MWNHOXVjeXdnWkdselkyOTFiblJ6SUdGdVpDQnZkR2hsY2lCdWIzUnBabWxqWVhScGIyNXpJSFJ2SUhsdmRYSWdaVzFoYVd3Z1lXUmtjbVZ6Y3lCaGJtUXZiM0lnWTJWc2JIVnNZWElnY0dodmJtVWdiM0lnWkdWMmFXTmxMaUJaYjNVZ2RXNWtaWEp6ZEdGdVpDQmhibVFnWVdkeVpXVWdkR2hoZENCMGFHVWdVMlZ5ZG1salpTQnBjeUJ3Y205MmFXUmxaQ0FtY1hWdmREdEJVeTFKVXlaeGRXOTBPeUJoYm1RZ2RHaGhkQ0IzWlNCaGMzTjFiV1VnYm04Z2NtVnpjRzl1YzJsaWFXeHBkSGtnWm05eUlIUm9aU0IwYVcxbGJHbHVaWE56TENCa1pXeGxkR2x2Yml3Z2JXbHpMV1JsYkdsMlpYSjVJRzl5SUdaaGFXeDFjbVVnZEc4Z2MzUnZjbVVnWVc1NUlIVnpaWElnWTI5dGJYVnVhV05oZEdsdmJuTWdiM0lnY0dWeWMyOXVZV3hwZW1GMGFXOXVJSE5sZEhScGJtZHpMand2Y0Q0S0NqeHdQbGx2ZFNCaGNtVWdjbVZ6Y0c5dWMybGliR1VnWm05eUlHOWlkR0ZwYm1sdVp5QmhZMk5sYzNNZ2RHOGdkR2hsSUZObGNuWnBZMlVnWVc1a0lIUm9ZWFFnWVdOalpYTnpJRzFoZVNCcGJuWnZiSFpsSUhSb2FYSmtJSEJoY25SNUlHWmxaWE1nS0hOMVkyZ2dZWE1nVTAxVElIUmxlSFFnYldWemMyRm5aWE1zSUVsdWRHVnlibVYwSUhObGNuWnBZMlVnY0hKdmRtbGtaWElnYjNJZ1kyVnNiSFZzWVhJZ1lXbHlkR2x0WlNCamFHRnlaMlZ6S1M0Z1dXOTFJR0Z5WlNCeVpYTndiMjV6YVdKc1pTQm1iM0lnZEdodmMyVWdabVZsY3l3Z2FXNWpiSFZrYVc1bklIUm9iM05sSUdabFpYTWdZWE56YjJOcFlYUmxaQ0IzYVhSb0lIUm9aU0JrYVhOd2JHRjVJRzl5SUdSbGJHbDJaWEo1SUc5bUlHVmhZMmdnVTAxVElIUmxlSFFnYldWemMyRm5aU0J6Wlc1MElIUnZJSGx2ZFNCaWVTQjFjeTRnU1c0Z1lXUmthWFJwYjI0c0lIbHZkU0J0ZFhOMElIQnliM1pwWkdVZ1lXNWtJR0Z5WlNCeVpYTndiMjV6YVdKc1pTQm1iM0lnWVd4c0lHVnhkV2x3YldWdWRDQnVaV05sYzNOaGNua2dkRzhnWVdOalpYTnpJSFJvWlNCVFpYSjJhV05sSUdGdVpDQnlaV05sYVhabElIUm9aU0JUVFZNZ2RHVjRkQ0J0WlhOellXZGxjeTRnVjJVZ1pHOGdibTkwSUdOb1lYSm5aU0JoYm5rZ1ptVmxjeUJtYjNJZ1pHVnNhWFpsY25rZ2IyWWdaVzFoYVd3Z2IzSWdVMDFUTGlCVWFHbHpJR2x6SUdFZ1puSmxaU0J6WlhKMmFXTmxJSEJ5YjNacFpHVmtJR0o1SUhWekxpQkliM2RsZG1WeUxDQndiR1ZoYzJVZ1kyaGxZMnNnZDJsMGFDQjViM1Z5SUdsdWRHVnlibVYwSUhObGNuWnBZMlVnY0hKdmRtbGtaWElnWVc1a0lHTmxiR3gxYkdGeUlHTmhjbkpwWlhJZ1ptOXlJR0Z1ZVNCamFHRnlaMlZ6SUhSb1lYUWdiV0Y1SUdsdVkzVnlJR0Z6SUdFZ2NtVnpkV3gwSUdaeWIyMGdjbVZqWldsMmFXNW5JR1Z0WVdsc0lHRnVaQ0JUVFZNZ2RHVjRkQ0J0WlhOellXZGxjeUIwYUdGMElIZGxJR1JsYkdsMlpYSWdkWEJ2YmlCNWIzVnlJRzl3ZEMxcGJpQmhibVFnY21WbmFYTjBjbUYwYVc5dUlIZHBkR2dnYjNWeUlHVnRZV2xzSUdGdVpDQlRUVk1nYzJWeWRtbGpaWE11SUZsdmRTQmpZVzRnWTJGdVkyVnNJR0YwSUdGdWVTQjBhVzFsTGlCS2RYTjBJSFJsZUhRZ0puRjFiM1E3VTFSUFVDWnhkVzkwT3lCMGJ5WnVZbk53T3p4b2FXZG9iR2xuYUhRZ1kyeGhjM005SW1OdmJYQmhibmxUVFZOUWFHOXVaVlZ3WkdGMFpTSStiblZzYkR3dmFHbG5hR3hwWjJoMFBpNGdRV1owWlhJZ2VXOTFJSE5sYm1RZ2RHaGxJRk5OVXlCdFpYTnpZV2RsSUNaeGRXOTBPMU5VVDFBbWNYVnZkRHNnZEc4Z2RYTXNJSGRsSUhkcGJHd2djMlZ1WkNCNWIzVWdZVzRnVTAxVElHMWxjM05oWjJVZ2RHOGdZMjl1Wm1seWJTQjBhR0YwSUhsdmRTQm9ZWFpsSUdKbFpXNGdkVzV6ZFdKelkzSnBZbVZrTGlCQlpuUmxjaUIwYUdsekxDQjViM1VnZDJsc2JDQnVieUJzYjI1blpYSWdjbVZqWldsMlpTQlRUVk1nYldWemMyRm5aWE1nWm5KdmJTQjFjeTQ4TDNBK0NnbzhjRDQ4YzNSeWIyNW5QbGxQVlZJZ1VrVkhTVk5VVWtGVVNVOU9JRTlDVEVsSFFWUkpUMDVUUEM5emRISnZibWMrUEM5d1Bnb0tQSEErU1c0Z1kyOXVjMmxrWlhKaGRHbHZiaUJ2WmlCNWIzVnlJSFZ6WlNCdlppQjBhR1VnVTJWeWRtbGpaU3dnZVc5MUlHRm5jbVZsSUhSdk9qd3ZjRDRLQ2p4dmJENEtDVHhzYVQ1d2NtOTJhV1JsSUhSeWRXVXNJR0ZqWTNWeVlYUmxMQ0JqZFhKeVpXNTBJR0Z1WkNCamIyMXdiR1YwWlNCcGJtWnZjbTFoZEdsdmJpQmhZbTkxZENCNWIzVnljMlZzWmlCaGN5QndjbTl0Y0hSbFpDQmllU0IwYUdVZ1UyVnlkbWxqWlNZak16azdjeUJ5WldkcGMzUnlZWFJwYjI0Z1ptOXliU0FvYzNWamFDQnBibVp2Y20xaGRHbHZiaUJpWldsdVp5QjBhR1VnSm5GMWIzUTdVbVZuYVhOMGNtRjBhVzl1SUVSaGRHRW1jWFZ2ZERzcElHRnVaRHd2YkdrK0NnazhiR2srYldGcGJuUmhhVzRnWVc1a0lIQnliMjF3ZEd4NUlIVndaR0YwWlNCMGFHVWdVbVZuYVhOMGNtRjBhVzl1SUVSaGRHRWdkRzhnYTJWbGNDQnBkQ0IwY25WbExDQmhZMk4xY21GMFpTd2dZM1Z5Y21WdWRDQmhibVFnWTI5dGNHeGxkR1V1SUVsbUlIbHZkU0J3Y205MmFXUmxJR0Z1ZVNCcGJtWnZjbTFoZEdsdmJpQjBhR0YwSUdseklIVnVkSEoxWlN3Z2FXNWhZMk4xY21GMFpTd2dibTkwSUdOMWNuSmxiblFnYjNJZ2FXNWpiMjF3YkdWMFpTd2diM0lnZDJVZ2FHRjJaU0J5WldGemIyNWhZbXhsSUdkeWIzVnVaSE1nZEc4Z2MzVnpjR1ZqZENCMGFHRjBJSE4xWTJnZ2FXNW1iM0p0WVhScGIyNGdhWE1nZFc1MGNuVmxMQ0JwYm1GalkzVnlZWFJsTENCdWIzUWdZM1Z5Y21WdWRDQnZjaUJwYm1OdmJYQnNaWFJsTENCM1pTQm9ZWFpsSUhSb1pTQnlhV2RvZENCMGJ5QnpkWE53Wlc1a0lHOXlJRHh6ZEhKdmJtYytQSE53WVc0Z2MzUjViR1U5SW1OdmJHOXlPaU5HUmpBd01EQTdJajUwWlhKdGFXNWhkR1VnZVc5MWNpQmhZMk52ZFc1MEwzQnliMlpwYkdVZ1lXNWtJSEpsWm5WelpTQmhibmtnWVc1a0lHRnNiQ0JqZFhKeVpXNTBJRzl5SUdaMWRIVnlaU0IxYzJVZ2IyWWdkR2hsSUZObGNuWnBZMlVnS0c5eUlHRnVlU0J3YjNKMGFXOXVJSFJvWlhKbGIyWXBMand2YzNCaGJqNDhMM04wY205dVp6NDhMMnhwUGdvOEwyOXNQZ29LUEhBK0ptNWljM0E3UEM5d1BnbzhhR2xuYUd4cFoyaDBJR05zWVhOelBTSmpiMjF3WVc1NVRtRnRaVlZ3WkdGMFpTSStVbVZ1ZDJsamF5QkZkbUZ1Y3lBbVlXMXdPeUJCYzNOdlkybGhkR1Z6UEM5b2FXZG9iR2xuYUhRK1BHSnlJQzgrQ2p4b2FXZG9iR2xuYUhRZ1kyeGhjM005SW1OdmJYQmhibmxCWkdSeVpYTnpWWEJrWVhSbElqNDFNekU0SUZNdUlFaGhiWEIwYjI0Z1VtUXVJQ3dnUkdGc2JHRnpMQ0JVV0NBM05USXpNand2YUdsbmFHeHBaMmgwUGp4aWNpQXZQZ284YUdsbmFHeHBaMmgwSUdOc1lYTnpQU0pqYjIxd1lXNTVVR2h2Ym1WVmNHUmhkR1VpUGp3dmFHbG5hR3hwWjJoMFBqeGljaUF2UGdvOGFHbG5hR3hwWjJoMElHTnNZWE56UFNKamIyMXdZVzU1UlcxaGFXeFZjR1JoZEdVaVBuSmxibmRwWTJzb1FDbHlaVzUzYVdOclpYWmhibk11WTI5dFBDOW9hV2RvYkdsbmFIUSsiLCJwcml2YWN5IjoiUEhBK1BITjBjbTl1Wno1UVVrbFdRVU5aUEM5emRISnZibWMrUEM5d1Bnb0tQSEErUEhOMGNtOXVaejVVYUdVZ2FXNW1iM0p0WVhScGIyNGdjSEp2ZG1sa1pXUWdaSFZ5YVc1bklIUm9hWE1nY21WbmFYTjBjbUYwYVc5dUlHbHpJR3RsY0hRZ2NISnBkbUYwWlNCaGJtUWdZMjl1Wm1sa1pXNTBhV0ZzTENCaGJtUWdkMmxzYkNCdVpYWmxjaUJpWlNCa2FYTjBjbWxpZFhSbFpDd2dZMjl3YVdWa0xDQnpiMnhrTENCMGNtRmtaV1FnYjNJZ2NHOXpkR1ZrSUdsdUlHRnVlU0IzWVhrc0lITm9ZWEJsSUc5eUlHWnZjbTB1SUZSb2FYTWdhWE1nYjNWeUlHZDFZWEpoYm5SbFpTNDhMM04wY205dVp6NDhMM0ErQ2dvOGNENDhjM1J5YjI1blBrbE9SRVZOVGtsVVdUd3ZjM1J5YjI1blBqd3ZjRDRLQ2p4d1BqeGxiVDVaYjNVZ1lXZHlaV1VnZEc4Z2FXNWtaVzF1YVdaNUlHRnVaQ0JvYjJ4a0lIVnpMQzRnWVc1a0lHbDBjeUJ6ZFdKemFXUnBZWEpwWlhNc0lHRm1abWxzYVdGMFpYTXNJRzltWm1salpYSnpMQ0JoWjJWdWRITXNJR052TFdKeVlXNWtaWEp6SUc5eUlHOTBhR1Z5SUhCaGNuUnVaWEp6TENCaGJtUWdaVzF3Ykc5NVpXVnpMQ0JvWVhKdGJHVnpjeUJtY205dElHRnVlU0JqYkdGcGJTQnZjaUJrWlcxaGJtUXNJR2x1WTJ4MVpHbHVaeUJ5WldGemIyNWhZbXhsSUdGMGRHOXlibVY1Y3lZak16azdJR1psWlhNc0lHMWhaR1VnWW5rZ1lXNTVJSFJvYVhKa0lIQmhjblI1SUdSMVpTQjBieUJ2Y2lCaGNtbHphVzVuSUc5MWRDQnZaaUJEYjI1MFpXNTBJSGx2ZFNCeVpXTmxhWFpsTENCemRXSnRhWFFzSUhKbGNHeDVMQ0J3YjNOMExDQjBjbUZ1YzIxcGRDQnZjaUJ0WVd0bElHRjJZV2xzWVdKc1pTQjBhSEp2ZFdkb0lIUm9aU0JUWlhKMmFXTmxMQ0I1YjNWeUlIVnpaU0J2WmlCMGFHVWdVMlZ5ZG1salpTd2dlVzkxY2lCamIyNXVaV04wYVc5dUlIUnZJSFJvWlNCVFpYSjJhV05sTENCNWIzVnlJSFpwYjJ4aGRHbHZiaUJ2WmlCMGFHVWdWRTlUTENCdmNpQjViM1Z5SUhacGIyeGhkR2x2YmlCdlppQmhibmtnY21sbmFIUnpJRzltSUdGdWIzUm9aWEl1UEM5bGJUNDhMM0ErQ2dvOGNENDhjM1J5YjI1blBrUkpVME5NUVVsTlJWSWdUMFlnVjBGU1VrRk9WRWxGVXp3dmMzUnliMjVuUGp3dmNENEtDanh3UGp4emRISnZibWMrV1U5VklFVllVRkpGVTFOTVdTQlZUa1JGVWxOVVFVNUVJRUZPUkNCQlIxSkZSU0JVU0VGVU9qd3ZjM1J5YjI1blBqd3ZjRDRLQ2p4dmJENEtDVHhzYVQ1WlQxVlNJRlZUUlNCUFJpQlVTRVVnVTBWU1ZrbERSU0JKVXlCQlZDQlpUMVZTSUZOUFRFVWdVa2xUU3k0Z1ZFaEZJRk5GVWxaSlEwVWdTVk1nVUZKUFZrbEVSVVFnVDA0Z1FVNGdKbkYxYjNRN1FWTWdTVk1tY1hWdmREc2dRVTVFSUNaeGRXOTBPMEZUSUVGV1FVbE1RVUpNUlNaeGRXOTBPeUJDUVZOSlV5NGdMQzRnUVU1RUlGVlRMQ0JKVkNZak16azdVeUJEVlZOVVQwMUZVbE1zSUVWWVVGSkZVMU5NV1NCRVNWTkRURUZKVFZNZ1FVeE1JRmRCVWxKQlRsUkpSVk1nVDBZZ1FVNVpJRXRKVGtRc0lGZElSVlJJUlZJZ1JWaFFVa1ZUVXlCUFVpQkpUVkJNU1VWRUxDQkpUa05NVlVSSlRrY3NJRUpWVkNCT1QxUWdURWxOU1ZSRlJDQlVUeUJVU0VVZ1NVMVFURWxGUkNCWFFWSlNRVTVVU1VWVElFOUdJRTFGVWtOSVFVNVVRVUpKVEVsVVdTd2dSa2xVVGtWVFV5QkdUMUlnUVNCUVFWSlVTVU5WVEVGU0lGQlZVbEJQVTBVZ1FVNUVJRTVQVGkxSlRrWlNTVTVIUlUxRlRsUXVQQzlzYVQ0S0NUeHNhVDVOUVV0RlV5Qk9UeUJYUVZKU1FVNVVXU0JVU0VGVUlDaHBLU0JVU0VVZ1UwVlNWa2xEUlNCWFNVeE1JRTFGUlZRZ1dVOVZVaUJTUlZGVlNWSkZUVVZPVkZNc0lDaHBhU2tnVkVoRklGTkZVbFpKUTBVZ1YwbE1UQ0JDUlNCVlRrbE9WRVZTVWxWUVZFVkVMQ0JVU1UxRlRGa3NJRk5GUTFWU1JTd2dUMUlnUlZKU1QxSXRSbEpGUlN3Z0tHbHBhU2tnVkVoRklGSkZVMVZNVkZNZ1ZFaEJWQ0JOUVZrZ1FrVWdUMEpVUVVsT1JVUWdSbEpQVFNCVVNFVWdWVk5GSUU5R0lGUklSU0JUUlZKV1NVTkZJRmRKVEV3Z1FrVWdRVU5EVlZKQlZFVWdUMUlnVWtWTVNVRkNURVVzSUVGT1JDQW9hWFlwSUVGT1dTQkZVbEpQVWxNZ1NVNGdWRWhGSUZOUFJsUlhRVkpGSUZkSlRFd2dRa1VnUTA5U1VrVkRWRVZFTGp3dmJHaytDZ2s4YkdrK1FVNVpJRTFCVkVWU1NVRk1JRVJQVjA1TVQwRkVSVVFnVDFJZ1QxUklSVkpYU1ZORklFOUNWRUZKVGtWRUlGUklVazlWUjBnZ1ZFaEZJRlZUUlNCUFJpQlVTRVVnVTBWU1ZrbERSU0JKVXlCRVQwNUZJRUZVSUZsUFZWSWdUMWRPSUVSSlUwTlNSVlJKVDA0Z1FVNUVJRkpKVTBzZ1FVNUVJRlJJUVZRZ1dVOVZJRmRKVEV3Z1FrVWdVMDlNUlV4WklGSkZVMUJQVGxOSlFreEZJRVpQVWlCQlRsa2dSRUZOUVVkRklGUlBJRmxQVlZJZ1EwOU5VRlZVUlZJZ1UxbFRWRVZOSUU5U0lFeFBVMU1nVDBZZ1JFRlVRU0JVU0VGVUlGSkZVMVZNVkZNZ1JsSlBUU0JVU0VVZ1JFOVhUa3hQUVVRZ1QwWWdRVTVaSUZOVlEwZ2dUVUZVUlZKSlFVd3VQQzlzYVQ0S0NUeHNhVDVPVHlCQlJGWkpRMFVnVDFJZ1NVNUdUMUpOUVZSSlQwNHNJRmRJUlZSSVJWSWdUMUpCVENCUFVpQlhVa2xVVkVWT0xDQlBRbFJCU1U1RlJDQkNXU0JaVDFVZ1JsSlBUU0JQVWlCVVNGSlBWVWRJSUU5U0lFWlNUMDBnVkVoRklGTkZVbFpKUTBVZ1UwaEJURXdnUTFKRlFWUkZJRUZPV1NCWFFWSlNRVTVVV1NCT1QxUWdSVmhRVWtWVFUweFpJRk5VUVZSRlJDQkpUaUJVU0VVZ1ZFOVRMand2YkdrK0Nqd3ZiMncrQ2dvOGNENDhjM1J5YjI1blBreEpUVWxVUVZSSlQwNGdUMFlnVEVsQlFrbE1TVlJaUEM5emRISnZibWMrUEM5d1Bnb0tQSEErV1U5VklFVllVRkpGVTFOTVdTQlZUa1JGVWxOVVFVNUVJRUZPUkNCQlIxSkZSU0JVU0VGVUlFRk9SQ0JUU0VGTVRDQk9UMVFnUWtVZ1RFbEJRa3hGSUVaUFVpQkJUbGtnUkVsU1JVTlVMQ0JKVGtSSlVrVkRWQ3dnU1U1RFNVUkZUbFJCVEN3Z1UxQkZRMGxCVEN3Z1EwOU9VMFZSVlVWT1ZFbEJUQ0JQVWlCRldFVk5VRXhCVWxrZ1JFRk5RVWRGVXl3Z1NVNURURlZFU1U1SElFSlZWQ0JPVDFRZ1RFbE5TVlJGUkNCVVR5d2dSRUZOUVVkRlV5QkdUMUlnVEU5VFV5QlBSaUJRVWs5R1NWUlRMQ0JIVDA5RVYwbE1UQ3dnVlZORkxDQkVRVlJCSUU5U0lFOVVTRVZTSUVsT1ZFRk9SMGxDVEVVZ1RFOVRVMFZUSUNoRlZrVk9JRWxHSUVoQlV5QkNSVVZPSUVGRVZrbFRSVVFnVDBZZ1ZFaEZJRkJQVTFOSlFrbE1TVlJaSUU5R0lGTlZRMGdnUkVGTlFVZEZVeWtzSUZKRlUxVk1WRWxPUnlCR1VrOU5Pand2Y0Q0S0NqeHZiRDRLQ1R4c2FUNVVTRVVnVlZORklFOVNJRlJJUlNCSlRrRkNTVXhKVkZrZ1ZFOGdWVk5GSUZSSVJTQlRSVkpXU1VORk96d3ZiR2srQ2drOGJHaytWRWhGSUVOUFUxUWdUMFlnVUZKUFExVlNSVTFGVGxRZ1QwWWdVMVZDVTFSSlZGVlVSU0JIVDA5RVV5QkJUa1FnVTBWU1ZrbERSVk1nVWtWVFZVeFVTVTVISUVaU1QwMGdRVTVaSUVkUFQwUlRMQ0JFUVZSQkxDQkpUa1pQVWsxQlZFbFBUaUJQVWlCVFJWSldTVU5GVXlCUVZWSkRTRUZUUlVRZ1QxSWdUMEpVUVVsT1JVUWdUMUlnVFVWVFUwRkhSVk1nVWtWRFJVbFdSVVFnVDFJZ1ZGSkJUbE5CUTFSSlQwNVRJRVZPVkVWU1JVUWdTVTVVVHlCVVNGSlBWVWRJSUU5U0lFWlNUMDBnVkVoRklGTkZVbFpKUTBVN1BDOXNhVDRLQ1R4c2FUNVZUa0ZWVkVoUFVrbGFSVVFnUVVORFJWTlRJRlJQSUU5U0lFRk1WRVZTUVZSSlQwNGdUMFlnV1U5VlVpQlVVa0ZPVTAxSlUxTkpUMDVUSUU5U0lFUkJWRUU3UEM5c2FUNEtDVHhzYVQ1VFZFRlVSVTFGVGxSVElFOVNJRU5QVGtSVlExUWdUMFlnUVU1WklGUklTVkpFSUZCQlVsUlpJRTlPSUZSSVJTQlRSVkpXU1VORk95QlBVand2YkdrK0NnazhiR2srUVU1WklFOVVTRVZTSUUxQlZGUkZVaUJTUlV4QlZFbE9SeUJVVHlCVVNFVWdVMFZTVmtsRFJTNDhMMnhwUGdvOEwyOXNQZ29LUEhBK1BIVStRbmtnY21WbmFYTjBaWEpwYm1jZ1lXNWtJSE4xWW5OamNtbGlhVzVuSUhSdklHOTFjaUJsYldGcGJDQmhibVFnVTAxVElITmxjblpwWTJVc0lHSjVJRzl3ZEMxcGJpd2diMjVzYVc1bElISmxaMmx6ZEhKaGRHbHZiaUJ2Y2lCaWVTQm1hV3hzYVc1bklHOTFkQ0JoSUdOaGNtUXNJQ1p4ZFc5ME8zbHZkU0JoWjNKbFpTQjBieUIwYUdWelpTQlVSVkpOVXlCUFJpQlRSVkpXU1VORkpuRjFiM1E3SUdGdVpDQjViM1VnWVdOcmJtOTNiR1ZrWjJVZ1lXNWtJSFZ1WkdWeWMzUmhibVFnZEdobElHRmliM1psSUhSbGNtMXpJRzltSUhObGNuWnBZMlVnYjNWMGJHbHVaV1FnWVc1a0lHUmxkR0ZwYkdWa0lHWnZjaUI1YjNVZ2RHOWtZWGt1UEM5MVBqd3ZjRDRLQ2p4d1BpWnVZbk53T3p3dmNENEtVbVZ1ZDJsamF5QkZkbUZ1Y3lBbVlXMXdPeUJCYzNOdlkybGhkR1Z6UEdKeUlDOCtDalV6TVRnZ1V5NGdTR0Z0Y0hSdmJpQlNaQzRnTENCRVlXeHNZWE1zSUZSWUlEYzFNak15UEdKeUlDOCtDanhpY2lBdlBncHlaVzUzYVdOcktFQXBjbVZ1ZDJsamEyVjJZVzV6TG1OdmJRPT0ifQ==

Terms of Service

Privacy Policy

Core Modal Title

Sorry, no results found

You Might Find These Articles Interesting

T
Please Check Your Email
We Will Be Following Up Shortly
*
*
*