Renwick Evans and Associates
  • Blog Home
  • Categories
    • Startup Launch Guidance
    • Cash Flow, Funding & Capital Strategies
    • Business Operations, challenges & Solutions
    • Merchant Processing & Payments
    • Business Marketing That Works
    • Business Growth & Scaling
    • Business Consulting Insights
    • Compliance & Risk Management
  • Home
March 24.2026
1 Minute Read

Merchant Processing Basics Every Startup Should Understand

Did you know that over 80% of customers prefer businesses that offer digital payment processing options? For startups, effective merchant processing is no longer optional, but a necessity for survival

"Did you know that over 80% of customers prefer businesses that offer digital payment processing options? For startups, effective merchant processing is no longer optional, but a necessity for survival."
Startup founders reviewing payment analytics on a tablet in a modern office - startup merchant processing for startups

Unlocking Merchant Processing for Startups: Surprising Trends and Vital Insights

The landscape for merchant processing for startups is evolving at lightning speed, with consumer expectations for fast, flexible payments at an all-time high. Modern small businesses and startups simply can't afford to stick with cash-only models. In fact, the majority of growth-focused startups now adopt advanced payment solutions—from credit card and debit card processing to mobile payment and payment links—to stay competitive. Offering multiple ways to accept payments not only boosts customer satisfaction, but also supports higher revenue and better cash flow management.

From choosing the right payment processor to understanding how processing fees can affect your bottom line, it’s critical to align your payment infrastructure with startup realities. Today’s best payment process choices are those that address real-world startup pain points—flexibility, integration, scalability, and transparent pricing—while helping you compliantly handle credit card and card payment transactions from anywhere. As the data shows, more startups are putting robust merchant services at the center of their operations to maximize growth from day one.

As you explore the essentials of merchant processing, it's also valuable to understand how building a strong foundation for your small business can impact your payment strategy and overall growth. For practical steps and legal considerations that support your startup’s success, see this guidance for building a strong small business.

What You'll Learn About Merchant Processing for Startups

  • The basics of merchant processing for startups
  • Key payment processing and payment process terms explained
  • How merchant services compare for small business needs
  • Criteria for choosing the right payment processor
  • How to reduce merchant processing fees
  • Key considerations for POS system and card reader selection

The Merchant Processing for Startups Landscape: Why Payment Processing Matters

The Evolving Role of Payment Processing in Small Business Success

For startup owners, getting paid quickly and securely is critical—especially when every sale counts and cash flow is tight. The payment processing industry is witnessing substantial market growth, with recent studies showing the global payment market expanding at a double-digit rate annually. This is fueled by shifting consumer habits, where the vast majority of customers prefer credit card, debit card, card payments, and even digital wallet and mobile payment options over cash. Businesses able to adapt by offering seamless digital payment solutions aren’t just keeping up—they’re gaining a direct competitive edge.

  • Market growth statistics: The rise in contactless payments and e-commerce means your customers expect fast, secure, and diverse payment methods.
  • Shifting consumer habits: From the local coffee shop to e-commerce startups, card payment and mobile payments are now the norm.
  • Competitive advantages: Fast, flexible payment process systems enable you to attract and retain more customers, deliver quicker checkouts, and scale more smoothly with your business needs.
Customer completing a card payment at a wireless POS terminal in a vibrant small business - payment processing for startups

What is Merchant Processing for Startups?

Defining Merchant Processing, Payment Processing, and Payment Solutions

In its simplest terms, merchant processing refers to the technology and merchant services that enable startups and small businesses to accept credit card, debit card, and digital payments. This can include accepting payments through a POS system in-store, handling online transactions, or offering quick payment via payment links. A payment processor handles the movement of funds from the customer’s card payment method to your business bank account, making it possible for startups to manage transactions reliably and securely. In addition, a broad set of payment solutions—from card readers to payment gateways—ensure your business can stay up-to-date with how today’s customers prefer to pay.

How a Payment Processor Works: The Payment Process Explained

The core of payment processing involves a network of systems that authenticate the buyer’s payment method, check the availability of funds or credit, and transfer the payment to your merchant account—all within seconds. Here’s how it breaks down: When a customer swipes, taps, or enters their card details, the payment gateway encrypts the sensitive card data and transmits it securely. The payment processor then validates and routes the payment to your bank, while a linked POS system or card reader confirms the transaction in real time. For startups, making sure these moving parts work together smoothly is crucial for both customer trust and business operations.

  • The role of payment processors, payment gateways, and POS systems

Key Components of Payment Processing for Startups

Merchant Services: What Every Small Business Must Know

Merchant services are more than just a means to accept card payments. A trusted provider will offer integrated solutions for in-person, online, and mobile commerce, along with reporting tools, security features, and dedicated support. For new business owners, evaluating merchant services includes scrutinizing contract terms, transaction fee structures, settlement times, and the ability to connect with your existing sales channels and tech stack. Forward-thinking merchant service providers also offer value-added services such as recurring billing, robust analytics dashboards, and instant currency conversions—giving your startup flexibility and scalability from day one.

Understanding Payment Processors, Credit Card Transactions, and Card Payments

At the heart of any good payment solution is the payment processor, which serves as the bridge between your business, your customer, and the financial institutions that make transactions possible. Whether you’re using an in-store terminal or an online checkout, the credit card and debit card details must be transmitted and approved through secure networks to prevent fraud and data theft. Features to consider include support for multiple card networks (like Visa, Mastercard, AMEX), integration capabilities for your point-of-sale (POS) or e-commerce platform, and rapid settlement of funds into your account, so your cash flow stays healthy. Modern card readers and POS systems now support contactless payments, chip cards, and even digital wallets (such as Apple Pay and Google Pay).

The Importance of Payment Gateways, POS System, and Card Reader Choices

Choosing the right payment gateway and POS system is fundamental for delivering a smooth customer experience. A payment gateway acts as your digital checkpoint, authorizing payments in real time and enabling you to compete with the biggest retail players. Meanwhile, the selection of card readers matters for in-person payments—modern devices allow for tap, swipe, and chip transactions. For a startup, ensuring these systems work together can mean fewer failed transactions, less downtime, and happy returning customers.

  • Integration with mobile payment and payment links
Using a contactless card at a modern POS system—card reader for startups in a trendy coffee shop

How the Payment Process Works: Step-by-Step for Startups

  1. Initiating a sale: The customer pays by card or mobile device, using a card reader, POS system, or online form.
  2. Role of the POS system/card reader: Payment details are entered or captured by hardware/software at the point of sale.
  3. Authorization through payment gateways: The payment gateway encrypts and transmits the transaction for approval by the card networks and issuing bank.
  4. Transfer via payment processor: The payment processor manages fund movement and oversees transaction security.
  5. Funds clearing and settlement: Cleared funds are deposited into the startup’s merchant or business bank account.
Comparison of Payment Processing Steps and Fees for Startups
Step Description Typical Fees
Payment Initiation Customer initiates payment by card, mobile, or online 0%
Authorization (POS/Gateway) Securely transmits and checks transaction Included in processing fee
Processing Funds routed via processor for settlement 1.5%–3.5% (per transaction)
Settlement Funds move into business account (daily or 2-3 days) None, or nominal account fee

Choosing the Right Payment Processors and Merchant Services for Your Small Business

Top Features to Seek in a Startup Payment Solution

Not all payment solutions are equal—especially for startups seeking rapid growth and flexibility. As you compare payment processors and merchant service providers, look for features such as transparent pricing (no surprise transaction fees or hidden charges), robust PCI compliance, support for both credit card and mobile payment acceptance, integration with your sales and accounting systems, customizable POS system options, and responsive customer support. Seamless setup and scalability are vital—look for providers that allow you to adjust features as your business grows or pivots.

Comparing Leading Payment Processors: Pricing, Scalability, and Support

Industry leaders like Stripe, Square, and PayPal have built reputations for startup-friendly solutions. Stripe is known for its developer-friendly APIs and global reach; Square shines with seamless in-person POS hardware and transparent fees; while PayPal excels with e-commerce checkout and invoicing. As you weigh options, compare not just the published per-transaction rates and monthly fees, but also the support level, settlement speed, availability of payment links, and integration with your existing POS or online shopping cart. Customer reviews can also provide insight into real-life reliability and issue resolution timeframes.

"Selecting the right payment processor can mean the difference between seamless sales and lost revenue for your startup."
Entrepreneurs comparing payment processor dashboards and charts - choosing the right payment processor for startups

Demo: Comparing User Experience of Popular Startup Payment Processors

Understanding Merchant Processing Fees for Startups

Breaking Down Processing Fees: Credit Card, POS Systems, and Payment Solutions

Merchant processing fees typically include a mix of per-transaction and monthly charges. Standard transaction fees for credit card payments range between 1.5%–3.5%, depending on your provider and card type. POS systems and hardware may carry upfront or rental fees, and online payment solutions sometimes have extra charges for invoicing or integration features. It’s also common to encounter incidental fees for chargebacks, refunds, or special payment methods like digital wallets. As you compare offers, pay special attention to fine print on monthly minimums, bundled service pricing, and possible surcharges for AMEX or international transactions.

Typical Processing Fee Structure by Provider Type
Provider Type Per Transaction Fee Monthly Fee Other Fees
Traditional Bank Processor 1.8%–3.5% $10–$50 PCI, batch, statement
Modern Payment Tech (Stripe, Square, PayPal) 2.6% + 10¢ $0–$30 Chargeback, hardware rental
POS System Bundle 1.5%–2.9% $0–$75 Hardware lease, optional add-ons

Strategies to Minimize Merchant Processing Fees for Small Business

Smart startups actively seek to reduce merchant processing fees to protect profit margins. Start by negotiating rates with your payment processor, especially as your transaction volume grows. Watch for hidden processing charges—including monthly minimums or ‘non-qualified’ card surcharges—and ask for these to be waived where possible. Exploring merchant services that bundle payment gateway, POS system, and card reader fees can simplify your payment process and reduce total costs. Routinely review merchant statements for errors and consider switching when better value is available.

  • Negotiating rates
  • Avoiding hidden charges
  • Bundling with merchant services

Essential Payment Solutions for Startups: From Mobile Payment to Payment Links

Integrating Mobile Payments and Payment Links to Expand Customer Options

Mobile payment and payment links are among the fastest-growing startup payment trends. Accepting mobile payments allows customers to use their smartphones, smartwatches, or digital wallet apps like Apple Pay and Google Pay to quickly make a purchase at the point of sale. Payment links enable you to send a secure, one-time checkout URL via text or email, making it easier for customers to pay remotely—ideal for service-based startups, event registration, or social commerce. Both options dramatically expand how (and where) your customers can pay, fueling higher conversion and customer convenience.

Leveraging Card Readers and POS Systems for Modern Businesses

Modern card readers and POS systems play a pivotal role in delivering seamless payment solutions. Setting up your POS involves selecting secure, up-to-date hardware that supports tap (contactless), chip, and swipe options. Many providers offer integration with inventory management, accounting, and analytics tools—making business operations smarter and more efficient. Key best practices include consistently updating software, training your staff on device usage, and prioritizing swift, friendly service at checkout.

  1. Best practices for setup: Use PCI-compliant hardware/software, conduct regular device updates, and test transactions across all payment methods.
  2. Security considerations: Encrypt cardholder data, enable two-factor device authentication, and physically secure POS hardware to prevent tampering.
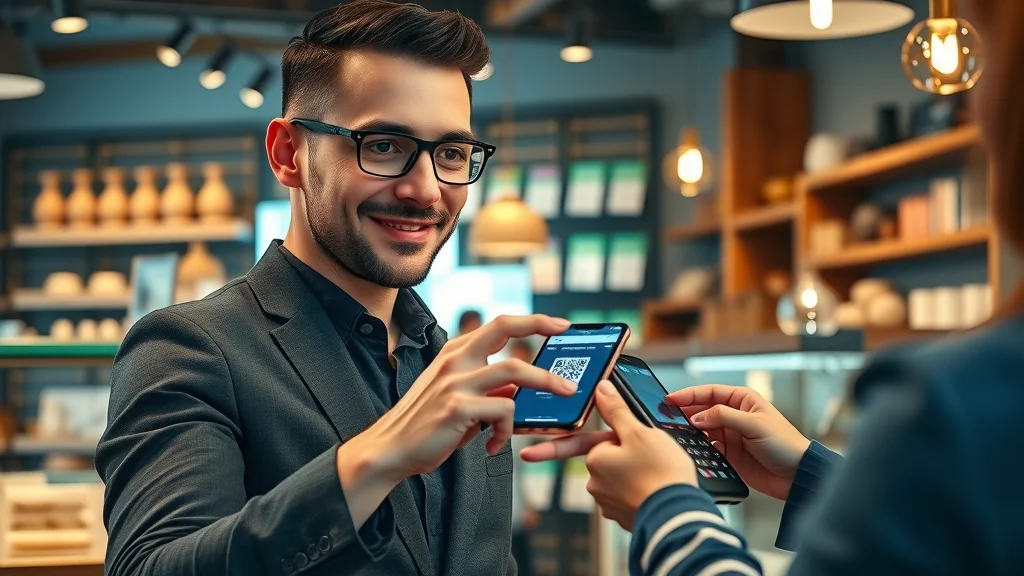
Business owner accepting payment with smartphone QR code—mobile payment solution for startups

How-To: Setting Up Your POS System and Accepting Card Payments

Merchant Processing for Startups: Security, Compliance, and Reducing Risk

PCI Compliance: Why It’s Critical for Small Business

Security and compliance are non-negotiables in payment processing. PCI-DSS (Payment Card Industry Data Security Standard) compliance ensures that your business follows strict data security protocols when handling credit card information—helping prevent breaches and heavy fines. Even the best payment solution is meaningless if transactions aren’t secure. Top merchant services automate PCI compliance checks, update encryption standards, and supply your staff with education, so your reputation and customer trust remain protected as you scale.

Fraud Prevention: Tools Provided by Payment Solution Providers

Leading payment processors equip startups with crucial fraud prevention tools—protecting both you and your customers. This includes two-factor authentication for login and transactions, real-time monitoring for unusual activity, AI-driven anomaly detection, and instant alerts for suspicious transactions. Providers may also integrate with chargeback protection, encrypted payment gateways, and customer notification systems. Staying proactive on fraud prevention is not just about safety—it’s about preserving your brand’s credibility and long-term customer relationships.

  • Two-factor authentication
  • Real-time transaction monitoring

Secure server environment with IT professional monitoring payment transactions - payment processing security for startups

Frequently Asked Questions: Merchant Processing for Startups

What is the best payment processor for a small business?

The best payment processor for a small business depends on transaction volume, business type, and required features. Leading providers include Stripe, Square, and PayPal, each offering robust payment solutions tailored to various startup needs.

Who pays the 3% credit card fee?

Typically, the business pays the 3% credit card processing fee, though some businesses opt to pass this cost on to customers or absorb it as part of operating expenses.

What is the best way to accept payments for a small business?

The best way is through an integrated payment processor that supports credit card, mobile payment, and online payment links, ensuring more flexibility and faster checkouts.

What is the average merchant processing fee?

The average merchant processing fee ranges between 1.5% and 3.5% per transaction, depending on the payment processor, card type, and sales channels used.

Key Takeaways: Merchant Processing for Startups

  • Merchant processing for startups is essential for sales growth
  • Choosing the right payment processor impacts profitability
  • Understanding payment processing fees helps control costs
  • Adopting modern payment solutions boosts customer satisfaction

Ready for Startup Success? Optimize Your Merchant Processing Today

"Set your startup apart with seamless payments and trusted merchant services—get started now!"

Call for a free consultation at 214-854-9931

Don’t let payment processing hold you back—take action today to prepare your startup for growth and customer satisfaction.

As you move forward with optimizing your startup’s payment systems, remember that a strong business foundation is just as important as seamless transactions. Exploring broader strategies for building a resilient small business can help you navigate challenges beyond payments, from legal compliance to operational best practices. For a comprehensive look at how to strengthen your business from the ground up, including expert tips and actionable guidance, visit our resource on building a strong small business. Taking these next steps will empower you to create a thriving, future-ready company that’s equipped for sustainable growth.
Merchant Processing & Payments

Write A Comment

*
*
Please complete the captcha to submit your comment.
Related Posts All Posts
09.16.2026

Payment Processing for Subscription-Based Startups

As you consider the essential components of subscription payment processing, it's also valuable to explore how recurring billing automation can further streamline your operations and reduce manual errors. For a practical breakdown of recurring billing best practices and actionable setup tips, check out this guide on optimizing recurring billing for startups. If you’re ready to take your startup’s payment infrastructure to the next level, it’s worth broadening your perspective beyond just payment processing. Building a resilient subscription business also means understanding the legal, operational, and strategic foundations that support long-term growth. For a comprehensive look at how to strengthen your small business from the ground up—including legal considerations and sustainable business practices—explore this in-depth resource on building a strong small business. By combining robust payment systems with holistic business strategies, you’ll be well-positioned to thrive in the competitive subscription economy.

09.09.2026

Best Merchant Services for Retail Startups

Did you know that 82% of retail startups fail without reliable payment processing? It’s true: having the right retail merchant services isn’t just nice to have—it’s mission critical for every budding retail business. This guide cuts through the noise to reveal how the right merchant service companies can unlock your startup’s growth, prevent payment pitfalls, and transform your retail store into a customer favorite. Revealing the Real Impact of Retail Merchant Services on Startup Growth As a retail startup, your path to profitability hinges on seamless payment processing solutions and the ability to quickly accept card payments, whether from credit cards, debit cards, or digital wallets. Without a trusted merchant service provider, cash flow can stall, customer trust can erode, and you risk falling behind competitors who streamline every transaction. Retail merchant services provide the lifeblood for your business, handling everything from card machine setup to chargeback protection, and direct connections to financial networks for instant day settlement. The right services company doesn’t just move money—they move your business forward. Success in the retail world means more than stocking shelves and managing staff. With over 60% of transactions now cashless in modern retail businesses, your ability to accept card payments is directly tied to sales growth, better customer experiences, and repeat purchases. Reliable payment processing opens doors for omnichannel sales, from in-store POS systems to online and mobile checkouts. In this article, we'll unpack why payment service providers are essential for startups, how to compare merchant services, and which solutions offer the competitive edge needed in a crowded retail marketplace. When evaluating merchant service providers, it's also helpful to understand how payment processing fits into the broader foundation of your business. For a deeper dive into building a resilient small business from the ground up, including legal and operational essentials, explore this comprehensive guide to small business fundamentals. A Startling Fact: 82% of Retail Startups Fail Without Reliable Payment Processing That’s right: data shows failure to secure dependable, secure merchant service relationships and easy card payment procedures puts startups at a major disadvantage. After all, friction at the checkout often leads to lost sales—and no small business can afford that. What You'll Learn About Retail Merchant Services for Small Businesses Key features of the best retail merchant services How merchant services impact retail startup success Industry-leading merchant service companies and processing solutions Retail merchant service costs and payment processing considerations Understanding Retail Merchant Services and Payment Processing Solutions What Are Retail Merchant Services? Retail merchant services refer to the comprehensive suite of payment processing tools and services that empower small businesses to accept and manage payments made with credit cards, debit cards, and other modern card payment methods. These services span everything from opening a merchant account (which functions as a temporary holding bank account) to supporting POS systems, online checkout integration, fraud management, and automated reporting. Unlike ordinary bank accounts, merchant services are tailored for fast-moving retail selling—giving you the agility to handle in-person, mobile, or online transactions with equal confidence. For startups in particular, choosing the right retail merchant service provider can make the crucial difference between seamless sales and disruptive headaches. Reliable merchant service companies streamline the way your retail business processes payments, minimize cash flow delays, and safeguard against card fraud or chargebacks. They act as trusted partners, not just vendors, giving you access to state-of-the-art card machines, virtual terminal options, and transparent processing costs tailored to your unique growth stage. How Merchant Service Companies Work for Small Business Retailers A merchant services company acts as the engine behind every successful card transaction. They enable your retail merchant setup to accept card payments by connecting your POS system or card reader to global financial networks. When a customer pays with a credit card or debit card, your merchant account receives the payment, verifies the transaction, and deposits the funds safely—typically with next-day or even same-day settlement for robust cash flow. The best services provide dashboard access for tracking sales, real-time alerts, and easy access to technical or customer support. Small business retailers benefit from merchant service companies that offer flexible contract terms (monthly or pay-as-you-go), transparent fee structures, and advanced fraud detection. Look for providers that integrate with a wide range of hardware—from advanced POS terminals to smartphone-compatible dongles—and who facilitate both physical and e-commerce transactions. This not only caters to changing customer behaviors but also ensures your retail business won’t be left behind by new payment technologies. Role of Credit Card and Card Machines in Merchant Services Card machines and POS terminals are the critical hardware components that bring merchant services to life in any retail store. These devices authenticate, process, and encrypt card payments—allowing fast, secure, and reliable checkouts whether via chip, swipe, tap, or digital wallets. Modern merchant services companies often provide or lease these machines as part of their overall service suite, ensuring compatibility with multiple card types and payment apps. Having the latest card machine or virtual terminal boosts your brand’s professionalism and customer trust. Speedy card processing means shorter lines and fewer abandoned baskets—a must for busy retail environments. On top of this, advanced POS systems can sync with inventory management, track customer preferences, and produce detailed sales reports—helping startups turn payment data into actionable business insights. Top Features of the Best Retail Merchant Services Integrated payment processing solutions Seamless credit card and debit card acceptance POS card machines and terminals Competitive pricing structures for small business Robust fraud and chargeback management The best retail merchant services go beyond simple payment acceptance. Integrated processing solutions ensure your operation can handle all forms of card payments—chip, magstripe, contactless, and even new methods like QR codes or mobile wallets. Seamless integration into your POS system reduces training time and the risk of manual entry errors. Competitive pricing—typically ranging from 1. 5% to 3. 5% on card transactions—is vital for protecting margins, while robust chargeback management provisions shield your business from common pitfalls that disrupt cash flow. When choosing a service provider, ensure they offer fraud detection tools, next-day settlements, online reporting, and on-demand customer service. Whether you’re processing a few card transactions per day or managing multi-location sales, these features will help your startup operate efficiently and confidently in a fast-moving retail landscape. Comparison Table: Leading Retail Merchant Service Companies Merchant Service Company Key Features Costs & Fees Contract Terms Processing Speed Best For Square Free POS, card reader, online invoicing, real-time reporting 2.6% + 10¢ per transaction No long-term contract Next day Retail popups & startups Clover Customizable POS, inventory tools, contactless payments 2.3% + 10¢ per transaction Monthly contracts Same or next day Growing small businesses Helcim Transparent pricing, virtual terminal, advanced security Interchange + 0.3% + 8¢ No contract 1-2 days Cost-conscious startups Stripe API integration, online/offline payments, fraud detection 2.9% + 30¢ per online transaction Month-to-month 2 days Omnichannel retailers PayPal Zettle Simple POS, card reader, eCommerce sync 2.29% per transaction No contract Next day Side businesses & mobile sellers Best Retail Merchant Services for Startups: Detailed Reviews Review: [Top Merchant Service Company #1] Square is a pioneer in retail payment processing solutions, renowned for intuitive design, transparent pricing, and no-hassle contracts. Their free POS system, coupled with an affordable card reader, allows startups to accept credit and debit card payments anywhere—whether in-store, curbside, or at pop-up events. Square stands out for its crystal-clear 2. 6% + 10¢ per transaction fee—no hidden costs or monthly minimums. With seamless integration into modern retail environments, Square helps small businesses thrive by ensuring reliable cash flow, same-day settlements, and 24/7 support. Comprehensive sales and customer insights are only a tap away in the Square Dashboard, giving startup retailers a powerful advantage in a competitive market. Alongside brick-and-mortar capability, Square supports online checkouts and digital wallet payments, allowing retailers to meet customers where they shop. With built-in chargeback protection and fraud detection, it keeps your business secure as you scale. For startups needing adaptability, speed, and transparent service, Square is among the best in the industry. Review: [Top Merchant Service Company #2] Clover is a favorite among retail merchants looking for a customizable and scalable POS ecosystem. Its modular system—featuring everything from sleek card machines and contactless card readers to inventory management tools—caters to both new startups and growing businesses. Clover’s transaction fees are competitive (2. 3% + 10¢), and the platform offers monthly contract flexibility, important for startups wary of long-term commitments. What sets Clover apart is its vast app marketplace, empowering retailers to expand as their needs evolve—from customer loyalty programs to online store integration. With robust support for debit and credit card acceptance, quick day settlement, and superior chargeback resolution, Clover is ideal for startups seeking growth potential. Their hardware options cover everything from stationary POS terminals to mobile card readers for smartphone or tablet use—all backed by industry-standard security and PCI compliance. Review: [Top Merchant Service Company #3] Helcim is best known for its radically transparent, low-cost pricing—making it a top pick for cost-conscious retail startups. Helcim uses an interchange-plus structure, with rates as low as interchange + 0. 3% + 8¢ per transaction, passing savings directly to retailers as they grow. Their POS system is user-friendly and versatile, supporting both brick-and-mortar and online sales, plus a powerful virtual terminal for phone or mail orders. Helcim includes free PCI compliance and advanced security tools to protect against fraud and chargebacks, reducing risk for small businesses. Fast processing (1-2 day settlement), real-time reporting, and no long-term contracts help startups stay agile while maintaining healthy cash flow. Helcim’s strong focus on customer support and resource guides is an additional plus for first-time business owners navigating retail payment systems for the very first time. How to Choose the Right Retail Merchant Services for Your Startup Assessing processing solutions and hardware needs Comparing credit card transaction fees Evaluating customer support and merchant account services Considering setup costs and contract flexibility Choosing the optimal merchant services company starts with a frank assessment of your retail operation’s scale, expected transaction volume, and technical requirements. New startups may want low-cost, plug-and-play solutions like Square or PayPal Zettle, while ambitious businesses gearing up for rapid growth might benefit from an all-in-one system like Clover or customizable solutions like Helcim. Carefully compare credit card and debit card fees—not just per-transaction charges, but also hidden costs like PCI compliance, service provider support, chargeback fees, and hardware rentals. Pay special attention to setup timelines, ease of onboarding, contract flexibility, and whether the provider offers responsive customer support via multiple channels. Look for transparent terms, quick day settlement for consistent cash flow, and integration with online platforms for omnichannel sales. Startups should choose a merchant account that scales with the business and won’t lock them into restrictive or costly arrangements. Video Guide: Setting Up Retail Merchant Services for Small Businesses Expert Quote: On the Value of Merchant Services for Retail Small Business "Choosing the right retail merchant service can mean the difference between thriving and surviving for startups. Reliable payment processing is your lifeline to steady revenue." — Industry Payment Professional People Also Ask: Frequently Searched Questions About Retail Merchant Services Who owns retail merchant services? Answer: Retail merchant services can be owned by independent companies, financial institutions, or specialized payment processors offering merchant accounts and processing solutions to retailers. What does a retail merchant do? Answer: A retail merchant manages the sale of goods and services to customers, handling payments, inventory, and customer service—crucially relying on merchant services for secure credit card and digital payment processing. How much does retail merchant services charge? Answer: Costs vary by merchant service company but typically include transaction fees, monthly service charges, and equipment costs. Fees for retail merchant services generally range from 1. 5% to 3. 5% per credit card transaction. What's the cheapest way to accept credit cards? Answer: The least expensive option is often a flat-rate processing solution with no long-term contract or monthly minimums. Many retail merchant service providers now offer transparent pricing for small business startups. Video Tutorial: Comparing Card Machines and Payment Processing Solutions Pros and Cons List: Retail Merchant Services for Startups Pros: Fast payments, increased sales, improved customer trust, flexible payment processing. Cons: Monthly and transaction fees, contract terms, potential chargebacks. FAQs: Quick Answers to Retail Merchant Services Queries What is the difference between retail merchant services and traditional bank accounts? Retail merchant services provide specialized payment processing, chargeback protection, and point-of-sale integrations—unlike standard bank accounts, which do not process customer card transactions or offer POS solutions. Are retail merchant services necessary for online retail businesses? Yes—any business selling online needs a merchant account or payment services company to securely process credit card and digital wallet payments. Can startups negotiate payment processing fees with merchant service companies? In many cases, yes—startups with higher volume or growth potential can often negotiate lower rates or transaction fees with providers. What is PCI compliance and why does it matter for small business retailers? PCI compliance ensures your payment system securely handles cardholder data, protecting against fraud and data breaches—a prerequisite for any retail merchant service provider. Key Takeaways: Finding the Best Retail Merchant Services for Your Business Choosing optimal retail merchant services requires comparing features, pricing, and support. Reliable payment processing is essential for retail startup growth and customer trust. Startups benefit from transparent, scalable, and secure merchant service solutions. Ready to Grow Your Startup? Call for a Free Consultation at 214-854-9931 With the right retail merchant services partner, your startup can thrive—unlocking faster sales, happier customers, and steady growth in a dynamic retail landscape. As you continue to refine your retail startup’s payment infrastructure, remember that merchant services are just one pillar of a resilient business. For a holistic approach to building a strong foundation—covering legal, operational, and strategic considerations—take the next step by reviewing expert guidance for small business success. This resource offers actionable insights that go beyond payments, helping you future-proof your venture and navigate the challenges of growth with confidence. Investing in both robust merchant services and sound business practices will position your startup for long-term achievement in today’s competitive retail landscape.

09.02.2026

How Chargebacks Hurt Startup Merchant Accounts

Did you know over 80% of startups are hit with chargebacks in their first year—risking not only their revenue but their very survival? While many founders focus on growth and customer acquisition, few realize just how devastating chargebacks can be to young businesses. In this article, you’ll learn how startup chargeback prevention can save your company from costly pitfalls, secure your merchant account, and ultimately protect your business as you scale. A Startling Look at Startup Chargeback Prevention and Its Impact on Startup Merchant Accounts Unveiling a surprising statistic: Over 80% of startups experience chargebacks within their first year. Why startup chargeback prevention is more than just a finance issue—it's a survival strategy. “Chargebacks aren’t just the cost of doing business—they can be the difference between scaling or shuttering your startup.” What You'll Learn About Startup Chargeback Prevention How chargebacks can undermine your startup's financial stability. Comprehensive startup chargeback prevention techniques. Key steps to protect your merchant account from chargeback fraud. Role of payment processors and customer service in friendly fraud. Understanding Chargeback Prevention for Startup Merchant Accounts What Are Chargebacks and Why Do Startups Need Prevention? Chargebacks occur when a cardholder disputes a credit card charge directly with their issuing bank, prompting a reversal of funds from your merchant account. For startup merchants, frequent chargebacks aren’t just minor hiccups—they can lead to costly penalties, loss of payment processing privileges, or even a frozen bank account. This is why startup chargeback prevention is critical from day one. Startups often operate on slim margins, and a few unexpected reversals are enough to throw off cash flow, frustrate business owners, and threaten your bottom line. By prioritizing chargeback prevention, startups can proactively shield themselves against these setbacks, ensure smooth payment processing, and protect your revenue as you grow. For startups looking to further strengthen their defenses, understanding the legal and operational foundations of small business management is equally important. Exploring guidance for building a strong small business can provide additional strategies that complement your chargeback prevention efforts and support long-term stability. How Credit Card Chargeback Works in Startup Contexts A chargeback typically starts when a customer disputes a card charge with their card issuer, often citing fraud, dissatisfaction, or a failure in customer service. The card issuer then temporarily removes the funds from your account and starts the dispute process, collecting evidence from both the cardholder and merchant. For startups, responding quickly and providing compelling documentation is essential to prevent losing both the funds and customer trust. The process exposes founders to complex interactions with card companies and strict timelines set by the issuing bank. Failing to follow through can result in penalties, an increased chargeback ratio, and potential termination of your payment processing capabilities—underscoring the need for proactive chargeback management and robust prevention strategies. The Growing Importance of Chargeback Prevention Strategies for Startups Startups today face a landscape where fraudsters are more sophisticated and card charge disputes are on the rise. As card not present (CNP) transactions increase, so does exposure to friendly fraud and chargeback fraud. Prevention strategies go beyond simple transaction monitoring. They involve advanced fraud detection, swift customer service, and leveraging partnerships with the right payment processor. The earlier you establish chargeback prevention protocols, the better protected your startup will be from the start. Building these strategies helps prevent chargebacks, protect your business reputation, and positions your company to scale confidently—even in a challenging fintech environment. Chargeback Type Description Impacts Prevention Methods Card Charge Legitimate transaction later disputed by customer Loss of funds, higher chargeback ratio, potential account termination Clear billing, timely delivery, signature confirmation Fraudulent Chargeback Unauthorized or counterfeit credit card use Revenue loss, fines, increased costs of fraud prevention Fraud detection tools, AVS, CVV checks, EMV Friendly Fraud Customer falsely claims fraud/dispute to recover funds Loss of goods/services and funds, customer trust erosion Strong communication, order tracking, providing clear receipts How Chargebacks Disrupt Startup Businesses—and Why Startup Chargeback Prevention Matters Startup Chargeback Prevention and Its Direct Effects on Revenue and Growth Chargebacks directly chip away at your startup’s revenue and can stall growth in unexpected ways. Every disputed transaction not only results in lost income but also compounds into fees levied by card companies and payment processors. If your chargeback ratio rises above what the processor allows, you risk having your merchant account frozen or terminated. For startups, these penalties can rapidly escalate, making it essential to prevent chargebacks from the outset. Additionally, the financial stability of your business is threatened, as cash flow crunches limit your ability to invest in operations or marketing. Proactive chargeback prevention strategies are essential to safeguard your bottom line and allow uninterrupted growth, especially in the competitive early stages of business. Protecting Your Business from Card Chargeback Risks The risk of card chargebacks increases as your business grows. Effective startup chargeback prevention means identifying potential vulnerabilities in your payment systems and customer service, addressing them before they become liabilities. Integrating fraud detection software, authenticating credit card transactions, and educating your team on common causes of disputes can substantially reduce chargebacks. Remember, the goal is not just to recover lost funds, but to create an environment where disputes are minimized and your reputation remains intact. When founders make prevention a core business objective, they reduce the chances of merchant account loss, preserve cash flow, and protect your business for the long run. Case Study: How a Startup Lost Access to Its Payment Processor After Chargeback Fraud Consider the story of a SaaS founder whose business was thriving—until a wave of friendly fraud chargebacks hit their merchant account. Despite strong sales, the startup failed to respond promptly to disputes and lacked a systematic chargeback prevention plan. Their payment processor flagged the high chargeback ratio and, with little warning, shut off their merchant account. The founder struggled to secure a new processor, customers experienced service interruptions, and revenue came screeching to a halt. This highlights the real-world stakes of startup chargeback prevention: inaction leads to lost payment processing capabilities and, for many startups, a swift downward spiral. “Losing your merchant account is often just the first domino in a cascade of failures for startups.” Identifying the Main Causes of Chargebacks for Startups Common credit card chargeback scenarios in early-stage businesses. Role of customer service failures in creating avoidable disputes. Friendly fraud: What it is and why startups are vulnerable. Detecting and Preventing Friendly Fraud in Startups Friendly fraud, where a genuine customer falsely claims they didn’t receive the product or were charged erroneously, is especially dangerous for startups. Startups are more vulnerable because they may lack robust verification systems or proactive communication. Preventing friendly fraud requires clear receipts, detailed tracking, swift responses to customer complaints, and educating customers on your billing practices. Implementing automated fraud detection tools and working closely with your payment processor can help flag suspicious behavior. Ultimately, integrating prevention strategies into your daily operations will minimize losses from friendly fraud and maintain healthy customer relations. Payment Processor Rules and Card Charge Dispute Process Your payment processor has strict policies for responding to card chargebacks. The dispute process is time-sensitive: after a chargeback is initiated, you have a short window to provide evidence such as order confirmations, delivery proofs, and communication history. Failing to comply may result in financial penalties and jeopardize your merchant account. Understanding the rules—including chargeback thresholds and what the card issuer requires—puts startups at an advantage when navigating these disputes. Robust documentation and prompt communication with your processor are key components of effective chargeback management, ensuring you don’t lose disputes by default and that you protect your revenue as you grow. Startup Chargeback Prevention Strategies: Avoid Card Chargeback Pitfalls Top 10 startup chargeback prevention tips. Implementation of fraud prevention tools for early-stage businesses. Developing a proactive customer service approach for dispute resolution. “Investing in robust startup chargeback prevention techniques pays for itself.” Leveraging Payment Processor Solutions for Effective Startup Chargeback Prevention Payment processors are invaluable allies in preventing chargebacks. Advanced processors offer real-time alerts, fraud filters, and chargeback representment services tailored for startups. By selecting a processor equipped with the latest fraud detection tools, businesses immediately reduce their risk. Ensure your payment partner has experience with chargeback prevention, provides transparent reporting, and supports you in building airtight documentation. Such partnerships help founders stay one step ahead, enabling startups to focus on growth while safeguarding transaction stability and customer trust. Best Practices for Credit Card Charge Monitoring Monitoring every credit card charge—both for patterns of fraud and for customer satisfaction—is central to chargeback prevention. Implement daily transaction reviews, automated alerts for large or suspicious charges, and regular reconciliation of payments. Utilize your processor’s dashboards to spot anomalies early. This vigilance allows business owners to catch issues before they escalate, address disputes promptly, and maintain a healthy chargeback ratio. Incorporating these monitoring routines into your financial workflow means you’re always prepared to combat card chargeback issues. Integrating Fraud Detection for Ongoing Card Charge Protection Fraud detection solutions powered by AI and machine learning are now accessible even for startups. These tools automatically flag irregular purchase patterns, mismatched billing details, and high-risk locations before the transaction is completed. Startups benefit from integrating these technologies, as they help prevent chargebacks before they materialize, save hours of manual review, and add a crucial layer of security. By investing in ongoing fraud prevention technology, you protect your business, reduce chargebacks, and establish a reputation for secure and reliable payment processing. Startup Chargeback Fraud: Identifying and Responding to Threats Understanding Chargeback Fraud and Its Consequences for Startups Chargeback fraud occurs when a transaction is intentionally disputed under false pretenses, often by individuals exploiting loopholes in the payment system. For startups, the stakes are high: too many fraudulent chargebacks will not only cost you goods or services and transaction value, but also risk your merchant account status and brand reputation. Small businesses and startups are especially susceptible because their verification and disruption response may not match those of established enterprises. Proactive monitoring, advanced fraud detection tools, and documented evidence are essential defenses against this growing threat in the digital economy. How Startups Can Prevent Chargeback Fraud with Modern Technology Modern technology offers startups a variety of ways to prevent chargeback fraud effectively. Implementing AVS (Address Verification Service), CVV checks, two-factor authentication, and device fingerprinting minimizes unauthorized transactions. Machine learning-based fraud analytics can detect patterns and flag high-risk behavior before the sale completes. Combining these technological tools with timely customer communication significantly lowers the risk of chargeback fraud and demonstrates to both card providers and customers that you’re a vigilant merchant. Proactive defense is not just best practice; it’s essential to safeguard your business’s future. Step-by-Step Guide to Navigating the Dispute Process When a chargeback occurs, swift action is essential. First, promptly review the dispute notification from your payment processor, then gather all transaction records, delivery confirmations, and communication history with the customer. Next, prepare a clear, organized response and submit it through your payment processor’s chargeback dispute portal. Remain in communication with both the processor and your customer throughout the process. Consistent documentation and rapid response are the foundation of successful dispute resolution—giving your startup the best chance to recover funds and maintain a healthy merchant account standing. “Every successful dispute recovery is a lesson in startup resilience.” Customer Service as a Pillar of Startup Chargeback Prevention Creating Seamless Experiences to Preventing Chargebacks Exceptional customer service is one of the most effective ways to prevent chargebacks. By creating seamless and transparent customer journeys—from easy checkout processes to proactive support—founders drastically reduce the chances of a dispute ever arising. Resolve issues before they escalate and ensure customers have multiple channels to reach your team. Every positive experience is an insurance policy against chargebacks, friendly fraud, and reputational damage. Make customer satisfaction an integral part of your chargeback prevention strategies. How Fast, Transparent Communication Protects Your Revenue Clear, timely, and honest communication is central to protect your revenue. When an issue is detected, quick outreach can turn a potential dispute into an amicable resolution. Explain company policies, refund procedures, and dispute timelines transparently. By keeping customers in the loop, you demonstrate reliability, reduce frustration, and limit the tendency to file a chargeback. Staff should be empowered to solve problems efficiently—building loyalty and minimizing costly card chargeback events. Training Staff for Chargeback Prevention Excellence Your team is your first line of defense against chargebacks. Invest in regular training that covers identifying early signs of disputes, communicating chargeback policies with clarity, and using your payment processor’s chargeback management tools. Employees should understand how to interpret fraud alerts and manage the dispute process professionally. Ongoing training keeps your company’s prevention skills sharp as card company regulations and fraud tactics evolve. This culture of vigilance helps your startup avoid common pitfalls and lowers exposure to unnecessary financial risk. Startup Chargeback Prevention and the Role of Payment Processors How to Choose a Payment Processor With Strong Startup Chargeback Prevention Tools Selecting a payment processor capable of supporting your startup chargeback prevention goals is vital. Compare processors based on features like built-in fraud detection, chargeback reporting, threshold alerts, and transparent chargeback dispute support. Ask about experience working with startups and ensure they offer dedicated support for early-stage businesses. A processor invested in your success shares best practices and provides a partnership—not just a service—helping ensure your merchant account remains in good standing as you grow. Consider costs, integrations, and the quality of their chargeback prevention tools when making your selection. What to Know About Payment Processor Chargeback Dispute Procedures Familiarity with your processor’s chargeback dispute process can save you time and money. Know the documentation you need, the timeframes for response, escalation procedures, and what your processor requires for a successful dispute. Work with their support team to ensure your policies and evidence meet standards set by card issuers. This proactive approach allows founders to protect your business and learn from each dispute—constantly refining prevention measures for the future. Ask questions upfront and establish clear communication channels with your processor from the very beginning. Essential Fraud Detection and Prevention Tools for Startups Automated fraud detection for preventing card chargebacks. Benefits of AI-driven chargeback prevention solutions. Third-party tools for real-time monitoring and reporting. Documenting and Reporting for Startup Chargeback Prevention Keeping Accurate Records for Evidence in the Dispute Process Winning chargeback disputes depends on your ability to produce timely, accurate evidence. Maintain digital records of every transaction, communication, shipping confirmation, and refund. Use secure cloud storage or CRM systems that timestamp actions. This detailed documentation acts as your insurance policy in the event of a chargeback—providing compelling proof to card companies and payment processors. Dedicated record keeping is an investment in both financial safety and operational resilience, helping you reduce chargebacks and protect your merchant account for the long term. Best Practices for Documenting Customer Communication Every interaction with customers can serve as evidence in the dispute process. Ensure all communication (emails, chat transcripts, call logs) is stored systematically and linked with corresponding transactions. Set up standard templates for confirming orders, shipping updates, and issue resolution summaries. This not only streamlines chargeback management, but also strengthens customer trust. Well-documented communication satisfies card issuers’ evidence requirements and places your startup in the strongest possible position to recover revenue when challenged. Training and Education for Ongoing Startup Chargeback Prevention Internal policy creation for preventing chargebacks. Ongoing team training: Why it matters for long-term fraud prevention. Startup Chargeback Prevention Case Studies: Success Stories and Lessons Learned “Our chargebacks dropped by 70% after implementing comprehensive prevention strategies.” – A fintech founder Many emerging fintech businesses and SaaS startups have turned their fortunes around by adopting comprehensive startup chargeback prevention programs. These companies focused on deploying automated fraud detection, strengthening customer service, and closely monitoring card chargebacks. Within months, they saw massive reductions in disputed transactions, better payment processor relationships, and significant improvements to their bottom line. The lesson: preventative action, not reaction, makes all the difference in scaling a resilient company. Comparing Chargeback Prevention Solutions for Startups Tool Key Features Cost (Monthly) Effectiveness FraudShield Pro AI analytics, instant alerts, integrates with all major processors $49–$99 High for early-stage SaaS and ecommerce startups Chargeback Defender Automated representment, real-time resolution, chargeback reports $79–$129 Excellent for dispute-heavy businesses SecurePay Plus Manual review assist, chargeback dispute support, notification system $59–$99 Best for high-ticket-item startups Key Takeaways: Why Startup Chargeback Prevention Should Be Every Founder’s Priority Startup chargeback prevention is central to protecting your business and revenue. Effective strategies reduce the risk of merchant account loss. Ongoing education, customer service, and technology adoption are essential. Startup Chargeback Prevention FAQs What are the first steps to implement startup chargeback prevention? Start by selecting a payment processor with robust prevention features, train your staff, establish clear customer communication protocols, and implement real-time fraud detection tools. How can fintech startups prevent friendly fraud and chargeback fraud? Use transparent billing, keep comprehensive transaction records, respond quickly to customer inquiries, and consider AI-powered fraud detection to spot suspicious activity before it escalates. When do payment processors terminate merchant accounts for excessive card chargebacks? Most payment processors set a strict threshold; if your chargeback ratio exceeds 1% of your monthly transactions, you risk termination. Immediate action is critical if you approach this limit. Are automated fraud detection tools essential for startup chargeback prevention? Yes, especially as your transaction volume increases. Automation helps flag high-risk charges instantly, preventing fraudulent transactions from going through and reducing costly disputes. People Also Ask: Startup Chargeback Prevention How can startups reduce the risk of credit card chargebacks? Startups can reduce the risk of credit card chargebacks by using proactive communication, implementing clear billing descriptors, monitoring for suspicious transactions, providing accurate delivery timelines, and training teams to resolve issues quickly, all as part of a comprehensive startup chargeback prevention plan. What is the best chargeback prevention strategy for a new merchant account? The best strategy combines fraud detection tools, transparent customer service processes, clear refund policies, and ongoing documentation of every transaction. Leveraging your payment processor’s resources further reduces exposure to card chargebacks and ensures early-stage protection. How does startup chargeback prevention differ from traditional chargeback prevention? Startup chargeback prevention places more emphasis on rapid response and flexibility, using technology and internal training to overcome limited resources. Startups also require solutions tailored to high risk, low volume, and the unique challenges of scaling rapidly. Can a startup recover from excessive chargebacks? Yes, but recovery requires immediate action: lowering the chargeback rate, switching processors if necessary, improving fraud prevention systems, and retraining staff. Quick recovery strategies—backed by smarter documentation—restore merchant privileges and rebuild trust with partners. What role does customer service play in preventing chargebacks for startups? Exceptional customer service minimizes dispute escalation, resolves complaints promptly, and fosters transparency—all of which are proven to prevent chargebacks before they happen. It’s a fundamental pillar of effective startup chargeback prevention. Are all payment processors equal when it comes to startup chargeback prevention? No. Some processors offer specialized tools, dedicated support, and startup-focused solutions, while others have minimal prevention options. Research and choose a processor aligned with your business’s chargeback prevention needs to ensure the best protection. Ready to Secure Your Startup? Call for a Free Consultation at 214-854-9931 Conclusion: Startup chargeback prevention is not optional—it’s your safeguard to protecting revenue, ensuring scalable growth, and building a business that stands the test of time. Take action now to strengthen your defenses and allow your vision to thrive. As you continue to refine your chargeback prevention strategies, remember that building a resilient business goes beyond just managing disputes. By investing in the right legal, operational, and financial frameworks, you set the stage for sustainable growth and long-term success. For a deeper dive into foundational business practices that can further protect and empower your startup, consider reviewing comprehensive guidance for building a strong small business. This resource offers actionable insights that complement your chargeback prevention efforts and help you navigate the broader challenges of entrepreneurship with confidence.

About Us:

At Renwick Evans and Associates, we deliver tailored consulting strategies that support your business's unique journey toward growth and success.

We provide strategic guidance for small business owners seeking clarity, stability, and growth. Our services support businesses at every stage—from startup to expansion—through smart strategy and practical solutions.

Connect with Us:

Phone: 214-854-9931

Click to Call Now

{"name":"Call Footer","action_type":"3","optin_action_type":"5","form_redirect_type":"3","form_redirect_funnel_url":"uaahut61mb","form_redirect_custom_url":"","order_form_settings":{"containers":[{"id":"personal-info-wrapper","visible":true,"label":{"id":"of-personal-title","visible":true},"fields":[{"id":"of-full-name","setting":false,"placeholder":"Full Name"},{"id":"of-field-email","setting":false,"placeholder":"Email Address"},{"id":"of-phone-number","setting":true,"visible":false,"require":true,"placeholder":"Enter Your Mobile Phone","additional":{"sms_permission":0}},{"id":"of-gdpr-optin-approval","label":"I Accept To Receive Additional Info","placeholder":"","icon":"fa-mobile","required":0,"visible":0,"system":1,"additional":{"gdpr_optin_approval":"1"}}]},{"id":"shipping-information-wrapper","visible":false,"label":{"id":"of-shipping-title","visible":true},"fields":[{"id":"of-shipping-address","setting":false,"placeholder":"Address"},{"id":"of-shipping-city","setting":false,"placeholder":"City"},{"id":"of-shipping-state","setting":false,"placeholder":"State"},{"id":"of-shipping-zipcode","setting":false,"placeholder":"Postal Code"}]},{"id":"profit-bump-wrapper","visible":true,"otoBgColor":"rgba(219,229,239,1)","otoBorderColor":"rgba(38,71,102,1)","otoTitleBgColor":"rgba(45,78,108,1)","otoArrowsColor":"rgba(255,177,58,1)","fields":[]},{"id":"order-summary-wrapper","visible":true,"orderDynamicBgColor":"rgba(242,242,242,1)","orderDynamicTexColor":"rgba(51,51,51,1)","fields":[]}]},"optin_type":{"showLabels":0,"fields":[{"name":"first_name","label":"Full Name","placeholder":"Enter Your Full Name","icon":"fa-user","required":1,"visible":1,"system":1,"additional":{}},{"name":"last_name","label":"Full Name","placeholder":"Enter Your Full Name","icon":"fa-user","required":1,"visible":1,"system":1,"additional":{}},{"name":"email","label":"Email","placeholder":"Enter Your Email","icon":"fa-envelope","required":1,"visible":1,"system":1,"additional":{}},{"name":"mobile_phone","label":"Mobile Phone","placeholder":"Enter Your Mobile Phone","icon":"fa-mobile","required":0,"visible":0,"system":1,"additional":{"sms_permission":0}},{"name":"fields_labels","label":"","placeholder":"","icon":"","required":0,"visible":1,"system":1,"additional":{}},{"name":"captcha","label":"Captcha","placeholder":"","icon":"","required":1,"visible":1,"system":1,"additional":{}},{"name":"gdpr_optin_approval","label":"SSBBY2NlcHQgVG8gUmVjZWl2ZSBBZGRpdGlvbmFsIEluZm8=","placeholder":"","icon":"fa-mobile","required":0,"visible":1,"system":1,"additional":{"gdpr_optin_approval":"1","sms_permission":0}}],"customFields":[],"sortedFields":[{"name":"first_name","label":"Full Name","placeholder":"Enter Your Full Name","icon":"fa-user","required":1,"visible":1,"system":1,"additional":{}},{"name":"first_name","label":"Full Name","placeholder":"Enter Your Full Name","icon":"fa-user","required":1,"visible":1,"system":1,"additional":{}},{"name":"last_name","label":"Full Name","placeholder":"Enter Your Full Name","icon":"fa-user","required":1,"visible":1,"system":1,"additional":{}},{"name":"email","label":"Email","placeholder":"Enter Your Email","icon":"fa-envelope","required":1,"visible":1,"system":1,"additional":{}},{"name":"mobile_phone","label":"Mobile Phone","placeholder":"Enter Your Mobile Phone","icon":"fa-mobile","required":0,"visible":0,"system":1,"additional":{"sms_permission":0}},{"name":"captcha","label":"Captcha","placeholder":"","icon":"","required":1,"visible":1,"system":1,"additional":{}}],"design":{"form_background_color":"rgb(245, 245, 245)","field_stroke":{"size":"1","color":"rgb(220, 220, 220)"},"field_icons":1,"button_color":"rgb(255, 158, 0)","button_stroke":{"size":"0","color":"rgba(255, 255, 255, 0.2)"},"button_box_shadow_color":"none","field_size":"small","label_size":"16","label_color":"rgb(0, 0, 0)","input_color":"rgb(52, 152, 219)","control_text_color":"rgb(0, 0, 0)","control_text_size":"15"},"mappedFields":[]},"redirect_type":{"url":"","target":0},"next_step":{"value":"uaahut61mb"},"click_to_email":{"value":""},"click_to_call":{"value":"2148549931"},"jump_to_block":{},"content":{"header_text":"PHNwYW4gc3R5bGU9ImZvbnQtc2l6ZToyNHB4OyBmb250LWZhbWlseTonb3BlbiBzYW5zJzsiPjxzcGFuIHN0eWxlPSJsaW5lLWhlaWdodDoxLjRlbTsiPldlIEFyZSBFeGNpdGVkITwvc3Bhbj48L3NwYW4+","content_text":"PHNwYW4gc3R5bGU9ImZvbnQtc2l6ZTo0OHB4OyBmb250LWZhbWlseTonb3BlbiBzYW5zJzsiPjxzcGFuIHN0eWxlPSJsaW5lLWhlaWdodDowLjllbTsiPjxzdHJvbmc+UExFQVNFIEZJTEwgT1VUIFlPVVIgSU5GTyAgQkVMT1cgVE8gU1VCU0NSSUJFPC9zdHJvbmc+PC9zcGFuPjwvc3Bhbj4=","button_text":"PHNwYW4gc3R5bGU9ImZvbnQtc2l6ZToyN3B4OyBmb250LWZhbWlseTonb3BlbiBzYW5zJzsiPjxzcGFuIHN0eWxlPSJsaW5lLWhlaWdodDoxZW07Ij48c3Ryb25nPlNFQ1VSRSBNWSBTUE9UPC9zdHJvbmc+PC9zcGFuPjwvc3Bhbj4=","spam_text":"PHNwYW4gc3R5bGU9ImxpbmUtaGVpZ2h0OjEuMmVtOyI+V2UgaGF0ZSBTUEFNIGFuZCBwcm9taXNlIHRvIGtlZXAgeW91ciBlbWFpbCBhZGRyZXNzIHNhZmU8L3NwYW4+","sms_text":"UmVjZWl2ZSBTTVMgVGV4dCBVcGRhdGVzIC0gPHNwYW4+b3B0aW9uYWw8L3NwYW4+","sms_text2":"SSBBY2NlcHQgVG8gUmVjZWl2ZSBBZGRpdGlvbmFsIEluZm8="},"email_confirmation":{"enable":1,"subject":"V2UgQXJlIEV4Y2l0ZWQhIFlvdXIgSW4h","message":""},"integrations":[],"automation_enable":0,"thank_you":{"type":"popup","redirect_url":"","popup_options":{"background_color":"#ffffff","headline_visible":1,"icon_visible":1,"icon_url":"//my.funnelpages.com/assets-pb/images/thankyou-popup-icon.png","subheadline_visible":1,"button_visible":1,"button_color":"#ffa800","headline_text":"PHNwYW4gc3R5bGU9ImxpbmUtaGVpZ2h0OjEuNGVtOyI+VGhhbmsgWW91IEZvciBDb250YWN0aW5nIFVzPC9zcGFuPg==","subeadline_text":"PHNwYW4gc3R5bGU9ImxpbmUtaGVpZ2h0OjEuNGVtOyI+UGxlYXNlIENoZWNrIFlvdXIgRW1haWw8YnIgLz5XZSBXaWxsIEJlIEZvbGxvd2luZyBVcCBTaG9ydGx5PC9zcGFuPg==","button_text":"Q2xvc2U="}}}

Our Approach:

We believe strategy comes before solutions. By focusing on clarity, transparency, and measurable outcomes, we help business owners make informed decisions that move their businesses forward.

Our mission is to help small businesses rise to new heights through clear strategy, smarter systems, and confident decision-making.

© 2026 Renwick Evans & Associates All Rights Reserved. 5318 S. Hampton Rd. , Dallas, TX 75232. Contact Us. Terms of Service . Privacy Policy

This website contains content that has been created using AI. Results created with AI can be inaccurate, unreliable, and subject to hallucinations. Renwick Evans & Associates disclaims any and all liability arising from use of its AI tool or services. Results created with AI are generally not protectable under intellectual property law, so Users assume all risk associated with potential liability and non-protectability arising from its use. For further details, see the Terms, available above.
eyJjb21wYW55IjoiUmVud2ljayBFdmFucyAmIEFzc29jaWF0ZXMiLCJhZGRyZXNzIjoiNTMxOCBTLiBIYW1wdG9uIFJkLiAgIiwiY2l0eSI6IkRhbGxhcyIsInN0YXRlIjoiVFgiLCJ6aXAiOiI3NTIzMiIsImVtYWlsIjoicmVud2lja0ByZW53aWNrZXZhbnMuY29tIiwidG9zIjoiUEhBK1BITjBjbTl1Wno0OFpXMCtWMmhsYmlCNWIzVWdjMmxuYmkxcGJpQjNhWFJvSUhWekxDQjViM1VnWVhKbElHZHBkbWx1WnladVluTndPeUI1YjNWeUlIQmxjbTFwYzNOcGIyNGdZVzVrSUdOdmJuTmxiblFnZEc4Z2MyVnVaQ0I1YjNVZ1pXMWhhV3dnWVc1a0wyOXlJRk5OVXlCMFpYaDBJRzFsYzNOaFoyVnpMaUJDZVNCamFHVmphMmx1WnlCMGFHVWdWR1Z5YlhNZ1lXNWtJRU52Ym1ScGRHbHZibk1nWW05NElHRnVaQ0JpZVNCemFXZHVhVzVuSUdsdUlIbHZkU0JoZFhSdmJXRjBhV05oYkd4NUlHTnZibVpwY20wZ2RHaGhkQ0I1YjNVZ1lXTmpaWEIwSUdGc2JDQjBaWEp0Y3lCcGJpQjBhR2x6SUdGbmNtVmxiV1Z1ZEM0OEwyVnRQand2YzNSeWIyNW5Qand2Y0Q0S0NqeHdQaVp1WW5Od096d3ZjRDRLQ2p4d1BqeHpkSEp2Ym1jK1UwVlNWa2xEUlR3dmMzUnliMjVuUGp3dmNENEtDanh3UGxkbElIQnliM1pwWkdVZ1lTQnpaWEoyYVdObElIUm9ZWFFnWTNWeWNtVnVkR3g1SUdGc2JHOTNjeUI1YjNVZ2RHOGdjbVZqWldsMlpTQnlaWEYxWlhOMGN5Qm1iM0lnWm1WbFpHSmhZMnNzSUdOdmJYQmhibmtnYVc1bWIzSnRZWFJwYjI0c0lIQnliMjF2ZEdsdmJtRnNJR2x1Wm05eWJXRjBhVzl1TENCamIyMXdZVzU1SUdGc1pYSjBjeXdnWTI5MWNHOXVjeXdnWkdselkyOTFiblJ6SUdGdVpDQnZkR2hsY2lCdWIzUnBabWxqWVhScGIyNXpJSFJ2SUhsdmRYSWdaVzFoYVd3Z1lXUmtjbVZ6Y3lCaGJtUXZiM0lnWTJWc2JIVnNZWElnY0dodmJtVWdiM0lnWkdWMmFXTmxMaUJaYjNVZ2RXNWtaWEp6ZEdGdVpDQmhibVFnWVdkeVpXVWdkR2hoZENCMGFHVWdVMlZ5ZG1salpTQnBjeUJ3Y205MmFXUmxaQ0FtY1hWdmREdEJVeTFKVXlaeGRXOTBPeUJoYm1RZ2RHaGhkQ0IzWlNCaGMzTjFiV1VnYm04Z2NtVnpjRzl1YzJsaWFXeHBkSGtnWm05eUlIUm9aU0IwYVcxbGJHbHVaWE56TENCa1pXeGxkR2x2Yml3Z2JXbHpMV1JsYkdsMlpYSjVJRzl5SUdaaGFXeDFjbVVnZEc4Z2MzUnZjbVVnWVc1NUlIVnpaWElnWTI5dGJYVnVhV05oZEdsdmJuTWdiM0lnY0dWeWMyOXVZV3hwZW1GMGFXOXVJSE5sZEhScGJtZHpMand2Y0Q0S0NqeHdQbGx2ZFNCaGNtVWdjbVZ6Y0c5dWMybGliR1VnWm05eUlHOWlkR0ZwYm1sdVp5QmhZMk5sYzNNZ2RHOGdkR2hsSUZObGNuWnBZMlVnWVc1a0lIUm9ZWFFnWVdOalpYTnpJRzFoZVNCcGJuWnZiSFpsSUhSb2FYSmtJSEJoY25SNUlHWmxaWE1nS0hOMVkyZ2dZWE1nVTAxVElIUmxlSFFnYldWemMyRm5aWE1zSUVsdWRHVnlibVYwSUhObGNuWnBZMlVnY0hKdmRtbGtaWElnYjNJZ1kyVnNiSFZzWVhJZ1lXbHlkR2x0WlNCamFHRnlaMlZ6S1M0Z1dXOTFJR0Z5WlNCeVpYTndiMjV6YVdKc1pTQm1iM0lnZEdodmMyVWdabVZsY3l3Z2FXNWpiSFZrYVc1bklIUm9iM05sSUdabFpYTWdZWE56YjJOcFlYUmxaQ0IzYVhSb0lIUm9aU0JrYVhOd2JHRjVJRzl5SUdSbGJHbDJaWEo1SUc5bUlHVmhZMmdnVTAxVElIUmxlSFFnYldWemMyRm5aU0J6Wlc1MElIUnZJSGx2ZFNCaWVTQjFjeTRnU1c0Z1lXUmthWFJwYjI0c0lIbHZkU0J0ZFhOMElIQnliM1pwWkdVZ1lXNWtJR0Z5WlNCeVpYTndiMjV6YVdKc1pTQm1iM0lnWVd4c0lHVnhkV2x3YldWdWRDQnVaV05sYzNOaGNua2dkRzhnWVdOalpYTnpJSFJvWlNCVFpYSjJhV05sSUdGdVpDQnlaV05sYVhabElIUm9aU0JUVFZNZ2RHVjRkQ0J0WlhOellXZGxjeTRnVjJVZ1pHOGdibTkwSUdOb1lYSm5aU0JoYm5rZ1ptVmxjeUJtYjNJZ1pHVnNhWFpsY25rZ2IyWWdaVzFoYVd3Z2IzSWdVMDFUTGlCVWFHbHpJR2x6SUdFZ1puSmxaU0J6WlhKMmFXTmxJSEJ5YjNacFpHVmtJR0o1SUhWekxpQkliM2RsZG1WeUxDQndiR1ZoYzJVZ1kyaGxZMnNnZDJsMGFDQjViM1Z5SUdsdWRHVnlibVYwSUhObGNuWnBZMlVnY0hKdmRtbGtaWElnWVc1a0lHTmxiR3gxYkdGeUlHTmhjbkpwWlhJZ1ptOXlJR0Z1ZVNCamFHRnlaMlZ6SUhSb1lYUWdiV0Y1SUdsdVkzVnlJR0Z6SUdFZ2NtVnpkV3gwSUdaeWIyMGdjbVZqWldsMmFXNW5JR1Z0WVdsc0lHRnVaQ0JUVFZNZ2RHVjRkQ0J0WlhOellXZGxjeUIwYUdGMElIZGxJR1JsYkdsMlpYSWdkWEJ2YmlCNWIzVnlJRzl3ZEMxcGJpQmhibVFnY21WbmFYTjBjbUYwYVc5dUlIZHBkR2dnYjNWeUlHVnRZV2xzSUdGdVpDQlRUVk1nYzJWeWRtbGpaWE11SUZsdmRTQmpZVzRnWTJGdVkyVnNJR0YwSUdGdWVTQjBhVzFsTGlCS2RYTjBJSFJsZUhRZ0puRjFiM1E3VTFSUFVDWnhkVzkwT3lCMGJ5WnVZbk53T3p4b2FXZG9iR2xuYUhRZ1kyeGhjM005SW1OdmJYQmhibmxUVFZOUWFHOXVaVlZ3WkdGMFpTSStiblZzYkR3dmFHbG5hR3hwWjJoMFBpNGdRV1owWlhJZ2VXOTFJSE5sYm1RZ2RHaGxJRk5OVXlCdFpYTnpZV2RsSUNaeGRXOTBPMU5VVDFBbWNYVnZkRHNnZEc4Z2RYTXNJSGRsSUhkcGJHd2djMlZ1WkNCNWIzVWdZVzRnVTAxVElHMWxjM05oWjJVZ2RHOGdZMjl1Wm1seWJTQjBhR0YwSUhsdmRTQm9ZWFpsSUdKbFpXNGdkVzV6ZFdKelkzSnBZbVZrTGlCQlpuUmxjaUIwYUdsekxDQjViM1VnZDJsc2JDQnVieUJzYjI1blpYSWdjbVZqWldsMlpTQlRUVk1nYldWemMyRm5aWE1nWm5KdmJTQjFjeTQ4TDNBK0NnbzhjRDQ4YzNSeWIyNW5QbGxQVlZJZ1VrVkhTVk5VVWtGVVNVOU9JRTlDVEVsSFFWUkpUMDVUUEM5emRISnZibWMrUEM5d1Bnb0tQSEErU1c0Z1kyOXVjMmxrWlhKaGRHbHZiaUJ2WmlCNWIzVnlJSFZ6WlNCdlppQjBhR1VnVTJWeWRtbGpaU3dnZVc5MUlHRm5jbVZsSUhSdk9qd3ZjRDRLQ2p4dmJENEtDVHhzYVQ1d2NtOTJhV1JsSUhSeWRXVXNJR0ZqWTNWeVlYUmxMQ0JqZFhKeVpXNTBJR0Z1WkNCamIyMXdiR1YwWlNCcGJtWnZjbTFoZEdsdmJpQmhZbTkxZENCNWIzVnljMlZzWmlCaGN5QndjbTl0Y0hSbFpDQmllU0IwYUdVZ1UyVnlkbWxqWlNZak16azdjeUJ5WldkcGMzUnlZWFJwYjI0Z1ptOXliU0FvYzNWamFDQnBibVp2Y20xaGRHbHZiaUJpWldsdVp5QjBhR1VnSm5GMWIzUTdVbVZuYVhOMGNtRjBhVzl1SUVSaGRHRW1jWFZ2ZERzcElHRnVaRHd2YkdrK0NnazhiR2srYldGcGJuUmhhVzRnWVc1a0lIQnliMjF3ZEd4NUlIVndaR0YwWlNCMGFHVWdVbVZuYVhOMGNtRjBhVzl1SUVSaGRHRWdkRzhnYTJWbGNDQnBkQ0IwY25WbExDQmhZMk4xY21GMFpTd2dZM1Z5Y21WdWRDQmhibVFnWTI5dGNHeGxkR1V1SUVsbUlIbHZkU0J3Y205MmFXUmxJR0Z1ZVNCcGJtWnZjbTFoZEdsdmJpQjBhR0YwSUdseklIVnVkSEoxWlN3Z2FXNWhZMk4xY21GMFpTd2dibTkwSUdOMWNuSmxiblFnYjNJZ2FXNWpiMjF3YkdWMFpTd2diM0lnZDJVZ2FHRjJaU0J5WldGemIyNWhZbXhsSUdkeWIzVnVaSE1nZEc4Z2MzVnpjR1ZqZENCMGFHRjBJSE4xWTJnZ2FXNW1iM0p0WVhScGIyNGdhWE1nZFc1MGNuVmxMQ0JwYm1GalkzVnlZWFJsTENCdWIzUWdZM1Z5Y21WdWRDQnZjaUJwYm1OdmJYQnNaWFJsTENCM1pTQm9ZWFpsSUhSb1pTQnlhV2RvZENCMGJ5QnpkWE53Wlc1a0lHOXlJRHh6ZEhKdmJtYytQSE53WVc0Z2MzUjViR1U5SW1OdmJHOXlPaU5HUmpBd01EQTdJajUwWlhKdGFXNWhkR1VnZVc5MWNpQmhZMk52ZFc1MEwzQnliMlpwYkdVZ1lXNWtJSEpsWm5WelpTQmhibmtnWVc1a0lHRnNiQ0JqZFhKeVpXNTBJRzl5SUdaMWRIVnlaU0IxYzJVZ2IyWWdkR2hsSUZObGNuWnBZMlVnS0c5eUlHRnVlU0J3YjNKMGFXOXVJSFJvWlhKbGIyWXBMand2YzNCaGJqNDhMM04wY205dVp6NDhMMnhwUGdvOEwyOXNQZ29LUEhBK0ptNWljM0E3UEM5d1BnbzhhR2xuYUd4cFoyaDBJR05zWVhOelBTSmpiMjF3WVc1NVRtRnRaVlZ3WkdGMFpTSStVbVZ1ZDJsamF5QkZkbUZ1Y3lBbVlXMXdPeUJCYzNOdlkybGhkR1Z6UEM5b2FXZG9iR2xuYUhRK1BHSnlJQzgrQ2p4b2FXZG9iR2xuYUhRZ1kyeGhjM005SW1OdmJYQmhibmxCWkdSeVpYTnpWWEJrWVhSbElqNDFNekU0SUZNdUlFaGhiWEIwYjI0Z1VtUXVJQ3dnUkdGc2JHRnpMQ0JVV0NBM05USXpNand2YUdsbmFHeHBaMmgwUGp4aWNpQXZQZ284YUdsbmFHeHBaMmgwSUdOc1lYTnpQU0pqYjIxd1lXNTVVR2h2Ym1WVmNHUmhkR1VpUGp3dmFHbG5hR3hwWjJoMFBqeGljaUF2UGdvOGFHbG5hR3hwWjJoMElHTnNZWE56UFNKamIyMXdZVzU1UlcxaGFXeFZjR1JoZEdVaVBuSmxibmRwWTJzb1FDbHlaVzUzYVdOclpYWmhibk11WTI5dFBDOW9hV2RvYkdsbmFIUSsiLCJwcml2YWN5IjoiUEhBK1BITjBjbTl1Wno1UVVrbFdRVU5aUEM5emRISnZibWMrUEM5d1Bnb0tQSEErUEhOMGNtOXVaejVVYUdVZ2FXNW1iM0p0WVhScGIyNGdjSEp2ZG1sa1pXUWdaSFZ5YVc1bklIUm9hWE1nY21WbmFYTjBjbUYwYVc5dUlHbHpJR3RsY0hRZ2NISnBkbUYwWlNCaGJtUWdZMjl1Wm1sa1pXNTBhV0ZzTENCaGJtUWdkMmxzYkNCdVpYWmxjaUJpWlNCa2FYTjBjbWxpZFhSbFpDd2dZMjl3YVdWa0xDQnpiMnhrTENCMGNtRmtaV1FnYjNJZ2NHOXpkR1ZrSUdsdUlHRnVlU0IzWVhrc0lITm9ZWEJsSUc5eUlHWnZjbTB1SUZSb2FYTWdhWE1nYjNWeUlHZDFZWEpoYm5SbFpTNDhMM04wY205dVp6NDhMM0ErQ2dvOGNENDhjM1J5YjI1blBrbE9SRVZOVGtsVVdUd3ZjM1J5YjI1blBqd3ZjRDRLQ2p4d1BqeGxiVDVaYjNVZ1lXZHlaV1VnZEc4Z2FXNWtaVzF1YVdaNUlHRnVaQ0JvYjJ4a0lIVnpMQzRnWVc1a0lHbDBjeUJ6ZFdKemFXUnBZWEpwWlhNc0lHRm1abWxzYVdGMFpYTXNJRzltWm1salpYSnpMQ0JoWjJWdWRITXNJR052TFdKeVlXNWtaWEp6SUc5eUlHOTBhR1Z5SUhCaGNuUnVaWEp6TENCaGJtUWdaVzF3Ykc5NVpXVnpMQ0JvWVhKdGJHVnpjeUJtY205dElHRnVlU0JqYkdGcGJTQnZjaUJrWlcxaGJtUXNJR2x1WTJ4MVpHbHVaeUJ5WldGemIyNWhZbXhsSUdGMGRHOXlibVY1Y3lZak16azdJR1psWlhNc0lHMWhaR1VnWW5rZ1lXNTVJSFJvYVhKa0lIQmhjblI1SUdSMVpTQjBieUJ2Y2lCaGNtbHphVzVuSUc5MWRDQnZaaUJEYjI1MFpXNTBJSGx2ZFNCeVpXTmxhWFpsTENCemRXSnRhWFFzSUhKbGNHeDVMQ0J3YjNOMExDQjBjbUZ1YzIxcGRDQnZjaUJ0WVd0bElHRjJZV2xzWVdKc1pTQjBhSEp2ZFdkb0lIUm9aU0JUWlhKMmFXTmxMQ0I1YjNWeUlIVnpaU0J2WmlCMGFHVWdVMlZ5ZG1salpTd2dlVzkxY2lCamIyNXVaV04wYVc5dUlIUnZJSFJvWlNCVFpYSjJhV05sTENCNWIzVnlJSFpwYjJ4aGRHbHZiaUJ2WmlCMGFHVWdWRTlUTENCdmNpQjViM1Z5SUhacGIyeGhkR2x2YmlCdlppQmhibmtnY21sbmFIUnpJRzltSUdGdWIzUm9aWEl1UEM5bGJUNDhMM0ErQ2dvOGNENDhjM1J5YjI1blBrUkpVME5NUVVsTlJWSWdUMFlnVjBGU1VrRk9WRWxGVXp3dmMzUnliMjVuUGp3dmNENEtDanh3UGp4emRISnZibWMrV1U5VklFVllVRkpGVTFOTVdTQlZUa1JGVWxOVVFVNUVJRUZPUkNCQlIxSkZSU0JVU0VGVU9qd3ZjM1J5YjI1blBqd3ZjRDRLQ2p4dmJENEtDVHhzYVQ1WlQxVlNJRlZUUlNCUFJpQlVTRVVnVTBWU1ZrbERSU0JKVXlCQlZDQlpUMVZTSUZOUFRFVWdVa2xUU3k0Z1ZFaEZJRk5GVWxaSlEwVWdTVk1nVUZKUFZrbEVSVVFnVDA0Z1FVNGdKbkYxYjNRN1FWTWdTVk1tY1hWdmREc2dRVTVFSUNaeGRXOTBPMEZUSUVGV1FVbE1RVUpNUlNaeGRXOTBPeUJDUVZOSlV5NGdMQzRnUVU1RUlGVlRMQ0JKVkNZak16azdVeUJEVlZOVVQwMUZVbE1zSUVWWVVGSkZVMU5NV1NCRVNWTkRURUZKVFZNZ1FVeE1JRmRCVWxKQlRsUkpSVk1nVDBZZ1FVNVpJRXRKVGtRc0lGZElSVlJJUlZJZ1JWaFFVa1ZUVXlCUFVpQkpUVkJNU1VWRUxDQkpUa05NVlVSSlRrY3NJRUpWVkNCT1QxUWdURWxOU1ZSRlJDQlVUeUJVU0VVZ1NVMVFURWxGUkNCWFFWSlNRVTVVU1VWVElFOUdJRTFGVWtOSVFVNVVRVUpKVEVsVVdTd2dSa2xVVGtWVFV5QkdUMUlnUVNCUVFWSlVTVU5WVEVGU0lGQlZVbEJQVTBVZ1FVNUVJRTVQVGkxSlRrWlNTVTVIUlUxRlRsUXVQQzlzYVQ0S0NUeHNhVDVOUVV0RlV5Qk9UeUJYUVZKU1FVNVVXU0JVU0VGVUlDaHBLU0JVU0VVZ1UwVlNWa2xEUlNCWFNVeE1JRTFGUlZRZ1dVOVZVaUJTUlZGVlNWSkZUVVZPVkZNc0lDaHBhU2tnVkVoRklGTkZVbFpKUTBVZ1YwbE1UQ0JDUlNCVlRrbE9WRVZTVWxWUVZFVkVMQ0JVU1UxRlRGa3NJRk5GUTFWU1JTd2dUMUlnUlZKU1QxSXRSbEpGUlN3Z0tHbHBhU2tnVkVoRklGSkZVMVZNVkZNZ1ZFaEJWQ0JOUVZrZ1FrVWdUMEpVUVVsT1JVUWdSbEpQVFNCVVNFVWdWVk5GSUU5R0lGUklSU0JUUlZKV1NVTkZJRmRKVEV3Z1FrVWdRVU5EVlZKQlZFVWdUMUlnVWtWTVNVRkNURVVzSUVGT1JDQW9hWFlwSUVGT1dTQkZVbEpQVWxNZ1NVNGdWRWhGSUZOUFJsUlhRVkpGSUZkSlRFd2dRa1VnUTA5U1VrVkRWRVZFTGp3dmJHaytDZ2s4YkdrK1FVNVpJRTFCVkVWU1NVRk1JRVJQVjA1TVQwRkVSVVFnVDFJZ1QxUklSVkpYU1ZORklFOUNWRUZKVGtWRUlGUklVazlWUjBnZ1ZFaEZJRlZUUlNCUFJpQlVTRVVnVTBWU1ZrbERSU0JKVXlCRVQwNUZJRUZVSUZsUFZWSWdUMWRPSUVSSlUwTlNSVlJKVDA0Z1FVNUVJRkpKVTBzZ1FVNUVJRlJJUVZRZ1dVOVZJRmRKVEV3Z1FrVWdVMDlNUlV4WklGSkZVMUJQVGxOSlFreEZJRVpQVWlCQlRsa2dSRUZOUVVkRklGUlBJRmxQVlZJZ1EwOU5VRlZVUlZJZ1UxbFRWRVZOSUU5U0lFeFBVMU1nVDBZZ1JFRlVRU0JVU0VGVUlGSkZVMVZNVkZNZ1JsSlBUU0JVU0VVZ1JFOVhUa3hQUVVRZ1QwWWdRVTVaSUZOVlEwZ2dUVUZVUlZKSlFVd3VQQzlzYVQ0S0NUeHNhVDVPVHlCQlJGWkpRMFVnVDFJZ1NVNUdUMUpOUVZSSlQwNHNJRmRJUlZSSVJWSWdUMUpCVENCUFVpQlhVa2xVVkVWT0xDQlBRbFJCU1U1RlJDQkNXU0JaVDFVZ1JsSlBUU0JQVWlCVVNGSlBWVWRJSUU5U0lFWlNUMDBnVkVoRklGTkZVbFpKUTBVZ1UwaEJURXdnUTFKRlFWUkZJRUZPV1NCWFFWSlNRVTVVV1NCT1QxUWdSVmhRVWtWVFUweFpJRk5VUVZSRlJDQkpUaUJVU0VVZ1ZFOVRMand2YkdrK0Nqd3ZiMncrQ2dvOGNENDhjM1J5YjI1blBreEpUVWxVUVZSSlQwNGdUMFlnVEVsQlFrbE1TVlJaUEM5emRISnZibWMrUEM5d1Bnb0tQSEErV1U5VklFVllVRkpGVTFOTVdTQlZUa1JGVWxOVVFVNUVJRUZPUkNCQlIxSkZSU0JVU0VGVUlFRk9SQ0JUU0VGTVRDQk9UMVFnUWtVZ1RFbEJRa3hGSUVaUFVpQkJUbGtnUkVsU1JVTlVMQ0JKVGtSSlVrVkRWQ3dnU1U1RFNVUkZUbFJCVEN3Z1UxQkZRMGxCVEN3Z1EwOU9VMFZSVlVWT1ZFbEJUQ0JQVWlCRldFVk5VRXhCVWxrZ1JFRk5RVWRGVXl3Z1NVNURURlZFU1U1SElFSlZWQ0JPVDFRZ1RFbE5TVlJGUkNCVVR5d2dSRUZOUVVkRlV5QkdUMUlnVEU5VFV5QlBSaUJRVWs5R1NWUlRMQ0JIVDA5RVYwbE1UQ3dnVlZORkxDQkVRVlJCSUU5U0lFOVVTRVZTSUVsT1ZFRk9SMGxDVEVVZ1RFOVRVMFZUSUNoRlZrVk9JRWxHSUVoQlV5QkNSVVZPSUVGRVZrbFRSVVFnVDBZZ1ZFaEZJRkJQVTFOSlFrbE1TVlJaSUU5R0lGTlZRMGdnUkVGTlFVZEZVeWtzSUZKRlUxVk1WRWxPUnlCR1VrOU5Pand2Y0Q0S0NqeHZiRDRLQ1R4c2FUNVVTRVVnVlZORklFOVNJRlJJUlNCSlRrRkNTVXhKVkZrZ1ZFOGdWVk5GSUZSSVJTQlRSVkpXU1VORk96d3ZiR2srQ2drOGJHaytWRWhGSUVOUFUxUWdUMFlnVUZKUFExVlNSVTFGVGxRZ1QwWWdVMVZDVTFSSlZGVlVSU0JIVDA5RVV5QkJUa1FnVTBWU1ZrbERSVk1nVWtWVFZVeFVTVTVISUVaU1QwMGdRVTVaSUVkUFQwUlRMQ0JFUVZSQkxDQkpUa1pQVWsxQlZFbFBUaUJQVWlCVFJWSldTVU5GVXlCUVZWSkRTRUZUUlVRZ1QxSWdUMEpVUVVsT1JVUWdUMUlnVFVWVFUwRkhSVk1nVWtWRFJVbFdSVVFnVDFJZ1ZGSkJUbE5CUTFSSlQwNVRJRVZPVkVWU1JVUWdTVTVVVHlCVVNGSlBWVWRJSUU5U0lFWlNUMDBnVkVoRklGTkZVbFpKUTBVN1BDOXNhVDRLQ1R4c2FUNVZUa0ZWVkVoUFVrbGFSVVFnUVVORFJWTlRJRlJQSUU5U0lFRk1WRVZTUVZSSlQwNGdUMFlnV1U5VlVpQlVVa0ZPVTAxSlUxTkpUMDVUSUU5U0lFUkJWRUU3UEM5c2FUNEtDVHhzYVQ1VFZFRlVSVTFGVGxSVElFOVNJRU5QVGtSVlExUWdUMFlnUVU1WklGUklTVkpFSUZCQlVsUlpJRTlPSUZSSVJTQlRSVkpXU1VORk95QlBVand2YkdrK0NnazhiR2srUVU1WklFOVVTRVZTSUUxQlZGUkZVaUJTUlV4QlZFbE9SeUJVVHlCVVNFVWdVMFZTVmtsRFJTNDhMMnhwUGdvOEwyOXNQZ29LUEhBK1BIVStRbmtnY21WbmFYTjBaWEpwYm1jZ1lXNWtJSE4xWW5OamNtbGlhVzVuSUhSdklHOTFjaUJsYldGcGJDQmhibVFnVTAxVElITmxjblpwWTJVc0lHSjVJRzl3ZEMxcGJpd2diMjVzYVc1bElISmxaMmx6ZEhKaGRHbHZiaUJ2Y2lCaWVTQm1hV3hzYVc1bklHOTFkQ0JoSUdOaGNtUXNJQ1p4ZFc5ME8zbHZkU0JoWjNKbFpTQjBieUIwYUdWelpTQlVSVkpOVXlCUFJpQlRSVkpXU1VORkpuRjFiM1E3SUdGdVpDQjViM1VnWVdOcmJtOTNiR1ZrWjJVZ1lXNWtJSFZ1WkdWeWMzUmhibVFnZEdobElHRmliM1psSUhSbGNtMXpJRzltSUhObGNuWnBZMlVnYjNWMGJHbHVaV1FnWVc1a0lHUmxkR0ZwYkdWa0lHWnZjaUI1YjNVZ2RHOWtZWGt1UEM5MVBqd3ZjRDRLQ2p4d1BpWnVZbk53T3p3dmNENEtVbVZ1ZDJsamF5QkZkbUZ1Y3lBbVlXMXdPeUJCYzNOdlkybGhkR1Z6UEdKeUlDOCtDalV6TVRnZ1V5NGdTR0Z0Y0hSdmJpQlNaQzRnTENCRVlXeHNZWE1zSUZSWUlEYzFNak15UEdKeUlDOCtDanhpY2lBdlBncHlaVzUzYVdOcktFQXBjbVZ1ZDJsamEyVjJZVzV6TG1OdmJRPT0ifQ==

Terms of Service

Privacy Policy

Core Modal Title

Sorry, no results found

You Might Find These Articles Interesting

T
Please Check Your Email
We Will Be Following Up Shortly
*
*
*