Renwick Evans and Associates
  • Blog Home
  • Categories
    • Startup Launch Guidance
    • Cash Flow, Funding & Capital Strategies
    • Business Operations, challenges & Solutions
    • Merchant Processing & Payments
    • Business Marketing That Works
    • Business Growth & Scaling
    • Business Consulting Insights
    • Compliance & Risk Management
  • Home
July 29.2026
1 Minute Read

Choosing Between Flat Rate and Interchange Pricing

A Surprising Truth About Merchant Pricing Models

Did you know that over 60% of small businesses overpay for payment processing due to improper selection of merchant pricing models? Many business owners unintentionally lock themselves into fee structures that don’t match their transaction patterns or growth. In this article, we unravel the complexities behind merchant pricing models so you can make smarter decisions about your payment process and avoid unnecessary expenses. Whether you’re a startup, a growing retailer, or an established professional service, understanding how to choose between flat rate and interchange pricing is crucial to minimizing your processing fees and maximizing your bottom line.
Business owner reviewing payment processing reports as part of merchant pricing models decision

What You'll Learn About Merchant Pricing Models

  • The definition and differences between flat rate and interchange merchant pricing models
  • How each pricing structure impacts your payment processing costs
  • Key factors to consider for your business when selecting a pricing model
  • Expert tips on optimizing your merchant service payments

Understanding Merchant Pricing Models in Payment Processing

Defining Merchant Pricing Models and Their Role in the Payment Process

Merchant pricing models are the foundation of every payment processing agreement, influencing both your bottom line and how efficiently payments flow through your business. In simple terms, a pricing model dictates how much you, as a business owner, pay in processing fees each time a customer completes a card transaction—be it by debit card, credit card, or another form of electronic payment. The pricing structure you select not only determines direct costs but also impacts cash flow, reconciliation, and the transparency of your payment process. By understanding what goes into these models, including how interchange fees are set by card networks and what markups your service provider adds, you can better control unexpected expenses and ensure that your merchant service aligns with your business goals. Businesses that actively evaluate and tailor their pricing models often benefit from improved profitability and fewer surprises in their monthly statements.

For a deeper dive into how payment processing fees are structured and how you can negotiate better terms, you may find it helpful to explore additional resources on building a strong small business foundation. Understanding the legal and financial aspects of your agreements can further empower you to make informed decisions about your merchant pricing model.

Common Pricing Models: Flat Rate, Interchange, and Beyond

  • Flat Rate Pricing Model: A single, predictable processing fee applied to every transaction, regardless of the card type used.
  • Interchange Plus Pricing Model: Separates the true interchange fee (set by card networks) from the processor’s markup for greater transparency.
  • Tiered Pricing: Transactions are classified into categories ("tiers") like qualified, mid-qualified, and non-qualified, each with different rates based on risk and card type.
  • Other Common Pricing Structures: Subscription-based and blended models offer variations for unique needs, often including monthly flat fees or hybrid cost structures.
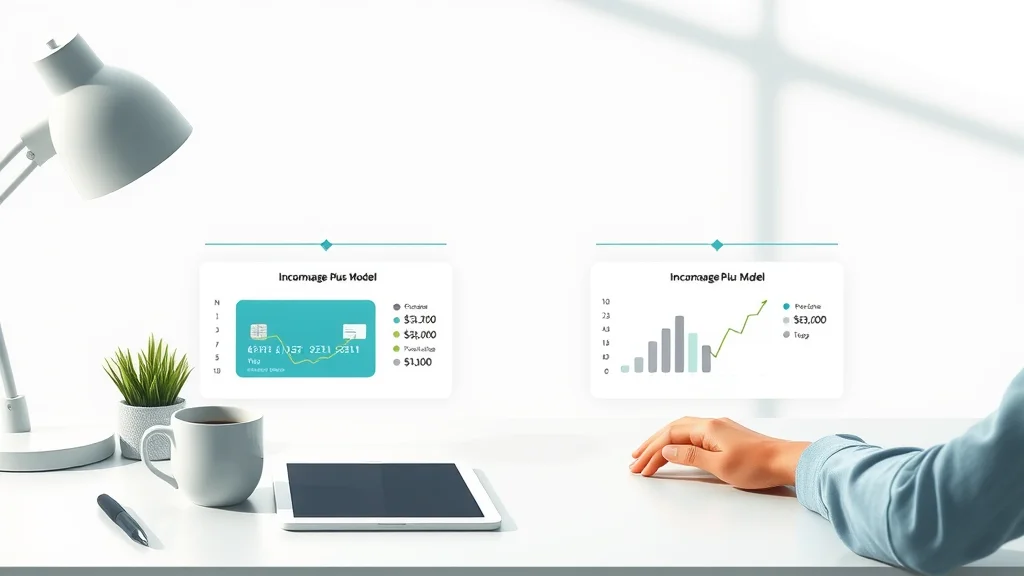
Infographic of flat rate vs interchange plus merchant pricing models for payment processing decision

Flat Rate vs. Interchange Plus: Comparing Payment Processing Approaches

What Is Flat Rate Merchant Pricing?

Flat rate pricing has become a popular choice for startups, microbusinesses, and growing companies seeking predictability in their payment process. With this model, your merchant service provider charges a fixed percentage per card transaction—commonly ranging from 2. 6% to 2. 9%—regardless of the customer’s card type or issuing bank. This simplicity allows you to forecast processing fees each month and often streamlines your accounting. However, that convenience may come at a price: since the same fee applies whether your customer pays with a debit card or premium credit card, some transactions could carry higher processing fees than if you were using a more nuanced pricing structure. The flat rate model is ideal for businesses processing a modest volume of transactions, offering peace of mind over budgeting and minimal complexity in reconciliation and reporting.

Understanding Interchange Plus Merchant Pricing Models

Unlike the flat rate approach, interchange plus pricing breaks down your merchant service costs into two key components: the interchange fee charged by card networks (like Visa, Mastercard, or Amex) and a separate markup set by your payment processor. This transparent pricing structure means your final rate can fluctuate based on the type of card used, the transaction method (such as online, in-store, or keyed-in), and the risk associated with each transaction. While this model can seem more complex, it allows high-volume or established merchants to benefit from lower average processing fees—especially for debit card payments that carry lower interchange rates. Businesses prioritizing complete visibility into their transaction fees and looking to optimize costs as they scale often prefer this approach.

Table: Flat Rate vs. Interchange Plus Pricing at a Glance

Feature Flat Rate Pricing Interchange Plus Pricing
Cost Predictability High Variable
Transparency Moderate High
Transaction Fee Basis Fixed % Interchange fee + markup
Best For Low volume/average ticket High volume/large ticket
Complexity Low Moderate to high

Cashier processing a card payment, representing merchant pricing models in action

Factors Influencing Merchant Pricing Models Choice

Business Size, Transaction Volume, and Payment Process Needs

Your business’s unique characteristics—like its size, sales volume, and preferred payment methods—directly influence which merchant pricing model makes the most sense for you. Small businesses and start-ups with lower average tickets or occasional transactions often benefit from simpler flat rate pricing, taking advantage of predictable budgets and easy-to-understand statements. In contrast, larger businesses processing thousands of transactions monthly may find the savings from interchange plus pricing substantial, especially if they accept a wide array of card types. When considering what works best, assess how average ticket size, overall volume, and seasonal patterns affect your processing fee burden. Aligning your pricing structure and merchant service requirements ensures you don’t pay more than necessary for each card transaction and that your payment process keeps pace as your business grows.

Payment Processing Security and Transparency Considerations

Security and transparency are critical when comparing merchant pricing models. Interchange plus pricing is often favored by businesses needing a clear, itemized breakdown of processing fees, which can be crucial for financial audits and compliance. This transparency helps you spot irregularities or unnecessary charges, enabling tighter controls on your merchant service expenses. Flat rate pricing, on the other hand, minimizes detailed accounting—but may obscure the true cost of each transaction type. Additionally, choosing a pricing structure that prioritizes security and regulatory compliance is vital to avoiding hidden costs and penalties associated with breaches or non-compliance (such as PCI DSS requirements). Always inquire about how each model addresses these concerns with your service provider before signing any agreement.
Secure merchant pricing models with analyst monitoring payment dashboard for compliance and transparency

Impact of Pricing Models on Merchant Services and Customer Experience

The choice between flat rate and interchange plus merchant pricing models doesn’t just impact your financials—it also shapes your customers’ payment experience. Competitive, transparent transaction fees can translate into better pricing for your products or services, helping to build trust and loyalty. Hidden or unpredictable fees may eventually force price increases, which can erode customer satisfaction and diminish your reputation. As you evaluate pricing structures, consider how the chosen model supports smooth payment processes, enhances service transparency, and reduces the risk of disputes or chargebacks. Ultimately, the right merchant service approach can strengthen both your profit margins and your client relationships.

Real-World Examples: When Flat Rate or Interchange Plus Merchant Pricing Models Prevail

Flat Rate Pricing Structure: Suited for Simplicity

  • Start-ups and microbusinesses using payment processing for low ticket transactions
  • Seasonal businesses preferring straightforward merchant service costs

Interchange Plus Model: Optimization for Established Merchants

  • High-volume retailers requiring detailed transaction fee breakdowns
  • Professional services seeking scalable, transparent merchant services

Quotes From Industry Experts on Merchant Service Pricing Models

“It’s not about choosing the cheapest merchant pricing model, but the one that aligns with your payment processing goals and customer demands.” — Payment Industry Leader
“Flat rate structures simplify accounting, but interchange plus provides powerful transparency for growing businesses.” — Small Business Consultant

A brief video overview explaining the differences, pros, and cons of pricing models for merchant services.

Frequently Asked Questions About Merchant Pricing Models

  • How do transaction fees work in merchant pricing models?
    Transaction fees are charges applied to each sale made using a card. In flat rate pricing, a consistent percentage covers most transaction types. In interchange plus, the fee includes a base interchange (set by card type and network) plus your processor’s markup. Both methods can also include additional fees for specific merchant services or risk factors.
  • What’s the difference between interchange and tiered pricing?
    Interchange pricing charges the real cost of each card type plus a clear markup, making it highly transparent. Tiered pricing groups transactions into pre-set categories (qualified, mid-qualified, non-qualified), sometimes resulting in higher fees and less transparency as you may not always know which category specific transactions fall into.
  • Can I negotiate flat rate pricing with my merchant service provider?
    Yes, some service providers allow business owners to negotiate flat rate percentages, especially if your sales volume increases or you have a long-standing relationship. Shop around and ask if your provider can match competitors or offer better terms based on your transaction history and business outlook.

People Also Ask: What are the 4 types of pricing?

The four primary pricing models in payment processing are flat rate, interchange plus, tiered pricing, and subscription-based pricing.

People Also Ask: What are the 5 C's of pricing?

The 5 C’s of pricing include Company objectives, Customers, Costs, Competition, and Channel members. Each plays a strategic role in determining merchant pricing models and ensuring your selected pricing structure aligns with business priorities.
Team discussing merchant pricing strategy and the 5 C

People Also Ask: Is it legal to charge a 4% credit card fee?

Yes, in many regions, it is legal to charge a surcharge for credit card use—sometimes up to 4%—as long as it complies with state or card network regulations. It’s essential to review your local laws and card network guidelines before adding such fees to ensure your merchant pricing model remains compliant.

People Also Ask: What are the types of pricing models?

The main types of merchant pricing models include flat rate, interchange plus, tiered pricing, and subscription models. Each has its own balance of transparency, complexity, and suitability depending on your transaction volume and merchant service requirements.

Lists: Pros and Cons of Flat Rate and Interchange Merchant Pricing Models

  • Flat Rate Pros: Ease of calculation, predictable budgeting, good for startups
  • Flat Rate Cons: Usually higher per-transaction cost for larger merchants
  • Interchange Plus Pros: Transparent charges, lower costs for high-volumes
  • Interchange Plus Cons: More complex to understand, variable monthly costs

Key Takeaways on Choosing the Right Merchant Pricing Models

  • Match your merchant pricing model to business size and payment process demands
  • Prioritize clarity in pricing structure to avoid unnecessary transaction fees
  • Regularly review your merchant services agreement as your business evolves
Entrepreneur consulting with expert on choosing merchant pricing models in an office setting

Watch a succinct video guide on leveraging your business profile to negotiate better rates and payment process terms in your merchant pricing models.

Conclusion: Making the Most of Your Merchant Pricing Models

Choosing the right merchant pricing models for your payment process is an essential decision with long-term impact on your business’s bottom line. Assess your priorities and consult with merchant service experts for the optimal fit.

As you continue to refine your approach to payment processing, remember that a strong foundation in business strategy and legal compliance is just as important as choosing the right pricing model. For further guidance on building a resilient and successful small business, including tips on contracts, risk management, and sustainable growth, explore our comprehensive resource on guidance for building a strong small business. Taking a holistic view of your operations will help you make smarter decisions, protect your interests, and position your business for long-term success.
Ready to find the ideal merchant pricing model? Call for a free consultation at 214-854-9931

Merchant Processing & Payments

Write A Comment

*
*
Please complete the captcha to submit your comment.
Related Posts All Posts
09.16.2026

Payment Processing for Subscription-Based Startups

As you consider the essential components of subscription payment processing, it's also valuable to explore how recurring billing automation can further streamline your operations and reduce manual errors. For a practical breakdown of recurring billing best practices and actionable setup tips, check out this guide on optimizing recurring billing for startups. If you’re ready to take your startup’s payment infrastructure to the next level, it’s worth broadening your perspective beyond just payment processing. Building a resilient subscription business also means understanding the legal, operational, and strategic foundations that support long-term growth. For a comprehensive look at how to strengthen your small business from the ground up—including legal considerations and sustainable business practices—explore this in-depth resource on building a strong small business. By combining robust payment systems with holistic business strategies, you’ll be well-positioned to thrive in the competitive subscription economy.

09.09.2026

Best Merchant Services for Retail Startups

Did you know that 82% of retail startups fail without reliable payment processing? It’s true: having the right retail merchant services isn’t just nice to have—it’s mission critical for every budding retail business. This guide cuts through the noise to reveal how the right merchant service companies can unlock your startup’s growth, prevent payment pitfalls, and transform your retail store into a customer favorite. Revealing the Real Impact of Retail Merchant Services on Startup Growth As a retail startup, your path to profitability hinges on seamless payment processing solutions and the ability to quickly accept card payments, whether from credit cards, debit cards, or digital wallets. Without a trusted merchant service provider, cash flow can stall, customer trust can erode, and you risk falling behind competitors who streamline every transaction. Retail merchant services provide the lifeblood for your business, handling everything from card machine setup to chargeback protection, and direct connections to financial networks for instant day settlement. The right services company doesn’t just move money—they move your business forward. Success in the retail world means more than stocking shelves and managing staff. With over 60% of transactions now cashless in modern retail businesses, your ability to accept card payments is directly tied to sales growth, better customer experiences, and repeat purchases. Reliable payment processing opens doors for omnichannel sales, from in-store POS systems to online and mobile checkouts. In this article, we'll unpack why payment service providers are essential for startups, how to compare merchant services, and which solutions offer the competitive edge needed in a crowded retail marketplace. When evaluating merchant service providers, it's also helpful to understand how payment processing fits into the broader foundation of your business. For a deeper dive into building a resilient small business from the ground up, including legal and operational essentials, explore this comprehensive guide to small business fundamentals. A Startling Fact: 82% of Retail Startups Fail Without Reliable Payment Processing That’s right: data shows failure to secure dependable, secure merchant service relationships and easy card payment procedures puts startups at a major disadvantage. After all, friction at the checkout often leads to lost sales—and no small business can afford that. What You'll Learn About Retail Merchant Services for Small Businesses Key features of the best retail merchant services How merchant services impact retail startup success Industry-leading merchant service companies and processing solutions Retail merchant service costs and payment processing considerations Understanding Retail Merchant Services and Payment Processing Solutions What Are Retail Merchant Services? Retail merchant services refer to the comprehensive suite of payment processing tools and services that empower small businesses to accept and manage payments made with credit cards, debit cards, and other modern card payment methods. These services span everything from opening a merchant account (which functions as a temporary holding bank account) to supporting POS systems, online checkout integration, fraud management, and automated reporting. Unlike ordinary bank accounts, merchant services are tailored for fast-moving retail selling—giving you the agility to handle in-person, mobile, or online transactions with equal confidence. For startups in particular, choosing the right retail merchant service provider can make the crucial difference between seamless sales and disruptive headaches. Reliable merchant service companies streamline the way your retail business processes payments, minimize cash flow delays, and safeguard against card fraud or chargebacks. They act as trusted partners, not just vendors, giving you access to state-of-the-art card machines, virtual terminal options, and transparent processing costs tailored to your unique growth stage. How Merchant Service Companies Work for Small Business Retailers A merchant services company acts as the engine behind every successful card transaction. They enable your retail merchant setup to accept card payments by connecting your POS system or card reader to global financial networks. When a customer pays with a credit card or debit card, your merchant account receives the payment, verifies the transaction, and deposits the funds safely—typically with next-day or even same-day settlement for robust cash flow. The best services provide dashboard access for tracking sales, real-time alerts, and easy access to technical or customer support. Small business retailers benefit from merchant service companies that offer flexible contract terms (monthly or pay-as-you-go), transparent fee structures, and advanced fraud detection. Look for providers that integrate with a wide range of hardware—from advanced POS terminals to smartphone-compatible dongles—and who facilitate both physical and e-commerce transactions. This not only caters to changing customer behaviors but also ensures your retail business won’t be left behind by new payment technologies. Role of Credit Card and Card Machines in Merchant Services Card machines and POS terminals are the critical hardware components that bring merchant services to life in any retail store. These devices authenticate, process, and encrypt card payments—allowing fast, secure, and reliable checkouts whether via chip, swipe, tap, or digital wallets. Modern merchant services companies often provide or lease these machines as part of their overall service suite, ensuring compatibility with multiple card types and payment apps. Having the latest card machine or virtual terminal boosts your brand’s professionalism and customer trust. Speedy card processing means shorter lines and fewer abandoned baskets—a must for busy retail environments. On top of this, advanced POS systems can sync with inventory management, track customer preferences, and produce detailed sales reports—helping startups turn payment data into actionable business insights. Top Features of the Best Retail Merchant Services Integrated payment processing solutions Seamless credit card and debit card acceptance POS card machines and terminals Competitive pricing structures for small business Robust fraud and chargeback management The best retail merchant services go beyond simple payment acceptance. Integrated processing solutions ensure your operation can handle all forms of card payments—chip, magstripe, contactless, and even new methods like QR codes or mobile wallets. Seamless integration into your POS system reduces training time and the risk of manual entry errors. Competitive pricing—typically ranging from 1. 5% to 3. 5% on card transactions—is vital for protecting margins, while robust chargeback management provisions shield your business from common pitfalls that disrupt cash flow. When choosing a service provider, ensure they offer fraud detection tools, next-day settlements, online reporting, and on-demand customer service. Whether you’re processing a few card transactions per day or managing multi-location sales, these features will help your startup operate efficiently and confidently in a fast-moving retail landscape. Comparison Table: Leading Retail Merchant Service Companies Merchant Service Company Key Features Costs & Fees Contract Terms Processing Speed Best For Square Free POS, card reader, online invoicing, real-time reporting 2.6% + 10¢ per transaction No long-term contract Next day Retail popups & startups Clover Customizable POS, inventory tools, contactless payments 2.3% + 10¢ per transaction Monthly contracts Same or next day Growing small businesses Helcim Transparent pricing, virtual terminal, advanced security Interchange + 0.3% + 8¢ No contract 1-2 days Cost-conscious startups Stripe API integration, online/offline payments, fraud detection 2.9% + 30¢ per online transaction Month-to-month 2 days Omnichannel retailers PayPal Zettle Simple POS, card reader, eCommerce sync 2.29% per transaction No contract Next day Side businesses & mobile sellers Best Retail Merchant Services for Startups: Detailed Reviews Review: [Top Merchant Service Company #1] Square is a pioneer in retail payment processing solutions, renowned for intuitive design, transparent pricing, and no-hassle contracts. Their free POS system, coupled with an affordable card reader, allows startups to accept credit and debit card payments anywhere—whether in-store, curbside, or at pop-up events. Square stands out for its crystal-clear 2. 6% + 10¢ per transaction fee—no hidden costs or monthly minimums. With seamless integration into modern retail environments, Square helps small businesses thrive by ensuring reliable cash flow, same-day settlements, and 24/7 support. Comprehensive sales and customer insights are only a tap away in the Square Dashboard, giving startup retailers a powerful advantage in a competitive market. Alongside brick-and-mortar capability, Square supports online checkouts and digital wallet payments, allowing retailers to meet customers where they shop. With built-in chargeback protection and fraud detection, it keeps your business secure as you scale. For startups needing adaptability, speed, and transparent service, Square is among the best in the industry. Review: [Top Merchant Service Company #2] Clover is a favorite among retail merchants looking for a customizable and scalable POS ecosystem. Its modular system—featuring everything from sleek card machines and contactless card readers to inventory management tools—caters to both new startups and growing businesses. Clover’s transaction fees are competitive (2. 3% + 10¢), and the platform offers monthly contract flexibility, important for startups wary of long-term commitments. What sets Clover apart is its vast app marketplace, empowering retailers to expand as their needs evolve—from customer loyalty programs to online store integration. With robust support for debit and credit card acceptance, quick day settlement, and superior chargeback resolution, Clover is ideal for startups seeking growth potential. Their hardware options cover everything from stationary POS terminals to mobile card readers for smartphone or tablet use—all backed by industry-standard security and PCI compliance. Review: [Top Merchant Service Company #3] Helcim is best known for its radically transparent, low-cost pricing—making it a top pick for cost-conscious retail startups. Helcim uses an interchange-plus structure, with rates as low as interchange + 0. 3% + 8¢ per transaction, passing savings directly to retailers as they grow. Their POS system is user-friendly and versatile, supporting both brick-and-mortar and online sales, plus a powerful virtual terminal for phone or mail orders. Helcim includes free PCI compliance and advanced security tools to protect against fraud and chargebacks, reducing risk for small businesses. Fast processing (1-2 day settlement), real-time reporting, and no long-term contracts help startups stay agile while maintaining healthy cash flow. Helcim’s strong focus on customer support and resource guides is an additional plus for first-time business owners navigating retail payment systems for the very first time. How to Choose the Right Retail Merchant Services for Your Startup Assessing processing solutions and hardware needs Comparing credit card transaction fees Evaluating customer support and merchant account services Considering setup costs and contract flexibility Choosing the optimal merchant services company starts with a frank assessment of your retail operation’s scale, expected transaction volume, and technical requirements. New startups may want low-cost, plug-and-play solutions like Square or PayPal Zettle, while ambitious businesses gearing up for rapid growth might benefit from an all-in-one system like Clover or customizable solutions like Helcim. Carefully compare credit card and debit card fees—not just per-transaction charges, but also hidden costs like PCI compliance, service provider support, chargeback fees, and hardware rentals. Pay special attention to setup timelines, ease of onboarding, contract flexibility, and whether the provider offers responsive customer support via multiple channels. Look for transparent terms, quick day settlement for consistent cash flow, and integration with online platforms for omnichannel sales. Startups should choose a merchant account that scales with the business and won’t lock them into restrictive or costly arrangements. Video Guide: Setting Up Retail Merchant Services for Small Businesses Expert Quote: On the Value of Merchant Services for Retail Small Business "Choosing the right retail merchant service can mean the difference between thriving and surviving for startups. Reliable payment processing is your lifeline to steady revenue." — Industry Payment Professional People Also Ask: Frequently Searched Questions About Retail Merchant Services Who owns retail merchant services? Answer: Retail merchant services can be owned by independent companies, financial institutions, or specialized payment processors offering merchant accounts and processing solutions to retailers. What does a retail merchant do? Answer: A retail merchant manages the sale of goods and services to customers, handling payments, inventory, and customer service—crucially relying on merchant services for secure credit card and digital payment processing. How much does retail merchant services charge? Answer: Costs vary by merchant service company but typically include transaction fees, monthly service charges, and equipment costs. Fees for retail merchant services generally range from 1. 5% to 3. 5% per credit card transaction. What's the cheapest way to accept credit cards? Answer: The least expensive option is often a flat-rate processing solution with no long-term contract or monthly minimums. Many retail merchant service providers now offer transparent pricing for small business startups. Video Tutorial: Comparing Card Machines and Payment Processing Solutions Pros and Cons List: Retail Merchant Services for Startups Pros: Fast payments, increased sales, improved customer trust, flexible payment processing. Cons: Monthly and transaction fees, contract terms, potential chargebacks. FAQs: Quick Answers to Retail Merchant Services Queries What is the difference between retail merchant services and traditional bank accounts? Retail merchant services provide specialized payment processing, chargeback protection, and point-of-sale integrations—unlike standard bank accounts, which do not process customer card transactions or offer POS solutions. Are retail merchant services necessary for online retail businesses? Yes—any business selling online needs a merchant account or payment services company to securely process credit card and digital wallet payments. Can startups negotiate payment processing fees with merchant service companies? In many cases, yes—startups with higher volume or growth potential can often negotiate lower rates or transaction fees with providers. What is PCI compliance and why does it matter for small business retailers? PCI compliance ensures your payment system securely handles cardholder data, protecting against fraud and data breaches—a prerequisite for any retail merchant service provider. Key Takeaways: Finding the Best Retail Merchant Services for Your Business Choosing optimal retail merchant services requires comparing features, pricing, and support. Reliable payment processing is essential for retail startup growth and customer trust. Startups benefit from transparent, scalable, and secure merchant service solutions. Ready to Grow Your Startup? Call for a Free Consultation at 214-854-9931 With the right retail merchant services partner, your startup can thrive—unlocking faster sales, happier customers, and steady growth in a dynamic retail landscape. As you continue to refine your retail startup’s payment infrastructure, remember that merchant services are just one pillar of a resilient business. For a holistic approach to building a strong foundation—covering legal, operational, and strategic considerations—take the next step by reviewing expert guidance for small business success. This resource offers actionable insights that go beyond payments, helping you future-proof your venture and navigate the challenges of growth with confidence. Investing in both robust merchant services and sound business practices will position your startup for long-term achievement in today’s competitive retail landscape.

09.02.2026

How Chargebacks Hurt Startup Merchant Accounts

Did you know over 80% of startups are hit with chargebacks in their first year—risking not only their revenue but their very survival? While many founders focus on growth and customer acquisition, few realize just how devastating chargebacks can be to young businesses. In this article, you’ll learn how startup chargeback prevention can save your company from costly pitfalls, secure your merchant account, and ultimately protect your business as you scale. A Startling Look at Startup Chargeback Prevention and Its Impact on Startup Merchant Accounts Unveiling a surprising statistic: Over 80% of startups experience chargebacks within their first year. Why startup chargeback prevention is more than just a finance issue—it's a survival strategy. “Chargebacks aren’t just the cost of doing business—they can be the difference between scaling or shuttering your startup.” What You'll Learn About Startup Chargeback Prevention How chargebacks can undermine your startup's financial stability. Comprehensive startup chargeback prevention techniques. Key steps to protect your merchant account from chargeback fraud. Role of payment processors and customer service in friendly fraud. Understanding Chargeback Prevention for Startup Merchant Accounts What Are Chargebacks and Why Do Startups Need Prevention? Chargebacks occur when a cardholder disputes a credit card charge directly with their issuing bank, prompting a reversal of funds from your merchant account. For startup merchants, frequent chargebacks aren’t just minor hiccups—they can lead to costly penalties, loss of payment processing privileges, or even a frozen bank account. This is why startup chargeback prevention is critical from day one. Startups often operate on slim margins, and a few unexpected reversals are enough to throw off cash flow, frustrate business owners, and threaten your bottom line. By prioritizing chargeback prevention, startups can proactively shield themselves against these setbacks, ensure smooth payment processing, and protect your revenue as you grow. For startups looking to further strengthen their defenses, understanding the legal and operational foundations of small business management is equally important. Exploring guidance for building a strong small business can provide additional strategies that complement your chargeback prevention efforts and support long-term stability. How Credit Card Chargeback Works in Startup Contexts A chargeback typically starts when a customer disputes a card charge with their card issuer, often citing fraud, dissatisfaction, or a failure in customer service. The card issuer then temporarily removes the funds from your account and starts the dispute process, collecting evidence from both the cardholder and merchant. For startups, responding quickly and providing compelling documentation is essential to prevent losing both the funds and customer trust. The process exposes founders to complex interactions with card companies and strict timelines set by the issuing bank. Failing to follow through can result in penalties, an increased chargeback ratio, and potential termination of your payment processing capabilities—underscoring the need for proactive chargeback management and robust prevention strategies. The Growing Importance of Chargeback Prevention Strategies for Startups Startups today face a landscape where fraudsters are more sophisticated and card charge disputes are on the rise. As card not present (CNP) transactions increase, so does exposure to friendly fraud and chargeback fraud. Prevention strategies go beyond simple transaction monitoring. They involve advanced fraud detection, swift customer service, and leveraging partnerships with the right payment processor. The earlier you establish chargeback prevention protocols, the better protected your startup will be from the start. Building these strategies helps prevent chargebacks, protect your business reputation, and positions your company to scale confidently—even in a challenging fintech environment. Chargeback Type Description Impacts Prevention Methods Card Charge Legitimate transaction later disputed by customer Loss of funds, higher chargeback ratio, potential account termination Clear billing, timely delivery, signature confirmation Fraudulent Chargeback Unauthorized or counterfeit credit card use Revenue loss, fines, increased costs of fraud prevention Fraud detection tools, AVS, CVV checks, EMV Friendly Fraud Customer falsely claims fraud/dispute to recover funds Loss of goods/services and funds, customer trust erosion Strong communication, order tracking, providing clear receipts How Chargebacks Disrupt Startup Businesses—and Why Startup Chargeback Prevention Matters Startup Chargeback Prevention and Its Direct Effects on Revenue and Growth Chargebacks directly chip away at your startup’s revenue and can stall growth in unexpected ways. Every disputed transaction not only results in lost income but also compounds into fees levied by card companies and payment processors. If your chargeback ratio rises above what the processor allows, you risk having your merchant account frozen or terminated. For startups, these penalties can rapidly escalate, making it essential to prevent chargebacks from the outset. Additionally, the financial stability of your business is threatened, as cash flow crunches limit your ability to invest in operations or marketing. Proactive chargeback prevention strategies are essential to safeguard your bottom line and allow uninterrupted growth, especially in the competitive early stages of business. Protecting Your Business from Card Chargeback Risks The risk of card chargebacks increases as your business grows. Effective startup chargeback prevention means identifying potential vulnerabilities in your payment systems and customer service, addressing them before they become liabilities. Integrating fraud detection software, authenticating credit card transactions, and educating your team on common causes of disputes can substantially reduce chargebacks. Remember, the goal is not just to recover lost funds, but to create an environment where disputes are minimized and your reputation remains intact. When founders make prevention a core business objective, they reduce the chances of merchant account loss, preserve cash flow, and protect your business for the long run. Case Study: How a Startup Lost Access to Its Payment Processor After Chargeback Fraud Consider the story of a SaaS founder whose business was thriving—until a wave of friendly fraud chargebacks hit their merchant account. Despite strong sales, the startup failed to respond promptly to disputes and lacked a systematic chargeback prevention plan. Their payment processor flagged the high chargeback ratio and, with little warning, shut off their merchant account. The founder struggled to secure a new processor, customers experienced service interruptions, and revenue came screeching to a halt. This highlights the real-world stakes of startup chargeback prevention: inaction leads to lost payment processing capabilities and, for many startups, a swift downward spiral. “Losing your merchant account is often just the first domino in a cascade of failures for startups.” Identifying the Main Causes of Chargebacks for Startups Common credit card chargeback scenarios in early-stage businesses. Role of customer service failures in creating avoidable disputes. Friendly fraud: What it is and why startups are vulnerable. Detecting and Preventing Friendly Fraud in Startups Friendly fraud, where a genuine customer falsely claims they didn’t receive the product or were charged erroneously, is especially dangerous for startups. Startups are more vulnerable because they may lack robust verification systems or proactive communication. Preventing friendly fraud requires clear receipts, detailed tracking, swift responses to customer complaints, and educating customers on your billing practices. Implementing automated fraud detection tools and working closely with your payment processor can help flag suspicious behavior. Ultimately, integrating prevention strategies into your daily operations will minimize losses from friendly fraud and maintain healthy customer relations. Payment Processor Rules and Card Charge Dispute Process Your payment processor has strict policies for responding to card chargebacks. The dispute process is time-sensitive: after a chargeback is initiated, you have a short window to provide evidence such as order confirmations, delivery proofs, and communication history. Failing to comply may result in financial penalties and jeopardize your merchant account. Understanding the rules—including chargeback thresholds and what the card issuer requires—puts startups at an advantage when navigating these disputes. Robust documentation and prompt communication with your processor are key components of effective chargeback management, ensuring you don’t lose disputes by default and that you protect your revenue as you grow. Startup Chargeback Prevention Strategies: Avoid Card Chargeback Pitfalls Top 10 startup chargeback prevention tips. Implementation of fraud prevention tools for early-stage businesses. Developing a proactive customer service approach for dispute resolution. “Investing in robust startup chargeback prevention techniques pays for itself.” Leveraging Payment Processor Solutions for Effective Startup Chargeback Prevention Payment processors are invaluable allies in preventing chargebacks. Advanced processors offer real-time alerts, fraud filters, and chargeback representment services tailored for startups. By selecting a processor equipped with the latest fraud detection tools, businesses immediately reduce their risk. Ensure your payment partner has experience with chargeback prevention, provides transparent reporting, and supports you in building airtight documentation. Such partnerships help founders stay one step ahead, enabling startups to focus on growth while safeguarding transaction stability and customer trust. Best Practices for Credit Card Charge Monitoring Monitoring every credit card charge—both for patterns of fraud and for customer satisfaction—is central to chargeback prevention. Implement daily transaction reviews, automated alerts for large or suspicious charges, and regular reconciliation of payments. Utilize your processor’s dashboards to spot anomalies early. This vigilance allows business owners to catch issues before they escalate, address disputes promptly, and maintain a healthy chargeback ratio. Incorporating these monitoring routines into your financial workflow means you’re always prepared to combat card chargeback issues. Integrating Fraud Detection for Ongoing Card Charge Protection Fraud detection solutions powered by AI and machine learning are now accessible even for startups. These tools automatically flag irregular purchase patterns, mismatched billing details, and high-risk locations before the transaction is completed. Startups benefit from integrating these technologies, as they help prevent chargebacks before they materialize, save hours of manual review, and add a crucial layer of security. By investing in ongoing fraud prevention technology, you protect your business, reduce chargebacks, and establish a reputation for secure and reliable payment processing. Startup Chargeback Fraud: Identifying and Responding to Threats Understanding Chargeback Fraud and Its Consequences for Startups Chargeback fraud occurs when a transaction is intentionally disputed under false pretenses, often by individuals exploiting loopholes in the payment system. For startups, the stakes are high: too many fraudulent chargebacks will not only cost you goods or services and transaction value, but also risk your merchant account status and brand reputation. Small businesses and startups are especially susceptible because their verification and disruption response may not match those of established enterprises. Proactive monitoring, advanced fraud detection tools, and documented evidence are essential defenses against this growing threat in the digital economy. How Startups Can Prevent Chargeback Fraud with Modern Technology Modern technology offers startups a variety of ways to prevent chargeback fraud effectively. Implementing AVS (Address Verification Service), CVV checks, two-factor authentication, and device fingerprinting minimizes unauthorized transactions. Machine learning-based fraud analytics can detect patterns and flag high-risk behavior before the sale completes. Combining these technological tools with timely customer communication significantly lowers the risk of chargeback fraud and demonstrates to both card providers and customers that you’re a vigilant merchant. Proactive defense is not just best practice; it’s essential to safeguard your business’s future. Step-by-Step Guide to Navigating the Dispute Process When a chargeback occurs, swift action is essential. First, promptly review the dispute notification from your payment processor, then gather all transaction records, delivery confirmations, and communication history with the customer. Next, prepare a clear, organized response and submit it through your payment processor’s chargeback dispute portal. Remain in communication with both the processor and your customer throughout the process. Consistent documentation and rapid response are the foundation of successful dispute resolution—giving your startup the best chance to recover funds and maintain a healthy merchant account standing. “Every successful dispute recovery is a lesson in startup resilience.” Customer Service as a Pillar of Startup Chargeback Prevention Creating Seamless Experiences to Preventing Chargebacks Exceptional customer service is one of the most effective ways to prevent chargebacks. By creating seamless and transparent customer journeys—from easy checkout processes to proactive support—founders drastically reduce the chances of a dispute ever arising. Resolve issues before they escalate and ensure customers have multiple channels to reach your team. Every positive experience is an insurance policy against chargebacks, friendly fraud, and reputational damage. Make customer satisfaction an integral part of your chargeback prevention strategies. How Fast, Transparent Communication Protects Your Revenue Clear, timely, and honest communication is central to protect your revenue. When an issue is detected, quick outreach can turn a potential dispute into an amicable resolution. Explain company policies, refund procedures, and dispute timelines transparently. By keeping customers in the loop, you demonstrate reliability, reduce frustration, and limit the tendency to file a chargeback. Staff should be empowered to solve problems efficiently—building loyalty and minimizing costly card chargeback events. Training Staff for Chargeback Prevention Excellence Your team is your first line of defense against chargebacks. Invest in regular training that covers identifying early signs of disputes, communicating chargeback policies with clarity, and using your payment processor’s chargeback management tools. Employees should understand how to interpret fraud alerts and manage the dispute process professionally. Ongoing training keeps your company’s prevention skills sharp as card company regulations and fraud tactics evolve. This culture of vigilance helps your startup avoid common pitfalls and lowers exposure to unnecessary financial risk. Startup Chargeback Prevention and the Role of Payment Processors How to Choose a Payment Processor With Strong Startup Chargeback Prevention Tools Selecting a payment processor capable of supporting your startup chargeback prevention goals is vital. Compare processors based on features like built-in fraud detection, chargeback reporting, threshold alerts, and transparent chargeback dispute support. Ask about experience working with startups and ensure they offer dedicated support for early-stage businesses. A processor invested in your success shares best practices and provides a partnership—not just a service—helping ensure your merchant account remains in good standing as you grow. Consider costs, integrations, and the quality of their chargeback prevention tools when making your selection. What to Know About Payment Processor Chargeback Dispute Procedures Familiarity with your processor’s chargeback dispute process can save you time and money. Know the documentation you need, the timeframes for response, escalation procedures, and what your processor requires for a successful dispute. Work with their support team to ensure your policies and evidence meet standards set by card issuers. This proactive approach allows founders to protect your business and learn from each dispute—constantly refining prevention measures for the future. Ask questions upfront and establish clear communication channels with your processor from the very beginning. Essential Fraud Detection and Prevention Tools for Startups Automated fraud detection for preventing card chargebacks. Benefits of AI-driven chargeback prevention solutions. Third-party tools for real-time monitoring and reporting. Documenting and Reporting for Startup Chargeback Prevention Keeping Accurate Records for Evidence in the Dispute Process Winning chargeback disputes depends on your ability to produce timely, accurate evidence. Maintain digital records of every transaction, communication, shipping confirmation, and refund. Use secure cloud storage or CRM systems that timestamp actions. This detailed documentation acts as your insurance policy in the event of a chargeback—providing compelling proof to card companies and payment processors. Dedicated record keeping is an investment in both financial safety and operational resilience, helping you reduce chargebacks and protect your merchant account for the long term. Best Practices for Documenting Customer Communication Every interaction with customers can serve as evidence in the dispute process. Ensure all communication (emails, chat transcripts, call logs) is stored systematically and linked with corresponding transactions. Set up standard templates for confirming orders, shipping updates, and issue resolution summaries. This not only streamlines chargeback management, but also strengthens customer trust. Well-documented communication satisfies card issuers’ evidence requirements and places your startup in the strongest possible position to recover revenue when challenged. Training and Education for Ongoing Startup Chargeback Prevention Internal policy creation for preventing chargebacks. Ongoing team training: Why it matters for long-term fraud prevention. Startup Chargeback Prevention Case Studies: Success Stories and Lessons Learned “Our chargebacks dropped by 70% after implementing comprehensive prevention strategies.” – A fintech founder Many emerging fintech businesses and SaaS startups have turned their fortunes around by adopting comprehensive startup chargeback prevention programs. These companies focused on deploying automated fraud detection, strengthening customer service, and closely monitoring card chargebacks. Within months, they saw massive reductions in disputed transactions, better payment processor relationships, and significant improvements to their bottom line. The lesson: preventative action, not reaction, makes all the difference in scaling a resilient company. Comparing Chargeback Prevention Solutions for Startups Tool Key Features Cost (Monthly) Effectiveness FraudShield Pro AI analytics, instant alerts, integrates with all major processors $49–$99 High for early-stage SaaS and ecommerce startups Chargeback Defender Automated representment, real-time resolution, chargeback reports $79–$129 Excellent for dispute-heavy businesses SecurePay Plus Manual review assist, chargeback dispute support, notification system $59–$99 Best for high-ticket-item startups Key Takeaways: Why Startup Chargeback Prevention Should Be Every Founder’s Priority Startup chargeback prevention is central to protecting your business and revenue. Effective strategies reduce the risk of merchant account loss. Ongoing education, customer service, and technology adoption are essential. Startup Chargeback Prevention FAQs What are the first steps to implement startup chargeback prevention? Start by selecting a payment processor with robust prevention features, train your staff, establish clear customer communication protocols, and implement real-time fraud detection tools. How can fintech startups prevent friendly fraud and chargeback fraud? Use transparent billing, keep comprehensive transaction records, respond quickly to customer inquiries, and consider AI-powered fraud detection to spot suspicious activity before it escalates. When do payment processors terminate merchant accounts for excessive card chargebacks? Most payment processors set a strict threshold; if your chargeback ratio exceeds 1% of your monthly transactions, you risk termination. Immediate action is critical if you approach this limit. Are automated fraud detection tools essential for startup chargeback prevention? Yes, especially as your transaction volume increases. Automation helps flag high-risk charges instantly, preventing fraudulent transactions from going through and reducing costly disputes. People Also Ask: Startup Chargeback Prevention How can startups reduce the risk of credit card chargebacks? Startups can reduce the risk of credit card chargebacks by using proactive communication, implementing clear billing descriptors, monitoring for suspicious transactions, providing accurate delivery timelines, and training teams to resolve issues quickly, all as part of a comprehensive startup chargeback prevention plan. What is the best chargeback prevention strategy for a new merchant account? The best strategy combines fraud detection tools, transparent customer service processes, clear refund policies, and ongoing documentation of every transaction. Leveraging your payment processor’s resources further reduces exposure to card chargebacks and ensures early-stage protection. How does startup chargeback prevention differ from traditional chargeback prevention? Startup chargeback prevention places more emphasis on rapid response and flexibility, using technology and internal training to overcome limited resources. Startups also require solutions tailored to high risk, low volume, and the unique challenges of scaling rapidly. Can a startup recover from excessive chargebacks? Yes, but recovery requires immediate action: lowering the chargeback rate, switching processors if necessary, improving fraud prevention systems, and retraining staff. Quick recovery strategies—backed by smarter documentation—restore merchant privileges and rebuild trust with partners. What role does customer service play in preventing chargebacks for startups? Exceptional customer service minimizes dispute escalation, resolves complaints promptly, and fosters transparency—all of which are proven to prevent chargebacks before they happen. It’s a fundamental pillar of effective startup chargeback prevention. Are all payment processors equal when it comes to startup chargeback prevention? No. Some processors offer specialized tools, dedicated support, and startup-focused solutions, while others have minimal prevention options. Research and choose a processor aligned with your business’s chargeback prevention needs to ensure the best protection. Ready to Secure Your Startup? Call for a Free Consultation at 214-854-9931 Conclusion: Startup chargeback prevention is not optional—it’s your safeguard to protecting revenue, ensuring scalable growth, and building a business that stands the test of time. Take action now to strengthen your defenses and allow your vision to thrive. As you continue to refine your chargeback prevention strategies, remember that building a resilient business goes beyond just managing disputes. By investing in the right legal, operational, and financial frameworks, you set the stage for sustainable growth and long-term success. For a deeper dive into foundational business practices that can further protect and empower your startup, consider reviewing comprehensive guidance for building a strong small business. This resource offers actionable insights that complement your chargeback prevention efforts and help you navigate the broader challenges of entrepreneurship with confidence.

About Us:

At Renwick Evans and Associates, we deliver tailored consulting strategies that support your business's unique journey toward growth and success.

We provide strategic guidance for small business owners seeking clarity, stability, and growth. Our services support businesses at every stage—from startup to expansion—through smart strategy and practical solutions.

Connect with Us:

Phone: 214-854-9931

Click to Call Now

{"name":"Call Footer","action_type":"3","optin_action_type":"5","form_redirect_type":"3","form_redirect_funnel_url":"uaahut61mb","form_redirect_custom_url":"","order_form_settings":{"containers":[{"id":"personal-info-wrapper","visible":true,"label":{"id":"of-personal-title","visible":true},"fields":[{"id":"of-full-name","setting":false,"placeholder":"Full Name"},{"id":"of-field-email","setting":false,"placeholder":"Email Address"},{"id":"of-phone-number","setting":true,"visible":false,"require":true,"placeholder":"Enter Your Mobile Phone","additional":{"sms_permission":0}},{"id":"of-gdpr-optin-approval","label":"I Accept To Receive Additional Info","placeholder":"","icon":"fa-mobile","required":0,"visible":0,"system":1,"additional":{"gdpr_optin_approval":"1"}}]},{"id":"shipping-information-wrapper","visible":false,"label":{"id":"of-shipping-title","visible":true},"fields":[{"id":"of-shipping-address","setting":false,"placeholder":"Address"},{"id":"of-shipping-city","setting":false,"placeholder":"City"},{"id":"of-shipping-state","setting":false,"placeholder":"State"},{"id":"of-shipping-zipcode","setting":false,"placeholder":"Postal Code"}]},{"id":"profit-bump-wrapper","visible":true,"otoBgColor":"rgba(219,229,239,1)","otoBorderColor":"rgba(38,71,102,1)","otoTitleBgColor":"rgba(45,78,108,1)","otoArrowsColor":"rgba(255,177,58,1)","fields":[]},{"id":"order-summary-wrapper","visible":true,"orderDynamicBgColor":"rgba(242,242,242,1)","orderDynamicTexColor":"rgba(51,51,51,1)","fields":[]}]},"optin_type":{"showLabels":0,"fields":[{"name":"first_name","label":"Full Name","placeholder":"Enter Your Full Name","icon":"fa-user","required":1,"visible":1,"system":1,"additional":{}},{"name":"last_name","label":"Full Name","placeholder":"Enter Your Full Name","icon":"fa-user","required":1,"visible":1,"system":1,"additional":{}},{"name":"email","label":"Email","placeholder":"Enter Your Email","icon":"fa-envelope","required":1,"visible":1,"system":1,"additional":{}},{"name":"mobile_phone","label":"Mobile Phone","placeholder":"Enter Your Mobile Phone","icon":"fa-mobile","required":0,"visible":0,"system":1,"additional":{"sms_permission":0}},{"name":"fields_labels","label":"","placeholder":"","icon":"","required":0,"visible":1,"system":1,"additional":{}},{"name":"captcha","label":"Captcha","placeholder":"","icon":"","required":1,"visible":1,"system":1,"additional":{}},{"name":"gdpr_optin_approval","label":"SSBBY2NlcHQgVG8gUmVjZWl2ZSBBZGRpdGlvbmFsIEluZm8=","placeholder":"","icon":"fa-mobile","required":0,"visible":1,"system":1,"additional":{"gdpr_optin_approval":"1","sms_permission":0}}],"customFields":[],"sortedFields":[{"name":"first_name","label":"Full Name","placeholder":"Enter Your Full Name","icon":"fa-user","required":1,"visible":1,"system":1,"additional":{}},{"name":"first_name","label":"Full Name","placeholder":"Enter Your Full Name","icon":"fa-user","required":1,"visible":1,"system":1,"additional":{}},{"name":"last_name","label":"Full Name","placeholder":"Enter Your Full Name","icon":"fa-user","required":1,"visible":1,"system":1,"additional":{}},{"name":"email","label":"Email","placeholder":"Enter Your Email","icon":"fa-envelope","required":1,"visible":1,"system":1,"additional":{}},{"name":"mobile_phone","label":"Mobile Phone","placeholder":"Enter Your Mobile Phone","icon":"fa-mobile","required":0,"visible":0,"system":1,"additional":{"sms_permission":0}},{"name":"captcha","label":"Captcha","placeholder":"","icon":"","required":1,"visible":1,"system":1,"additional":{}}],"design":{"form_background_color":"rgb(245, 245, 245)","field_stroke":{"size":"1","color":"rgb(220, 220, 220)"},"field_icons":1,"button_color":"rgb(255, 158, 0)","button_stroke":{"size":"0","color":"rgba(255, 255, 255, 0.2)"},"button_box_shadow_color":"none","field_size":"small","label_size":"16","label_color":"rgb(0, 0, 0)","input_color":"rgb(52, 152, 219)","control_text_color":"rgb(0, 0, 0)","control_text_size":"15"},"mappedFields":[]},"redirect_type":{"url":"","target":0},"next_step":{"value":"uaahut61mb"},"click_to_email":{"value":""},"click_to_call":{"value":"2148549931"},"jump_to_block":{},"content":{"header_text":"PHNwYW4gc3R5bGU9ImZvbnQtc2l6ZToyNHB4OyBmb250LWZhbWlseTonb3BlbiBzYW5zJzsiPjxzcGFuIHN0eWxlPSJsaW5lLWhlaWdodDoxLjRlbTsiPldlIEFyZSBFeGNpdGVkITwvc3Bhbj48L3NwYW4+","content_text":"PHNwYW4gc3R5bGU9ImZvbnQtc2l6ZTo0OHB4OyBmb250LWZhbWlseTonb3BlbiBzYW5zJzsiPjxzcGFuIHN0eWxlPSJsaW5lLWhlaWdodDowLjllbTsiPjxzdHJvbmc+UExFQVNFIEZJTEwgT1VUIFlPVVIgSU5GTyAgQkVMT1cgVE8gU1VCU0NSSUJFPC9zdHJvbmc+PC9zcGFuPjwvc3Bhbj4=","button_text":"PHNwYW4gc3R5bGU9ImZvbnQtc2l6ZToyN3B4OyBmb250LWZhbWlseTonb3BlbiBzYW5zJzsiPjxzcGFuIHN0eWxlPSJsaW5lLWhlaWdodDoxZW07Ij48c3Ryb25nPlNFQ1VSRSBNWSBTUE9UPC9zdHJvbmc+PC9zcGFuPjwvc3Bhbj4=","spam_text":"PHNwYW4gc3R5bGU9ImxpbmUtaGVpZ2h0OjEuMmVtOyI+V2UgaGF0ZSBTUEFNIGFuZCBwcm9taXNlIHRvIGtlZXAgeW91ciBlbWFpbCBhZGRyZXNzIHNhZmU8L3NwYW4+","sms_text":"UmVjZWl2ZSBTTVMgVGV4dCBVcGRhdGVzIC0gPHNwYW4+b3B0aW9uYWw8L3NwYW4+","sms_text2":"SSBBY2NlcHQgVG8gUmVjZWl2ZSBBZGRpdGlvbmFsIEluZm8="},"email_confirmation":{"enable":1,"subject":"V2UgQXJlIEV4Y2l0ZWQhIFlvdXIgSW4h","message":""},"integrations":[],"automation_enable":0,"thank_you":{"type":"popup","redirect_url":"","popup_options":{"background_color":"#ffffff","headline_visible":1,"icon_visible":1,"icon_url":"//my.funnelpages.com/assets-pb/images/thankyou-popup-icon.png","subheadline_visible":1,"button_visible":1,"button_color":"#ffa800","headline_text":"PHNwYW4gc3R5bGU9ImxpbmUtaGVpZ2h0OjEuNGVtOyI+VGhhbmsgWW91IEZvciBDb250YWN0aW5nIFVzPC9zcGFuPg==","subeadline_text":"PHNwYW4gc3R5bGU9ImxpbmUtaGVpZ2h0OjEuNGVtOyI+UGxlYXNlIENoZWNrIFlvdXIgRW1haWw8YnIgLz5XZSBXaWxsIEJlIEZvbGxvd2luZyBVcCBTaG9ydGx5PC9zcGFuPg==","button_text":"Q2xvc2U="}}}

Our Approach:

We believe strategy comes before solutions. By focusing on clarity, transparency, and measurable outcomes, we help business owners make informed decisions that move their businesses forward.

Our mission is to help small businesses rise to new heights through clear strategy, smarter systems, and confident decision-making.

© 2026 Renwick Evans & Associates All Rights Reserved. 5318 S. Hampton Rd. , Dallas, TX 75232. Contact Us. Terms of Service . Privacy Policy

This website contains content that has been created using AI. Results created with AI can be inaccurate, unreliable, and subject to hallucinations. Renwick Evans & Associates disclaims any and all liability arising from use of its AI tool or services. Results created with AI are generally not protectable under intellectual property law, so Users assume all risk associated with potential liability and non-protectability arising from its use. For further details, see the Terms, available above.
eyJjb21wYW55IjoiUmVud2ljayBFdmFucyAmIEFzc29jaWF0ZXMiLCJhZGRyZXNzIjoiNTMxOCBTLiBIYW1wdG9uIFJkLiAgIiwiY2l0eSI6IkRhbGxhcyIsInN0YXRlIjoiVFgiLCJ6aXAiOiI3NTIzMiIsImVtYWlsIjoicmVud2lja0ByZW53aWNrZXZhbnMuY29tIiwidG9zIjoiUEhBK1BITjBjbTl1Wno0OFpXMCtWMmhsYmlCNWIzVWdjMmxuYmkxcGJpQjNhWFJvSUhWekxDQjViM1VnWVhKbElHZHBkbWx1WnladVluTndPeUI1YjNWeUlIQmxjbTFwYzNOcGIyNGdZVzVrSUdOdmJuTmxiblFnZEc4Z2MyVnVaQ0I1YjNVZ1pXMWhhV3dnWVc1a0wyOXlJRk5OVXlCMFpYaDBJRzFsYzNOaFoyVnpMaUJDZVNCamFHVmphMmx1WnlCMGFHVWdWR1Z5YlhNZ1lXNWtJRU52Ym1ScGRHbHZibk1nWW05NElHRnVaQ0JpZVNCemFXZHVhVzVuSUdsdUlIbHZkU0JoZFhSdmJXRjBhV05oYkd4NUlHTnZibVpwY20wZ2RHaGhkQ0I1YjNVZ1lXTmpaWEIwSUdGc2JDQjBaWEp0Y3lCcGJpQjBhR2x6SUdGbmNtVmxiV1Z1ZEM0OEwyVnRQand2YzNSeWIyNW5Qand2Y0Q0S0NqeHdQaVp1WW5Od096d3ZjRDRLQ2p4d1BqeHpkSEp2Ym1jK1UwVlNWa2xEUlR3dmMzUnliMjVuUGp3dmNENEtDanh3UGxkbElIQnliM1pwWkdVZ1lTQnpaWEoyYVdObElIUm9ZWFFnWTNWeWNtVnVkR3g1SUdGc2JHOTNjeUI1YjNVZ2RHOGdjbVZqWldsMlpTQnlaWEYxWlhOMGN5Qm1iM0lnWm1WbFpHSmhZMnNzSUdOdmJYQmhibmtnYVc1bWIzSnRZWFJwYjI0c0lIQnliMjF2ZEdsdmJtRnNJR2x1Wm05eWJXRjBhVzl1TENCamIyMXdZVzU1SUdGc1pYSjBjeXdnWTI5MWNHOXVjeXdnWkdselkyOTFiblJ6SUdGdVpDQnZkR2hsY2lCdWIzUnBabWxqWVhScGIyNXpJSFJ2SUhsdmRYSWdaVzFoYVd3Z1lXUmtjbVZ6Y3lCaGJtUXZiM0lnWTJWc2JIVnNZWElnY0dodmJtVWdiM0lnWkdWMmFXTmxMaUJaYjNVZ2RXNWtaWEp6ZEdGdVpDQmhibVFnWVdkeVpXVWdkR2hoZENCMGFHVWdVMlZ5ZG1salpTQnBjeUJ3Y205MmFXUmxaQ0FtY1hWdmREdEJVeTFKVXlaeGRXOTBPeUJoYm1RZ2RHaGhkQ0IzWlNCaGMzTjFiV1VnYm04Z2NtVnpjRzl1YzJsaWFXeHBkSGtnWm05eUlIUm9aU0IwYVcxbGJHbHVaWE56TENCa1pXeGxkR2x2Yml3Z2JXbHpMV1JsYkdsMlpYSjVJRzl5SUdaaGFXeDFjbVVnZEc4Z2MzUnZjbVVnWVc1NUlIVnpaWElnWTI5dGJYVnVhV05oZEdsdmJuTWdiM0lnY0dWeWMyOXVZV3hwZW1GMGFXOXVJSE5sZEhScGJtZHpMand2Y0Q0S0NqeHdQbGx2ZFNCaGNtVWdjbVZ6Y0c5dWMybGliR1VnWm05eUlHOWlkR0ZwYm1sdVp5QmhZMk5sYzNNZ2RHOGdkR2hsSUZObGNuWnBZMlVnWVc1a0lIUm9ZWFFnWVdOalpYTnpJRzFoZVNCcGJuWnZiSFpsSUhSb2FYSmtJSEJoY25SNUlHWmxaWE1nS0hOMVkyZ2dZWE1nVTAxVElIUmxlSFFnYldWemMyRm5aWE1zSUVsdWRHVnlibVYwSUhObGNuWnBZMlVnY0hKdmRtbGtaWElnYjNJZ1kyVnNiSFZzWVhJZ1lXbHlkR2x0WlNCamFHRnlaMlZ6S1M0Z1dXOTFJR0Z5WlNCeVpYTndiMjV6YVdKc1pTQm1iM0lnZEdodmMyVWdabVZsY3l3Z2FXNWpiSFZrYVc1bklIUm9iM05sSUdabFpYTWdZWE56YjJOcFlYUmxaQ0IzYVhSb0lIUm9aU0JrYVhOd2JHRjVJRzl5SUdSbGJHbDJaWEo1SUc5bUlHVmhZMmdnVTAxVElIUmxlSFFnYldWemMyRm5aU0J6Wlc1MElIUnZJSGx2ZFNCaWVTQjFjeTRnU1c0Z1lXUmthWFJwYjI0c0lIbHZkU0J0ZFhOMElIQnliM1pwWkdVZ1lXNWtJR0Z5WlNCeVpYTndiMjV6YVdKc1pTQm1iM0lnWVd4c0lHVnhkV2x3YldWdWRDQnVaV05sYzNOaGNua2dkRzhnWVdOalpYTnpJSFJvWlNCVFpYSjJhV05sSUdGdVpDQnlaV05sYVhabElIUm9aU0JUVFZNZ2RHVjRkQ0J0WlhOellXZGxjeTRnVjJVZ1pHOGdibTkwSUdOb1lYSm5aU0JoYm5rZ1ptVmxjeUJtYjNJZ1pHVnNhWFpsY25rZ2IyWWdaVzFoYVd3Z2IzSWdVMDFUTGlCVWFHbHpJR2x6SUdFZ1puSmxaU0J6WlhKMmFXTmxJSEJ5YjNacFpHVmtJR0o1SUhWekxpQkliM2RsZG1WeUxDQndiR1ZoYzJVZ1kyaGxZMnNnZDJsMGFDQjViM1Z5SUdsdWRHVnlibVYwSUhObGNuWnBZMlVnY0hKdmRtbGtaWElnWVc1a0lHTmxiR3gxYkdGeUlHTmhjbkpwWlhJZ1ptOXlJR0Z1ZVNCamFHRnlaMlZ6SUhSb1lYUWdiV0Y1SUdsdVkzVnlJR0Z6SUdFZ2NtVnpkV3gwSUdaeWIyMGdjbVZqWldsMmFXNW5JR1Z0WVdsc0lHRnVaQ0JUVFZNZ2RHVjRkQ0J0WlhOellXZGxjeUIwYUdGMElIZGxJR1JsYkdsMlpYSWdkWEJ2YmlCNWIzVnlJRzl3ZEMxcGJpQmhibVFnY21WbmFYTjBjbUYwYVc5dUlIZHBkR2dnYjNWeUlHVnRZV2xzSUdGdVpDQlRUVk1nYzJWeWRtbGpaWE11SUZsdmRTQmpZVzRnWTJGdVkyVnNJR0YwSUdGdWVTQjBhVzFsTGlCS2RYTjBJSFJsZUhRZ0puRjFiM1E3VTFSUFVDWnhkVzkwT3lCMGJ5WnVZbk53T3p4b2FXZG9iR2xuYUhRZ1kyeGhjM005SW1OdmJYQmhibmxUVFZOUWFHOXVaVlZ3WkdGMFpTSStiblZzYkR3dmFHbG5hR3hwWjJoMFBpNGdRV1owWlhJZ2VXOTFJSE5sYm1RZ2RHaGxJRk5OVXlCdFpYTnpZV2RsSUNaeGRXOTBPMU5VVDFBbWNYVnZkRHNnZEc4Z2RYTXNJSGRsSUhkcGJHd2djMlZ1WkNCNWIzVWdZVzRnVTAxVElHMWxjM05oWjJVZ2RHOGdZMjl1Wm1seWJTQjBhR0YwSUhsdmRTQm9ZWFpsSUdKbFpXNGdkVzV6ZFdKelkzSnBZbVZrTGlCQlpuUmxjaUIwYUdsekxDQjViM1VnZDJsc2JDQnVieUJzYjI1blpYSWdjbVZqWldsMlpTQlRUVk1nYldWemMyRm5aWE1nWm5KdmJTQjFjeTQ4TDNBK0NnbzhjRDQ4YzNSeWIyNW5QbGxQVlZJZ1VrVkhTVk5VVWtGVVNVOU9JRTlDVEVsSFFWUkpUMDVUUEM5emRISnZibWMrUEM5d1Bnb0tQSEErU1c0Z1kyOXVjMmxrWlhKaGRHbHZiaUJ2WmlCNWIzVnlJSFZ6WlNCdlppQjBhR1VnVTJWeWRtbGpaU3dnZVc5MUlHRm5jbVZsSUhSdk9qd3ZjRDRLQ2p4dmJENEtDVHhzYVQ1d2NtOTJhV1JsSUhSeWRXVXNJR0ZqWTNWeVlYUmxMQ0JqZFhKeVpXNTBJR0Z1WkNCamIyMXdiR1YwWlNCcGJtWnZjbTFoZEdsdmJpQmhZbTkxZENCNWIzVnljMlZzWmlCaGN5QndjbTl0Y0hSbFpDQmllU0IwYUdVZ1UyVnlkbWxqWlNZak16azdjeUJ5WldkcGMzUnlZWFJwYjI0Z1ptOXliU0FvYzNWamFDQnBibVp2Y20xaGRHbHZiaUJpWldsdVp5QjBhR1VnSm5GMWIzUTdVbVZuYVhOMGNtRjBhVzl1SUVSaGRHRW1jWFZ2ZERzcElHRnVaRHd2YkdrK0NnazhiR2srYldGcGJuUmhhVzRnWVc1a0lIQnliMjF3ZEd4NUlIVndaR0YwWlNCMGFHVWdVbVZuYVhOMGNtRjBhVzl1SUVSaGRHRWdkRzhnYTJWbGNDQnBkQ0IwY25WbExDQmhZMk4xY21GMFpTd2dZM1Z5Y21WdWRDQmhibVFnWTI5dGNHeGxkR1V1SUVsbUlIbHZkU0J3Y205MmFXUmxJR0Z1ZVNCcGJtWnZjbTFoZEdsdmJpQjBhR0YwSUdseklIVnVkSEoxWlN3Z2FXNWhZMk4xY21GMFpTd2dibTkwSUdOMWNuSmxiblFnYjNJZ2FXNWpiMjF3YkdWMFpTd2diM0lnZDJVZ2FHRjJaU0J5WldGemIyNWhZbXhsSUdkeWIzVnVaSE1nZEc4Z2MzVnpjR1ZqZENCMGFHRjBJSE4xWTJnZ2FXNW1iM0p0WVhScGIyNGdhWE1nZFc1MGNuVmxMQ0JwYm1GalkzVnlZWFJsTENCdWIzUWdZM1Z5Y21WdWRDQnZjaUJwYm1OdmJYQnNaWFJsTENCM1pTQm9ZWFpsSUhSb1pTQnlhV2RvZENCMGJ5QnpkWE53Wlc1a0lHOXlJRHh6ZEhKdmJtYytQSE53WVc0Z2MzUjViR1U5SW1OdmJHOXlPaU5HUmpBd01EQTdJajUwWlhKdGFXNWhkR1VnZVc5MWNpQmhZMk52ZFc1MEwzQnliMlpwYkdVZ1lXNWtJSEpsWm5WelpTQmhibmtnWVc1a0lHRnNiQ0JqZFhKeVpXNTBJRzl5SUdaMWRIVnlaU0IxYzJVZ2IyWWdkR2hsSUZObGNuWnBZMlVnS0c5eUlHRnVlU0J3YjNKMGFXOXVJSFJvWlhKbGIyWXBMand2YzNCaGJqNDhMM04wY205dVp6NDhMMnhwUGdvOEwyOXNQZ29LUEhBK0ptNWljM0E3UEM5d1BnbzhhR2xuYUd4cFoyaDBJR05zWVhOelBTSmpiMjF3WVc1NVRtRnRaVlZ3WkdGMFpTSStVbVZ1ZDJsamF5QkZkbUZ1Y3lBbVlXMXdPeUJCYzNOdlkybGhkR1Z6UEM5b2FXZG9iR2xuYUhRK1BHSnlJQzgrQ2p4b2FXZG9iR2xuYUhRZ1kyeGhjM005SW1OdmJYQmhibmxCWkdSeVpYTnpWWEJrWVhSbElqNDFNekU0SUZNdUlFaGhiWEIwYjI0Z1VtUXVJQ3dnUkdGc2JHRnpMQ0JVV0NBM05USXpNand2YUdsbmFHeHBaMmgwUGp4aWNpQXZQZ284YUdsbmFHeHBaMmgwSUdOc1lYTnpQU0pqYjIxd1lXNTVVR2h2Ym1WVmNHUmhkR1VpUGp3dmFHbG5hR3hwWjJoMFBqeGljaUF2UGdvOGFHbG5hR3hwWjJoMElHTnNZWE56UFNKamIyMXdZVzU1UlcxaGFXeFZjR1JoZEdVaVBuSmxibmRwWTJzb1FDbHlaVzUzYVdOclpYWmhibk11WTI5dFBDOW9hV2RvYkdsbmFIUSsiLCJwcml2YWN5IjoiUEhBK1BITjBjbTl1Wno1UVVrbFdRVU5aUEM5emRISnZibWMrUEM5d1Bnb0tQSEErUEhOMGNtOXVaejVVYUdVZ2FXNW1iM0p0WVhScGIyNGdjSEp2ZG1sa1pXUWdaSFZ5YVc1bklIUm9hWE1nY21WbmFYTjBjbUYwYVc5dUlHbHpJR3RsY0hRZ2NISnBkbUYwWlNCaGJtUWdZMjl1Wm1sa1pXNTBhV0ZzTENCaGJtUWdkMmxzYkNCdVpYWmxjaUJpWlNCa2FYTjBjbWxpZFhSbFpDd2dZMjl3YVdWa0xDQnpiMnhrTENCMGNtRmtaV1FnYjNJZ2NHOXpkR1ZrSUdsdUlHRnVlU0IzWVhrc0lITm9ZWEJsSUc5eUlHWnZjbTB1SUZSb2FYTWdhWE1nYjNWeUlHZDFZWEpoYm5SbFpTNDhMM04wY205dVp6NDhMM0ErQ2dvOGNENDhjM1J5YjI1blBrbE9SRVZOVGtsVVdUd3ZjM1J5YjI1blBqd3ZjRDRLQ2p4d1BqeGxiVDVaYjNVZ1lXZHlaV1VnZEc4Z2FXNWtaVzF1YVdaNUlHRnVaQ0JvYjJ4a0lIVnpMQzRnWVc1a0lHbDBjeUJ6ZFdKemFXUnBZWEpwWlhNc0lHRm1abWxzYVdGMFpYTXNJRzltWm1salpYSnpMQ0JoWjJWdWRITXNJR052TFdKeVlXNWtaWEp6SUc5eUlHOTBhR1Z5SUhCaGNuUnVaWEp6TENCaGJtUWdaVzF3Ykc5NVpXVnpMQ0JvWVhKdGJHVnpjeUJtY205dElHRnVlU0JqYkdGcGJTQnZjaUJrWlcxaGJtUXNJR2x1WTJ4MVpHbHVaeUJ5WldGemIyNWhZbXhsSUdGMGRHOXlibVY1Y3lZak16azdJR1psWlhNc0lHMWhaR1VnWW5rZ1lXNTVJSFJvYVhKa0lIQmhjblI1SUdSMVpTQjBieUJ2Y2lCaGNtbHphVzVuSUc5MWRDQnZaaUJEYjI1MFpXNTBJSGx2ZFNCeVpXTmxhWFpsTENCemRXSnRhWFFzSUhKbGNHeDVMQ0J3YjNOMExDQjBjbUZ1YzIxcGRDQnZjaUJ0WVd0bElHRjJZV2xzWVdKc1pTQjBhSEp2ZFdkb0lIUm9aU0JUWlhKMmFXTmxMQ0I1YjNWeUlIVnpaU0J2WmlCMGFHVWdVMlZ5ZG1salpTd2dlVzkxY2lCamIyNXVaV04wYVc5dUlIUnZJSFJvWlNCVFpYSjJhV05sTENCNWIzVnlJSFpwYjJ4aGRHbHZiaUJ2WmlCMGFHVWdWRTlUTENCdmNpQjViM1Z5SUhacGIyeGhkR2x2YmlCdlppQmhibmtnY21sbmFIUnpJRzltSUdGdWIzUm9aWEl1UEM5bGJUNDhMM0ErQ2dvOGNENDhjM1J5YjI1blBrUkpVME5NUVVsTlJWSWdUMFlnVjBGU1VrRk9WRWxGVXp3dmMzUnliMjVuUGp3dmNENEtDanh3UGp4emRISnZibWMrV1U5VklFVllVRkpGVTFOTVdTQlZUa1JGVWxOVVFVNUVJRUZPUkNCQlIxSkZSU0JVU0VGVU9qd3ZjM1J5YjI1blBqd3ZjRDRLQ2p4dmJENEtDVHhzYVQ1WlQxVlNJRlZUUlNCUFJpQlVTRVVnVTBWU1ZrbERSU0JKVXlCQlZDQlpUMVZTSUZOUFRFVWdVa2xUU3k0Z1ZFaEZJRk5GVWxaSlEwVWdTVk1nVUZKUFZrbEVSVVFnVDA0Z1FVNGdKbkYxYjNRN1FWTWdTVk1tY1hWdmREc2dRVTVFSUNaeGRXOTBPMEZUSUVGV1FVbE1RVUpNUlNaeGRXOTBPeUJDUVZOSlV5NGdMQzRnUVU1RUlGVlRMQ0JKVkNZak16azdVeUJEVlZOVVQwMUZVbE1zSUVWWVVGSkZVMU5NV1NCRVNWTkRURUZKVFZNZ1FVeE1JRmRCVWxKQlRsUkpSVk1nVDBZZ1FVNVpJRXRKVGtRc0lGZElSVlJJUlZJZ1JWaFFVa1ZUVXlCUFVpQkpUVkJNU1VWRUxDQkpUa05NVlVSSlRrY3NJRUpWVkNCT1QxUWdURWxOU1ZSRlJDQlVUeUJVU0VVZ1NVMVFURWxGUkNCWFFWSlNRVTVVU1VWVElFOUdJRTFGVWtOSVFVNVVRVUpKVEVsVVdTd2dSa2xVVGtWVFV5QkdUMUlnUVNCUVFWSlVTVU5WVEVGU0lGQlZVbEJQVTBVZ1FVNUVJRTVQVGkxSlRrWlNTVTVIUlUxRlRsUXVQQzlzYVQ0S0NUeHNhVDVOUVV0RlV5Qk9UeUJYUVZKU1FVNVVXU0JVU0VGVUlDaHBLU0JVU0VVZ1UwVlNWa2xEUlNCWFNVeE1JRTFGUlZRZ1dVOVZVaUJTUlZGVlNWSkZUVVZPVkZNc0lDaHBhU2tnVkVoRklGTkZVbFpKUTBVZ1YwbE1UQ0JDUlNCVlRrbE9WRVZTVWxWUVZFVkVMQ0JVU1UxRlRGa3NJRk5GUTFWU1JTd2dUMUlnUlZKU1QxSXRSbEpGUlN3Z0tHbHBhU2tnVkVoRklGSkZVMVZNVkZNZ1ZFaEJWQ0JOUVZrZ1FrVWdUMEpVUVVsT1JVUWdSbEpQVFNCVVNFVWdWVk5GSUU5R0lGUklSU0JUUlZKV1NVTkZJRmRKVEV3Z1FrVWdRVU5EVlZKQlZFVWdUMUlnVWtWTVNVRkNURVVzSUVGT1JDQW9hWFlwSUVGT1dTQkZVbEpQVWxNZ1NVNGdWRWhGSUZOUFJsUlhRVkpGSUZkSlRFd2dRa1VnUTA5U1VrVkRWRVZFTGp3dmJHaytDZ2s4YkdrK1FVNVpJRTFCVkVWU1NVRk1JRVJQVjA1TVQwRkVSVVFnVDFJZ1QxUklSVkpYU1ZORklFOUNWRUZKVGtWRUlGUklVazlWUjBnZ1ZFaEZJRlZUUlNCUFJpQlVTRVVnVTBWU1ZrbERSU0JKVXlCRVQwNUZJRUZVSUZsUFZWSWdUMWRPSUVSSlUwTlNSVlJKVDA0Z1FVNUVJRkpKVTBzZ1FVNUVJRlJJUVZRZ1dVOVZJRmRKVEV3Z1FrVWdVMDlNUlV4WklGSkZVMUJQVGxOSlFreEZJRVpQVWlCQlRsa2dSRUZOUVVkRklGUlBJRmxQVlZJZ1EwOU5VRlZVUlZJZ1UxbFRWRVZOSUU5U0lFeFBVMU1nVDBZZ1JFRlVRU0JVU0VGVUlGSkZVMVZNVkZNZ1JsSlBUU0JVU0VVZ1JFOVhUa3hQUVVRZ1QwWWdRVTVaSUZOVlEwZ2dUVUZVUlZKSlFVd3VQQzlzYVQ0S0NUeHNhVDVPVHlCQlJGWkpRMFVnVDFJZ1NVNUdUMUpOUVZSSlQwNHNJRmRJUlZSSVJWSWdUMUpCVENCUFVpQlhVa2xVVkVWT0xDQlBRbFJCU1U1RlJDQkNXU0JaVDFVZ1JsSlBUU0JQVWlCVVNGSlBWVWRJSUU5U0lFWlNUMDBnVkVoRklGTkZVbFpKUTBVZ1UwaEJURXdnUTFKRlFWUkZJRUZPV1NCWFFWSlNRVTVVV1NCT1QxUWdSVmhRVWtWVFUweFpJRk5VUVZSRlJDQkpUaUJVU0VVZ1ZFOVRMand2YkdrK0Nqd3ZiMncrQ2dvOGNENDhjM1J5YjI1blBreEpUVWxVUVZSSlQwNGdUMFlnVEVsQlFrbE1TVlJaUEM5emRISnZibWMrUEM5d1Bnb0tQSEErV1U5VklFVllVRkpGVTFOTVdTQlZUa1JGVWxOVVFVNUVJRUZPUkNCQlIxSkZSU0JVU0VGVUlFRk9SQ0JUU0VGTVRDQk9UMVFnUWtVZ1RFbEJRa3hGSUVaUFVpQkJUbGtnUkVsU1JVTlVMQ0JKVGtSSlVrVkRWQ3dnU1U1RFNVUkZUbFJCVEN3Z1UxQkZRMGxCVEN3Z1EwOU9VMFZSVlVWT1ZFbEJUQ0JQVWlCRldFVk5VRXhCVWxrZ1JFRk5RVWRGVXl3Z1NVNURURlZFU1U1SElFSlZWQ0JPVDFRZ1RFbE5TVlJGUkNCVVR5d2dSRUZOUVVkRlV5QkdUMUlnVEU5VFV5QlBSaUJRVWs5R1NWUlRMQ0JIVDA5RVYwbE1UQ3dnVlZORkxDQkVRVlJCSUU5U0lFOVVTRVZTSUVsT1ZFRk9SMGxDVEVVZ1RFOVRVMFZUSUNoRlZrVk9JRWxHSUVoQlV5QkNSVVZPSUVGRVZrbFRSVVFnVDBZZ1ZFaEZJRkJQVTFOSlFrbE1TVlJaSUU5R0lGTlZRMGdnUkVGTlFVZEZVeWtzSUZKRlUxVk1WRWxPUnlCR1VrOU5Pand2Y0Q0S0NqeHZiRDRLQ1R4c2FUNVVTRVVnVlZORklFOVNJRlJJUlNCSlRrRkNTVXhKVkZrZ1ZFOGdWVk5GSUZSSVJTQlRSVkpXU1VORk96d3ZiR2srQ2drOGJHaytWRWhGSUVOUFUxUWdUMFlnVUZKUFExVlNSVTFGVGxRZ1QwWWdVMVZDVTFSSlZGVlVSU0JIVDA5RVV5QkJUa1FnVTBWU1ZrbERSVk1nVWtWVFZVeFVTVTVISUVaU1QwMGdRVTVaSUVkUFQwUlRMQ0JFUVZSQkxDQkpUa1pQVWsxQlZFbFBUaUJQVWlCVFJWSldTVU5GVXlCUVZWSkRTRUZUUlVRZ1QxSWdUMEpVUVVsT1JVUWdUMUlnVFVWVFUwRkhSVk1nVWtWRFJVbFdSVVFnVDFJZ1ZGSkJUbE5CUTFSSlQwNVRJRVZPVkVWU1JVUWdTVTVVVHlCVVNGSlBWVWRJSUU5U0lFWlNUMDBnVkVoRklGTkZVbFpKUTBVN1BDOXNhVDRLQ1R4c2FUNVZUa0ZWVkVoUFVrbGFSVVFnUVVORFJWTlRJRlJQSUU5U0lFRk1WRVZTUVZSSlQwNGdUMFlnV1U5VlVpQlVVa0ZPVTAxSlUxTkpUMDVUSUU5U0lFUkJWRUU3UEM5c2FUNEtDVHhzYVQ1VFZFRlVSVTFGVGxSVElFOVNJRU5QVGtSVlExUWdUMFlnUVU1WklGUklTVkpFSUZCQlVsUlpJRTlPSUZSSVJTQlRSVkpXU1VORk95QlBVand2YkdrK0NnazhiR2srUVU1WklFOVVTRVZTSUUxQlZGUkZVaUJTUlV4QlZFbE9SeUJVVHlCVVNFVWdVMFZTVmtsRFJTNDhMMnhwUGdvOEwyOXNQZ29LUEhBK1BIVStRbmtnY21WbmFYTjBaWEpwYm1jZ1lXNWtJSE4xWW5OamNtbGlhVzVuSUhSdklHOTFjaUJsYldGcGJDQmhibVFnVTAxVElITmxjblpwWTJVc0lHSjVJRzl3ZEMxcGJpd2diMjVzYVc1bElISmxaMmx6ZEhKaGRHbHZiaUJ2Y2lCaWVTQm1hV3hzYVc1bklHOTFkQ0JoSUdOaGNtUXNJQ1p4ZFc5ME8zbHZkU0JoWjNKbFpTQjBieUIwYUdWelpTQlVSVkpOVXlCUFJpQlRSVkpXU1VORkpuRjFiM1E3SUdGdVpDQjViM1VnWVdOcmJtOTNiR1ZrWjJVZ1lXNWtJSFZ1WkdWeWMzUmhibVFnZEdobElHRmliM1psSUhSbGNtMXpJRzltSUhObGNuWnBZMlVnYjNWMGJHbHVaV1FnWVc1a0lHUmxkR0ZwYkdWa0lHWnZjaUI1YjNVZ2RHOWtZWGt1UEM5MVBqd3ZjRDRLQ2p4d1BpWnVZbk53T3p3dmNENEtVbVZ1ZDJsamF5QkZkbUZ1Y3lBbVlXMXdPeUJCYzNOdlkybGhkR1Z6UEdKeUlDOCtDalV6TVRnZ1V5NGdTR0Z0Y0hSdmJpQlNaQzRnTENCRVlXeHNZWE1zSUZSWUlEYzFNak15UEdKeUlDOCtDanhpY2lBdlBncHlaVzUzYVdOcktFQXBjbVZ1ZDJsamEyVjJZVzV6TG1OdmJRPT0ifQ==

Terms of Service

Privacy Policy

Core Modal Title

Sorry, no results found

You Might Find These Articles Interesting

T
Please Check Your Email
We Will Be Following Up Shortly
*
*
*